Wednesday, 4 November 2026

A Complete Guide to Antique Diamond Cuts: History, Styles and the Beauty of Old-Cut Diamonds

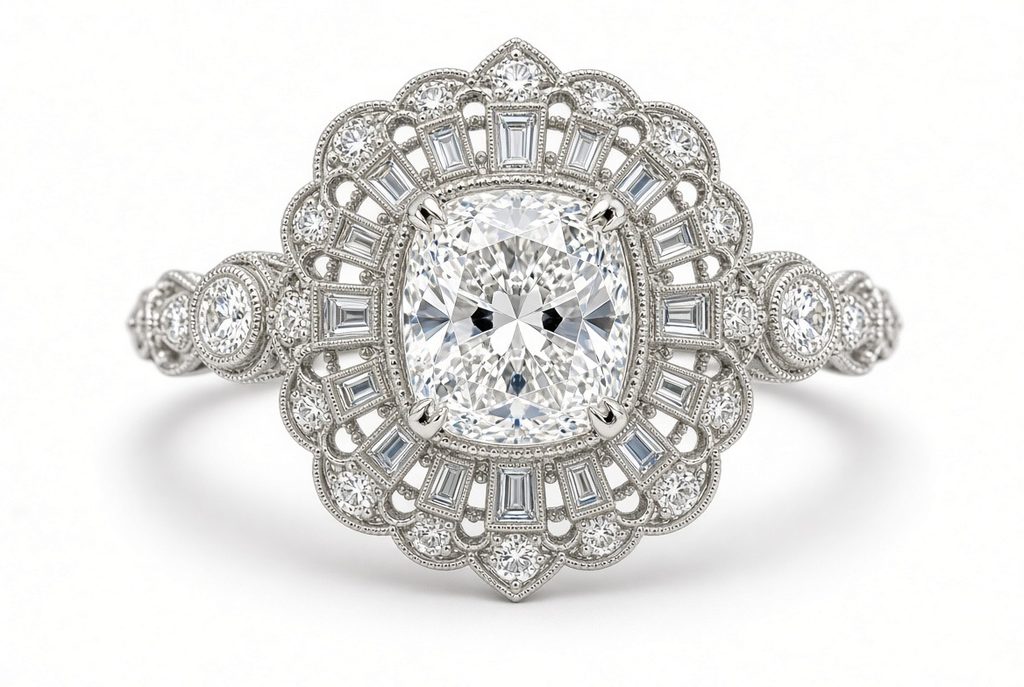
 The Cushion Cut evolved from earlier antique diamond shapes, including the Old Mine Cut.Its rounded corners and square or rectangular outline give it the appearance of a cushion.Depending on the period and cutting style, cushion diamonds can have broad facets, smaller brilliant-style facets or a combination of both.

For centuries, diamonds have captivated people not only because of their rarity and beauty, but also because of the extraordinary skill required to transform a rough crystal into a polished gemstone. Long before modern diamond-cutting technology, master craftsmen developed ingenious techniques to reveal the beauty hidden within each stone.

Today, as jewellery trends increasingly embrace individuality, heritage and craftsmanship, antique and old-cut diamonds are enjoying renewed appreciation. From the soft, romantic shimmer of a Rose Cut to the distinctive chunky facets of an Old Mine Cut, these historic cutting styles offer something quite different from the precise, high-brilliance diamonds commonly seen in contemporary jewellery.

An old-cut diamond is not simply an outdated version of a modern brilliant. It represents a different philosophy of craftsmanship, shaped by the technology, tools, lighting conditions and aesthetic preferences of its time.

Understanding these historic cuts provides a fascinating insight into the evolution of the diamond industry and helps explain why some of these stones are now highly sought after by collectors, antique jewellery enthusiasts and those looking for something genuinely individual.

The Early History of

Diamonds were treasured for thousands of years before the development of modern cutting techniques. Initially, they were valued largely for their natural shape, exceptional hardness and rarity. Early diamond traders and jewellers often used polished natural crystals rather than attempting elaborate cutting.

The earliest documented diamond-cutting techniques were relatively simple. Craftsmen gradually discovered that diamonds could be shaped and polished using diamond powder, eventually developing more sophisticated methods to create facets and improve their appearance.

As trade routes expanded and diamond centres developed across Europe, particularly in Venice, Bruges, Antwerp, Paris and Amsterdam, cutting techniques became increasingly refined.

The development of diamond-cutting technology was closely connected to the availability of mechanical tools, the understanding of diamond crystal structure and the growing demand for more brilliant gemstones.

The following historic cuts represent important stages in this evolution.

The Historic Diamond Cuts and Their Characteristics

1. The Point Cut – 14th to 15th Century

The Point Cut is among the earliest recognised diamond-cutting styles.

Rather than creating a series of facets, the cutter followed the natural octahedral shape of the rough diamond, polishing its existing crystal faces while retaining much of its original form.

The result was a pointed, largely unmodified diamond that preserved the natural geometry of the crystal.

These early stones were often used in medieval jewellery, particularly in rings and religious ornaments. Their appearance was considerably different from the brilliant diamonds we recognise today.

2. The Table Cut – 15th to 16th Century

The Table Cut represented an important advancement in diamond cutting.

By removing the top point of an octahedral crystal, cutters created a flat table facet. The corners could also be slightly truncated, introducing additional facets and improving the stone’s appearance.

Table Cuts became popular during the Renaissance and were frequently used in European royal and aristocratic jewellery.

Some examples featured a relatively large table and a small culet, the flat facet at the bottom of the diamond.

Their understated appearance reflects an era when symmetry, shape and the natural character of the diamond were often more important than maximum brilliance.

3. The Rose Cut – 16th Century Onwards

<PRIVATE_PERSON>

The Rose Cut is one of the most recognisable and romantic antique diamond styles.

Unlike modern brilliant cuts, a traditional Rose Cut has a flat base and a domed crown covered in triangular or kite-shaped facets that rise towards a central point.

The number of facets varies. Traditional examples commonly have three, six, twelve or twenty-four facets, although more elaborate variations were also produced.

The Rose Cut does not have the deep pavilion of a modern brilliant diamond. Instead, its flat-backed construction creates a softer, more subtle appearance, with light moving across the surface rather than producing the intense flashes associated with modern brilliant cutting.

This construction can also make a Rose Cut appear larger across the finger than a modern diamond of comparable carat weight.

Rose Cuts became particularly popular during the Georgian and Victorian periods and were frequently incorporated into closed-back settings, often backed with silver or gold.

They were traditionally used in rings, earrings, brooches, pendants and elaborate floral jewellery designs.

There are several variations, including:

  • Dutch Rose Cut: Often featuring a higher, more rounded dome with a greater number of facets.
  • Antwerp Rose Cut: A traditional European variation with a flatter profile and triangular facets.
  • Briolette Rose Cut: An elongated, fully faceted drop-shaped form, particularly popular in pendant and earring designs.
  • Rose Brilliant: A more elaborate variation combining characteristics of rose and brilliant cutting.

The Rose Cut has experienced a significant revival in contemporary jewellery. Designers increasingly use it in modern bezel settings, asymmetrical designs and distinctive engagement rings.

Its appeal lies in its character rather than maximum sparkle. It offers softness, individuality and an unmistakable connection to jewellery history.

4. The Mazarin Cut – 17th Century

The Mazarin Cut is an early form of brilliant cutting, named after Cardinal Jules Mazarin, the French statesman and diamond collector.

It is generally associated with a cushion-shaped outline and an early arrangement of facets intended to improve the reflection of light.

The Mazarin Cut is an important milestone because it helped move diamond cutting away from simple geometric shapes towards the development of more sophisticated brilliant patterns.

5. The Peruzzi Cut – Late 17th Century

The Peruzzi Cut is traditionally attributed to Venetian cutter Vincenzo Peruzzi.

It developed the early brilliant-cut concept by introducing additional facets to the crown and pavilion.

The Peruzzi Cut is generally associated with a more developed cushion-shaped brilliant arrangement, often described as having 33 facets on the crown and 24 on the pavilion, excluding the culet.

Although these early brilliant cuts did not achieve the optical performance of modern diamonds, they represented a major advancement in the understanding of light reflection and diamond proportions.

6. The Old Mine Cut – 18th to 19th Century

The Old Mine Cut is one of the most desirable and recognisable antique diamond styles.

Popular during the Georgian and Victorian periods, it was generally cushion-shaped, with a relatively high crown, small table, rounded corners, deep pavilion and often a noticeably large culet.

Unlike modern brilliant diamonds, Old Mine Cuts were individually shaped by hand, with proportions that varied considerably from stone to stone.

Their facets were designed to perform under the candlelight and softer illumination of the period. The larger facets create distinctive flashes of light rather than the more uniform sparkle associated with modern cutting.

Many Old Mine Cuts have a slightly asymmetrical appearance, which is part of their charm.

These diamonds are particularly popular in antique engagement rings and heritage jewellery. Their individuality makes them attractive to collectors and buyers who appreciate traditional craftsmanship.

7. The Old European Cut – Late 19th to Early 20th Century

The Old European Cut represents another important development in diamond cutting and is the direct historical predecessor of the modern round brilliant.

It became particularly popular during the Victorian, Edwardian and early Art Deco periods.

Unlike the cushion-shaped Old Mine Cut, the Old European Cut has a more rounded outline. It generally features a small table, high crown, deep pavilion, relatively large culet and a symmetrical arrangement of facets.

Old European Cuts were designed to maximise the return of light using the cutting knowledge and technology available at the time.

As mechanical cutting methods improved, cutters were increasingly able to produce more consistent round shapes and symmetrical facet arrangements.

The Old European Cut remains highly sought after because of its distinctive appearance, historical significance and softer, more individual light performance.

8. The Cushion Cut – 19th Century and Earlier Origins

The Cushion Cut evolved from earlier antique diamond shapes, including the Old Mine Cut.

Its rounded corners and square or rectangular outline give it the appearance of a cushion.

Depending on the period and cutting style, cushion diamonds can have broad facets, smaller brilliant-style facets or a combination of both.

Modern cushion cuts continue to be popular, but antique cushion diamonds are particularly interesting because their proportions and facet arrangements often reveal the hand craftsmanship of their original cutters.

9. The Single Cut – 19th Century Onwards

The Single Cut is a relatively simple faceting style, generally consisting of 17 or 18 facets depending on the counting convention.

It has a small table, crown facets and a simple pavilion arrangement.

Single Cuts were widely used in smaller diamonds, particularly in pavé settings, watches and fine jewellery.

They were also commonly used in older jewellery where numerous small stones were required to complement a larger centre diamond.

Although less elaborate than a full brilliant cut, Single Cuts remain useful in contemporary jewellery manufacturing.

10. The French Cut – 17th Century Onwards

The French Cut is a distinctive square-shaped diamond cut with a geometric arrangement of triangular facets.

It is particularly associated with antique and Art Deco jewellery.

French Cuts were often used as side stones in rings and bracelets, where their straight edges and architectural appearance complemented the designs of the period.

Their popularity increased during the Art Deco movement, when geometric shapes, symmetry and strong architectural lines became central to jewellery design.

11. The Eight-Cut – 19th to 20th Century

The Eight-Cut is a simplified brilliant-style cut, generally featuring eight facets on the crown and eight on the pavilion, together with a table and culet.

It was particularly useful for small diamonds where a full brilliant arrangement was impractical or uneconomical.

Eight-Cuts were widely used in older jewellery, particularly in pavé and cluster settings.

They are still encountered in antique pieces and some modern jewellery manufacturing.

12. The Swiss Cut – 19th to 20th Century

The Swiss Cut is another simplified brilliant-style cut, generally incorporating a greater number of facets than an Eight-Cut.

It was commonly used for small diamonds and melee stones in jewellery settings.

These diamonds were designed to provide more sparkle than a basic single or eight-cut stone while remaining economical to manufacture.

13. The Transitional Cut – Early to Mid-20th Century

The Transitional Cut emerged as diamond-cutting technology advanced and the industry moved towards the modern round brilliant.

It combined features of the Old European Cut with improved symmetry, more refined proportions and a smaller culet.

These diamonds represent an important bridge between traditional hand-cut stones and modern precision cutting.

Many transitional diamonds have excellent visual character, combining the broad flashes of antique diamonds with increased brilliance.

14. The Modern Round Brilliant – 20th Century

The modern round brilliant cut represents the culmination of centuries of diamond-cutting development.

The work of Marcel Tolkowsky in 1919 helped establish a mathematical approach to diamond proportions and light performance.

Modern cutting technology, precision measuring equipment and advanced optical analysis have continued to refine the round brilliant.

The standard modern round brilliant typically has 57 facets, or 58 when a culet is present.

Its carefully calculated proportions, facet arrangement and symmetry are designed to maximise brilliance, fire and scintillation.

Although the modern brilliant is now the most familiar diamond shape, it is important to remember that it represents only one chapter in a much longer history of diamond craftsmanship.

Why Are Old-Cut Diamonds Becoming Popular Again?

There is a growing appreciation for jewellery that tells a story.

Modern consumers are increasingly interested in pieces that are individual, distinctive and connected to history. Antique diamonds offer exactly that.

Unlike many contemporary diamonds, which are cut to precise and consistent specifications, old cuts were often shaped individually by skilled craftsmen.

This means that two antique diamonds of similar size and cutting style may have noticeably different proportions, facet arrangements and optical characteristics.

There are several reasons for their renewed popularity.

Individuality: No two hand-cut antique diamonds are necessarily identical. Their subtle irregularities and distinctive proportions give them personality.

Historical significance: An antique diamond may have been cut more than a century ago, potentially passing through several generations of jewellery ownership.

Soft light performance: Rose Cuts, Old Mine Cuts and Old European Cuts produce a different visual effect from modern brilliant diamonds. Their broad facets and distinctive proportions create larger flashes and a softer appearance.

Larger face-up appearance: Some Rose Cuts and shallow antique diamonds can appear larger across the surface than a modern diamond of the same carat weight.

Sustainable jewellery: Reusing an existing antique diamond allows an old gemstone to be incorporated into a new design without requiring another diamond to be mined and manufactured.

Are Old-Cut Diamonds More Valuable Than Modern Diamonds?

The value of an antique diamond is not determined simply by its age.

A well-preserved Old Mine Cut or Old European Cut may attract considerable interest, particularly when it has attractive proportions, desirable colour and clarity, good condition and documented provenance.

However, not every old-cut diamond commands a premium.

Factors influencing value include:

  • Carat weight and face-up measurements.
  • Colour and clarity.
  • Overall proportions and symmetry.
  • Condition, including chips, abrasions and damaged facet junctions.
  • Originality and evidence of previous repolishing.
  • Rarity and desirability of the particular cutting style.
  • Historical provenance and supporting documentation.
  • Current demand among collectors and jewellery buyers.

It is also important to distinguish between an antique diamond and a modern diamond cut in an antique style. A newly manufactured Old Mine-style diamond may reproduce the appearance of an historic cut without having any genuine historical age.

Professional examination is essential when establishing what a diamond actually is.

The Importance of Professional Diamond Identification and Grading

One of the challenges with antique diamonds is that many were cut long before modern grading standards existed.

Old certificates, handwritten descriptions and jewellery valuations may not accurately describe the diamond according to today’s recognised grading terminology.

Furthermore, a diamond that has remained in its original setting for generations may have accumulated wear, damage or alterations that are difficult to identify without specialist examination.

At the Diamond Certification Laboratory of Australia (DCLA), diamond examination involves detailed assessment of the stone’s characteristics, including its weight, measurements, colour, clarity, proportions, polish, symmetry and identifying features.

The laboratory can also document the diamond’s cutting style and relevant characteristics, helping owners, collectors and the jewellery trade better understand the stone they possess.

A diamond grading report is not a monetary valuation. Rather, it provides an independent technical description that can assist with identification, insurance, resale and informed purchasing decisions.

Preserving the Past While Appreciating the Future

The history of diamond cutting is a history of human ingenuity.

From the simple Point Cut of medieval Europe to the elaborate Rose Cuts, Old Mine Cuts and Old European Cuts of later centuries, every development reflects the knowledge, craftsmanship and aesthetic preferences of its time.

The modern brilliant cut may offer extraordinary optical performance, but it does not make the earlier styles obsolete.

An antique diamond can possess something that cannot be reproduced simply by using modern cutting equipment: genuine age, historical character and a connection to the craftsmanship of another era.

Whether it is an inherited Victorian ring, an Edwardian engagement ring, an Art Deco jewel or a contemporary design incorporating a Rose Cut, these diamonds continue to demonstrate that beauty is not always about maximum sparkle.

Sometimes, it is about individuality, history and the story held within the stone.

At DCLA, we believe that understanding a diamond begins with understanding its characteristics, its craftsmanship and its history. Every diamond has a story, and the old cuts are among the most fascinating chapters in that story.

Tuesday, 3 November 2026

South African Diamond Miner Petra Diamonds Shares Suspended in London

 The company grew rapidly through the acquisition of established diamond mines, many of which had previously been owned by De Beers.

Petra Diamonds, one of the most recognised names in South Africa’s modern diamond mining industry, has had its shares suspended from trading on the London Stock Exchange following its failure to publish audited financial results by the regulatory deadline.

The suspension, which took effect at 7:30 am UK time on 2 November 2026, applies to Petra’s ordinary shares on the London Stock Exchange’s Official List and Main Market.

The development marks another difficult chapter for a company with a significant history in South Africa’s diamond industry, including ownership of the historic Cullinan mine, famous for producing some of the world’s largest and most valuable diamonds.

Importantly, the suspension is a regulatory measure relating to the delayed financial reporting. It does not mean Petra has been delisted, nor does it automatically stop its mining operations.
Petra Diamonds: From junior explorer to major international producer
Petra Diamonds was established in 1997 and initially listed on London’s Alternative Investment Market (AIM) with a market capitalisation of less than £10 million. Its original ambition was to become a significant independent producer of gem-quality diamonds.

The company grew rapidly through the acquisition of established diamond mines, many of which had previously been owned by De Beers.

A major turning point came in 2008 when Petra acquired an initial interest in the Cullinan Diamond Mine, near Pretoria, South Africa. It subsequently increased its ownership and invested heavily in modernising the operation.

In 2011, Petra acquired a majority interest in the Finsch mine, another historically important South African diamond operation. That same year, the company graduated from AIM to the Main Market of the London Stock Exchange.

Over the following years, Petra established itself as an important supplier of natural rough diamonds to the international jewellery industry. Its portfolio included several historic mining operations in South Africa and Tanzania.

Perhaps no asset in Petra’s portfolio carries greater historical significance than the Cullinan Diamond Mine.

Originally known as the Premier Mine, it was discovered in 1902. On 26 January 1905, the mine produced the extraordinary 3,106-carat Cullinan Diamond, the largest gem-quality rough diamond ever discovered.

The stone was subsequently presented to King Edward VII and cut into nine principal stones and numerous smaller diamonds. Two of the largest became the Great Star of Africa and the Second Star of Africa, now part of the British Crown Jewels.

The mine has continued to produce exceptional diamonds, including rare blue diamonds and high-quality Type IIa white diamonds. In 2021, Petra sold a remarkable 39.34-carat blue diamond recovered at Cullinan for approximately US$40.2 million, demonstrating the extraordinary value that can still emerge from South African diamond deposits.
Petra Diamonds+2

Why has Petra Diamonds run into difficulties?
Despite its impressive diamond heritage, Petra has faced mounting financial and operational challenges.

The company has been operating in an increasingly difficult diamond market, particularly as demand for smaller natural diamonds has weakened and competition from laboratory-grown diamonds has continued to affect parts of the jewellery market.

Its financial position has also been affected by operational difficulties at Finsch.

Petra entered a business-rescue process for the Finsch operation on 29 May 2026, with production suspended in June. This leaves Cullinan as the company’s only producing mine, according to the information in its latest operating update.

In July, Petra reported revenue of approximately US$206 million for the financial year ended 30 June 2026, broadly unchanged from the previous year.

However, its consolidated net debt increased to US$322 million, compared with US$298 million three months earlier. The company reported total cash of US$28 million, of which only US$9 million was unrestricted.

Petra also secured a short-term working-capital facility of approximately US$18 million and negotiated a deferral of around US$6 million in interest payments.

The company has subsequently undertaken workforce restructuring and launched a strategic review to investigate options for addressing its short-term cash requirements, potentially including asset disposals.
Audit delay triggers London Stock Exchange suspension
The immediate reason for the suspension is Petra’s failure to publish its audited annual report for the financial year ended 30 June 2026 by the 31 October deadline.

Petra had warned shareholders on 22 October that additional time was required to complete outstanding audit procedures, finalise consolidated financial statements and undertake the necessary group audit reviews.

On 2 November, the Financial Conduct Authority suspended the company’s listing, with trading on the London Stock Exchange’s Main Market also suspended.

Petra has stressed that the audit remains in progress and that it is working with its auditors to publish the accounts as soon as practicable.

The company has not announced a date for completion.

Importantly, the suspension is not a delisting and does not automatically affect the company’s mining operations. However, shareholders are unable to buy or sell their shares through normal London Stock Exchange trading while the suspension remains in place.

Petra has indicated that it will seek restoration of its listing once the audited accounts are published. This will require the necessary regulatory approval.
What does this mean for the diamond industry?
Petra Diamonds’ difficulties are significant because the company represents an important part of South Africa’s modern natural diamond mining industry.

For nearly three decades, Petra has built its business around some of the world’s most historically important diamond deposits. Its association with Cullinan, in particular, gives the company a unique position in the history of the natural diamond trade.

However, the current situation also highlights the pressures facing established diamond producers.

The industry is navigating changing consumer demand, competition from laboratory-grown diamonds, economic uncertainty and the substantial costs associated with operating deep underground mines.

For the natural diamond industry, the challenge is not simply finding diamonds. It is maintaining commercially viable mining operations, securing investment and ensuring that natural diamonds continue to command a premium based on their rarity, provenance and enduring appeal.

Petra’s future will depend on completing its audit, addressing its financial position and determining how best to secure the future of its remaining operations.

For the diamond industry, the story is far from over. The Cullinan mine has been producing remarkable diamonds for more than a century, and its geological resources remain significant. Whether Petra Diamonds can successfully navigate its current financial difficulties is now the question facing shareholders, employees and the wider diamond trade.

Source note: Historical background is drawn from Petra Diamonds’ published company history and Cullinan heritage information. The 2026 financial and suspension details above are based on the information supplied for this article.

Source: DCLA

Monday, 2 November 2026

The global jewellery industry is undergoing a significant structural change.

 Australia: An especially challenging environment for jewellery businesses

The global jewellery industry is undergoing a significant structural change. Independent jewellers, manufacturers, wholesalers and traditional retailers are facing mounting financial pressure, fewer new businesses are entering the market, and established operators are increasingly being forced to close, consolidate or rethink their business models.

For an industry built on generations of craftsmanship, family ownership, personal relationships and the enduring appeal of precious metals and gemstones, the warning signs are becoming difficult to ignore.

While the United States is reporting a continuing decline in the number of jewellery businesses, Australia faces its own challenges. High operating costs, elevated interest rates, pressure on household disposable incomes, rising wages, commercial rents and changing consumer behaviour are creating an increasingly difficult environment for Australian jewellery businesses.

There is also a bigger question: is the traditional jewellery retail model becoming unsustainable?

The answer may have significant implications for consumers, jewellers, manufacturers and anyone looking to buy, sell or inherit valuable jewellery.

The American jewellery industry: A warning sign for the rest of the world

The latest figures from the Jewelers Board of Trade (JBT), released in October 2026, provide a useful snapshot of the pressures facing the American jewellery trade.

At 30 September 2026, the United States had 21,831 listed jewellery retailers, wholesalers and manufacturers, representing a 1.4% decline compared with the previous year.

US jewellery industry – third quarter 2026

21,831

Active listed businesses

-1.4%

Annual decline

67

New businesses in Q3

15

Bankruptcies in first nine months

Source: Jewelers Board of Trade, September 2026 reporting.

The breakdown is particularly revealing:

Business categoryBusinesses remainingAnnual change
Retailers16,564-1.5%
Wholesalers3,206-0.9%
Manufacturers2,061-1.7%

The number of new businesses being established is equally concerning. Only 67 jewellery companies opened during the third quarter, compared with 89 during the same period last year.

For the first nine months of 2026, just 236 new businesses were established, a reduction of 14.8% from the previous year’s 277.

Meanwhile, 116 businesses exited the industry during the third quarter. Although this was an improvement on the 126 exits recorded a year earlier, bankruptcies over the first nine months more than doubled, increasing from seven to 15.

The message is clear: even in one of the world’s largest and most established jewellery markets, the traditional trade is under pressure.

And importantly, the problem is not confined to shopfronts. Retailers, wholesalers and manufacturers are all experiencing contraction.

This is a global structural change, not simply a difficult trading year

The challenges facing the jewellery industry are being driven by several forces occurring simultaneously.

1. The rising cost of doing business

Jewellery retailers traditionally operate with substantial overheads. Commercial rents, wages, insurance, security, electricity, inventory financing and compliance costs all contribute to the cost of maintaining a physical retail operation.

For independent jewellers, these expenses can become increasingly difficult to absorb when customer numbers and sales volumes weaken.

Unlike many other retail categories, jewellery businesses must also maintain significant amounts of valuable stock, often tying up substantial working capital in products that may take months or even years to sell.

2. The changing economics of gold and diamonds

The dramatic increase in precious metal prices has created another challenge.

When gold prices rise, the replacement cost of jewellery inventory rises with them. Retailers must either commit more capital to maintaining their stock levels or operate with smaller inventories.

Consumers, meanwhile, are confronted with higher prices for traditional gold jewellery.

This creates a difficult situation: the value of the underlying metal may increase, but the number of customers able or willing to purchase finished jewellery can decline.

3. Online competition and changing consumer behaviour

The traditional jewellery store is no longer the only place consumers can research, compare and purchase jewellery.

Online retailers, international marketplaces and direct-to-consumer brands have changed the competitive landscape.

Customers can compare prices internationally, investigate diamonds independently and purchase products without necessarily visiting a physical showroom.

This has put additional pressure on businesses that rely on high retail margins and expensive shopfronts.

4. Lab-grown diamonds have disrupted traditional diamond retailing

The rapid growth of laboratory-grown diamonds has fundamentally changed the diamond market.

Consumers can now purchase visually comparable laboratory-grown diamonds at a fraction of the price of natural diamonds.

While this has opened the market to a different category of customer, it has also created significant pricing pressure for retailers holding natural diamond inventory.

Natural diamonds and laboratory-grown diamonds are not the same product economically. Their supply characteristics, rarity, resale markets and long-term value propositions are different.

Retailers that fail to explain these differences risk competing purely on price.

5. Family businesses are struggling with succession

Another important factor is generational change.

Many jewellery businesses were established by families who built their reputations over decades. Their owners often possess exceptional technical knowledge, manufacturing experience and relationships that cannot easily be replaced.

However, the next generation does not always want to inherit the responsibility, financial commitment and operating demands of a traditional jewellery business.

As a result, some established businesses are being sold, consolidated or closed rather than passed on.

This is particularly significant because the disappearance of an experienced jeweller represents more than the loss of another retail outlet. It can mean the loss of valuable industry knowledge, craftsmanship and expertise.

Australia: An especially challenging environment for jewellery businesses

Australia deserves particular attention.

It is tempting to describe Australia as the worst-performing developed economy in the world for jewellery businesses. However, there is currently insufficient comparable international jewellery-industry data to establish that definitive ranking.

What can be established is that Australia is experiencing substantial pressure across its retail sector, with smaller discretionary retailers particularly exposed.

The economic environment is making it increasingly difficult for businesses to operate profitably.

According to KPMG’s September 2026 Retail Health Index, Australia’s retail sector deteriorated further during the June quarter, with its index falling to -1.07 from -0.39 in the previous quarter.

KPMG identified higher business costs, fragile consumer confidence, weaker profitability and elevated insolvencies as important factors. Its outlook suggests that challenging retail conditions could persist through to the end of 2027. KPMG Australia

Deloitte Access Economics has also warned that Australian retail spending is likely to weaken.

Its September 2026 forecasts anticipate real retail turnover growth slowing from 2.8% in 2025–26 to just 1.5% in 2026–27, as higher interest rates, weaker real wages and pressure on household finances affect discretionary purchases. Deloitte Australia+1

For jewellery businesses, this is particularly problematic.

Jewellery is generally a discretionary purchase. Engagement rings, anniversary gifts, luxury watches, diamond earrings and substantial gold jewellery purchases can be postponed when households are worried about mortgages, living expenses and financial security.

The Australian business environment also has some significant structural disadvantages:

  • High labour costs: Australian wage and employment expenses place considerable pressure on smaller retailers.
  • Commercial property costs: Maintaining a premium retail location can consume a substantial proportion of revenue.
  • Compliance and operating expenses: Insurance, security, administration and regulatory obligations add to the cost of doing business.
  • Household financial pressure: Mortgage commitments and the cost of living compete directly with discretionary spending.
  • International competition: Australian businesses must compete with global online retailers that may have different cost structures and access to larger markets.

The broader business figures reinforce the concern.

Australian industry data published in August 2026 showed 14,500 business insolvencies over the financial year to June, approximately 70% above pre-pandemic levels. Retail and accommodation businesses were among those affected by weaker consumer spending. August 2026

Furthermore, Australian small retail businesses declined by more than 10,000, or 9%, between 2020–21 and 2024–25. New business entries also fell during that period. Service and Creative Skills Australia (SaCSA)

These are not jewellery-specific figures, but they demonstrate the difficult environment in which Australian jewellers are operating.

Why traditional jewellery retailers are particularly vulnerable

One of the biggest problems facing traditional jewellery retailers is the way their businesses are structured.

A conventional jewellery store may have:

  • A substantial investment in finished jewellery inventory.
  • Expensive premises in shopping centres or premium retail locations.
  • Several employees, including salespeople and specialist staff.
  • Security systems, insurance and other fixed operating costs.
  • A reliance on customers purchasing new jewellery at retail prices.

When sales slow, most of these expenses remain unchanged.

A business can therefore experience a significant decline in profitability even when the value of its stock is increasing.

There is also a fundamental difference between selling jewellery and buying precious metals or second-hand jewellery.

A traditional retailer needs to sell new products, often with significant manufacturing, distribution and retail costs built into the final price.

A specialist precious metals and jewellery buyer, on the other hand, operates in a different part of the market. It can provide services to people who are looking to sell, liquidate, value or redistribute existing assets.

This distinction is becoming increasingly important.

The Australian jewellery industry needs to adapt

The future of the jewellery industry will not necessarily belong to the businesses with the biggest shopfronts or the most expensive advertising campaigns.

It is likely to favour businesses with genuine expertise, lower operating overheads, established reputations and the ability to provide services beyond simply selling new jewellery.

Consumers are becoming more informed. They want to understand what their jewellery is worth, how diamonds are graded, what their gold contains and what they can realistically expect to receive when selling.

They also want confidence that the person assessing their valuables has the technical knowledge and experience to provide an honest opinion.

This is where specialist knowledge becomes a competitive advantage.

GoldCompany and DCLA: A different approach to the jewellery industry

While much of the traditional jewellery trade remains focused on selling new products, the GoldCompany Group has developed a broader business model built around buying, selling, assessing and understanding precious metals, diamonds and jewellery.

Established in Australia in 2008, the GoldCompany Group brings together specialist expertise across gold, diamonds, jewellery and precious metals.

Its businesses include GoldCompany and the Diamond Certification Laboratory of Australia (DCLA).

This combination provides an important advantage in an industry where independent technical knowledge is becoming increasingly valuable.

GoldCompany – expertise in buying and valuing precious metals and jewellery

GoldCompany specialises in purchasing gold, silver, platinum, coins, diamonds, watches and estate jewellery.

For customers looking to sell inherited jewellery, divide an estate or understand the value of their possessions, the ability to deal with experienced specialists is particularly important.

Rather than relying on a simple weight-based assessment, customers can benefit from an understanding of the individual components of their jewellery, including precious metals, gemstones, diamonds and potentially valuable individual pieces.

DCLA – independent diamond expertise

The Diamond Certification Laboratory of Australia provides specialist diamond identification, grading and certification services.

Its technical capabilities include assessing natural and laboratory-grown diamonds, identifying treatments and examining diamond characteristics.

The laboratory provides an additional level of expertise when customers need to understand what they own, particularly when dealing with valuable estate jewellery, inherited diamonds or significant individual gemstones.

Three generations of knowledge and experience

The GoldCompany Group’s foundations are built on generations of experience in diamonds, gold, manufacturing and precious metals.

That background matters.

Understanding a diamond requires more than looking at its size. Understanding gold jewellery requires more than weighing it. And understanding the potential value of an estate requires knowledge of the different markets in which its individual items can be sold.

This is the type of expertise that becomes increasingly important as consumers become more cautious and demand greater transparency.

The opportunity: The industry may be shrinking, but the need for expertise is growing

There is an important distinction between the number of jewellery businesses operating and the underlying demand for jewellery expertise.

People will continue to inherit jewellery. Families will continue to divide estates. Couples will continue to purchase engagement rings. Owners will continue to sell unwanted gold, diamonds and watches.

What may change is where they choose to go for assistance.

The traditional model of visiting a retail jeweller to purchase a new item is only one part of the market.

There is an expanding need for:

  • Independent diamond identification and grading.
  • Professional valuations and assessments.
  • Estate jewellery evaluations and liquidation.
  • Gold and precious metals purchasing.
  • Assistance with inheritance and family divisions.
  • Advice on the differences between natural and laboratory-grown diamonds.
  • Specialist knowledge when selling significant jewellery and gemstones.

Businesses that can provide these services under one roof are particularly well positioned to serve changing consumer requirements.

What does this mean for consumers?

For anyone purchasing or selling jewellery, the changing industry makes it more important than ever to understand who they are dealing with.

When selling valuable jewellery, do not assume that the first offer you receive represents its true market value.

A diamond may have a value beyond its metal setting. An antique ring may have historical or collectible significance. A substantial gold piece may contain gemstones that should be assessed separately.

Similarly, when purchasing a diamond, consumers should understand the distinction between natural and laboratory-grown stones and the very different markets in which they trade.

Independent technical assessment, transparency and experience should be important considerations.

The future belongs to businesses built on knowledge, trust and experience

The decline in the number of American jewellery businesses is another indication that the traditional jewellery trade is undergoing a major transformation.

Australia is experiencing many of the same structural pressures, compounded by an expensive operating environment and increasingly cautious consumers.

It would be premature to declare Australia the worst-performing developed country for jewellery businesses without comparable international figures. However, the available Australian retail and insolvency data clearly demonstrate the severity of the challenges.

The industry is not necessarily disappearing. It is changing.

Businesses that rely entirely on expensive premises, high inventory commitments and traditional retail margins may find the coming years increasingly difficult.

Those that combine technical expertise, established relationships, transparent pricing and a broader range of services may be better positioned to adapt.

At DCLA, our philosophy has always been that knowledge and experience matter.

With three generations of industry knowledge, specialist diamond laboratory expertise and a business built around buying, assessing and understanding precious metals and jewellery, we believe that the future belongs to businesses that offer more than simply a product for sale.

In an industry where trust is becoming increasingly important, experience is not just an advantage. It is the foundation of a sustainable business.

A Complete Guide to Antique Diamond Cuts: History, Styles and the Beauty of Old-Cut Diamonds

  For centuries, diamonds have captivated people not only because of their rarity and beauty, but also because of the extraordinary skill re...