Showing posts with label Canada. Show all posts

Monday, 14 September 2026

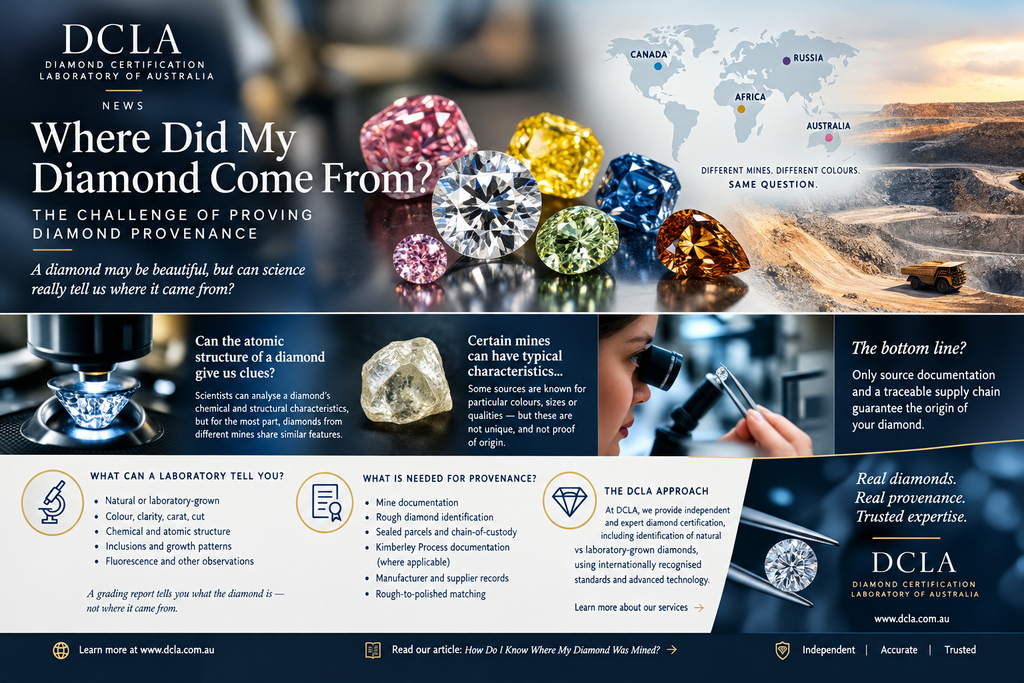
Where Did My Diamond Come From?

 How can you prove the provenance of a polished diamond?

How can you prove the provenance of a polished diamond?

When buying a natural diamond, one question is becoming increasingly important:

Where did it come from?

A diamond may have been mined in Botswana, South Africa, Canada, Australia, Angola, Namibia, Lesotho, Russia or one of the many other diamond-producing regions around the world. But once that rough diamond has been cut and polished, can a laboratory actually look at the finished stone and determine which mine it came from?

For the vast majority of polished diamonds, the answer is no.

This is an important distinction between identifying what a diamond is and identifying where it came from.

A gemmological laboratory can examine a polished diamond and determine many things about it, including its natural or laboratory-grown origin, colour, clarity, carat weight and other characteristics. But determining the geographic origin of a natural diamond is a very different scientific problem.

DCLA has previously addressed the difficulty of determining where a diamond was mined and the importance of documentation and traceability. DCLA: How Do I Know Where My Diamond Was Mined?

Can the atomic structure of a diamond reveal its mine?

This is where the science becomes particularly interesting.

A diamond is made primarily from carbon atoms arranged in a highly organised crystal structure. Small amounts of nitrogen, boron and other trace elements can also occur within the crystal.

Scientists can examine characteristics such as:

  • Crystal structure
  • Nitrogen characteristics
  • Trace elements
  • Isotopic composition
  • Inclusions
  • Growth patterns
  • Spectroscopic characteristics
  • Fluorescence and luminescence

These characteristics can sometimes provide clues.

The problem is that diamonds from different mines can share remarkably similar geological and chemical characteristics.

Research published by the Gemological Institute of America has found that diamond characteristics overlap extensively between deposits around the world. There is currently no scientifically robust method that can independently determine the geographic origin of a random individual polished diamond simply by analysing the stone.

In other words, the atomic structure can tell scientists a great deal about a diamond but for most polished diamonds, it cannot provide a unique geographic fingerprint saying, for example, “this diamond came from Mine X.”

Diamonds from particular mines can have characteristics but that is not proof

This does not mean that diamonds from particular mines are completely indistinguishable.

Certain mines and deposits can become associated with particular characteristics.

For example, some sources have become famous for producing particular sizes, qualities or colours of diamonds. The Argyle mine in Australia became particularly associated with pink and other rare coloured diamonds, while the Cullinan mine in South Africa became famous for producing exceptionally large, high-quality diamonds.

However, these associations are not the same thing as scientific proof of origin.

A diamond may display characteristics that are more common in diamonds from a particular locality without those characteristics being exclusive to that locality.

As GIA research explains, experienced professionals may sometimes make an educated assessment of the likely origin of certain rough diamonds or parcels. But for the majority of polished diamonds, there are no distinctive characteristics that independently reveal their geographic origin.

This distinction is particularly important when a diamond is being marketed with a premium based on its supposed geographical origin.

“This diamond looks like it could have come from that mine” is not the same as “this diamond has been proven to have come from that mine.”

What happens when the diamond is polished?

The journey from rough to polished is critical.

A rough diamond can contain information that is lost or altered when it is cut and polished. Surface characteristics disappear, inclusions may be removed or avoided during cutting, and the original crystal shape is transformed into a finished gemstone.

This makes retrospective identification extremely difficult.

GIA’s research describes the problem clearly: the characteristics of diamonds from different geological environments overlap, while gem-quality diamonds contain extremely low concentrations of many trace elements. The research concludes that, at present, reliable diamond provenance depends on retaining origin information from the time of mining rather than attempting to determine the origin analytically after the fact.

So how can the origin of a polished diamond actually be proven?

The answer is traceability.

Instead of trying to work backwards from the finished diamond, the origin needs to be established at the beginning of the diamond’s journey.

One of the strongest scientific approaches is to analyse the rough diamond when its origin is documented, record its characteristics, and then match the resulting polished diamond back to that original rough.

This is the principle behind the GIA Diamond Origin Report.

GIA requires the rough diamond to be received in a documented, sealed and tamper-resistant parcel directly from the mining company. The rough is analysed and assigned an identification number. After cutting and polishing, the finished diamond can then be submitted and scientifically matched against the original rough.

The matching process can use a combination of physical measurements, spectroscopy, imaging and other characteristics recorded from the rough.

This is fundamentally different from taking an unknown polished diamond and attempting to guess its mine of origin.

What about the Kimberley Process?

The Kimberley Process is also an important part of the broader diamond supply chain.

It was established to prevent the international trade in conflict diamonds and provides a system of controls surrounding the international trade in rough diamonds.

DCLA’s own terms and conditions require diamonds listed through its website to have been imported under the Kimberley Process.

However, it is important to understand what this means.

A Kimberley Process certificate and supply-chain documentation can provide important evidence concerning the legal movement and declared origin of rough diamonds, but it is not the same as a gemmological laboratory looking at an unknown polished diamond and scientifically determining its mine.

What does a normal diamond certificate prove?

A diamond grading report is extremely useful, but consumers should understand what it does and does not establish.

A conventional grading report can document characteristics such as the diamond’s:

Carat weight
Colour
Clarity
Cut
Measurements
Proportions
Fluorescence and other laboratory observations

It may also identify whether a diamond is natural or laboratory-grown, depending on the laboratory and examination performed.

But a standard grading report does not automatically establish the mine where a natural diamond was extracted.

DCLA has also warned consumers about another important issue: a legitimate grading certificate can sometimes be presented with a different stone. The laboratory’s recent consumer alert highlights why matching the physical diamond to its report and verifying inscriptions and characteristics is so important.

You can read more about DCLA’s approach to diamond identification and certification through the DCLA Diamond Certification Laboratory.

What about coloured diamonds?

The situation becomes particularly interesting with natural coloured diamonds.

Certain geographic sources have become strongly associated with particular colours and colour ranges.

Australia’s Argyle mine, for example, became internationally famous for its pink diamonds. Other deposits have produced distinctive populations of yellow, blue, brown and other coloured diamonds.

Colour, hue and saturation can therefore sometimes provide useful clues about a possible source.

But again, a clue is not proof.

A particular colour may be much more frequently encountered from one locality than another, while similar colours can occur elsewhere.

The same principle applies to other characteristics such as inclusions, growth features and trace chemistry.

A laboratory may be able to say that a stone displays characteristics that are consistent with diamonds seen from a particular source. That does not necessarily mean the laboratory can prove that the individual diamond came from that mine.

The difference between identification and provenance

This is perhaps the most important distinction for consumers.

Identification asks:

What is this diamond?

Provenance asks:

Where did this particular diamond come from and can its journey be documented?

A laboratory can provide powerful scientific evidence about the first question.

The second question requires something more: a chain of evidence connecting the individual diamond to its source.

That evidence can include:

  • Mine documentation
  • Rough diamond identification
  • Sealed parcels
  • Export documentation
  • Kimberley Process documentation where applicable
  • Manufacturer records
  • Rough-to-polished matching
  • Laser inscriptions
  • Grading reports
  • Purchase invoices
  • Supplier records
  • Chain-of-custody documentation
  • Verified digital traceability systems

Documentation is the key to provenance

The simplest way to think about diamond provenance is this:

You cannot reliably create provenance after the diamond has lost its documented history.

If a diamond is mined, mixed with thousands of other diamonds, sold through several companies, cut and polished, and eventually appears years later without its original documentation, scientific examination may be unable to reconstruct its exact mine of origin.

By contrast, if the diamond’s identity is established at the mine and maintained throughout the manufacturing process, its journey can potentially be verified.

This is why modern diamond traceability systems are becoming increasingly important.

GIA itself has stated that there is currently no scientific method capable of determining country of origin simply by examining a random natural diamond. Its origin services instead rely on verified origin information and scientific matching between the rough and polished diamond.

The DCLA view

At DCLA, we believe consumers should be given a clear distinction between what can be scientifically established and what may simply be an educated opinion.

Diamonds from certain mines can share characteristics. Certain colours, qualities, inclusions and growth features may occur more frequently in particular deposits.

But the majority of gem-quality white diamonds, once polished, do not carry a unique scientific fingerprint that allows their mine of origin to be established with certainty.

And while some coloured diamonds may display characteristics strongly associated with particular sources, those characteristics are not automatically proof of origin.

The bottom line is simple:

If you want to know where your diamond came from, look at the chain of evidence not just the appearance of the stone.

A diamond grading report can tell you what the diamond is.

Scientific examination can identify many of its characteristics.

But provenance comes from being able to connect that individual diamond to its documented source.

For a diamond whose geographic origin is important to the buyer, the strongest evidence is documentation and traceability maintained from the rough diamond through cutting, polishing and sale.

In the world of diamond provenance, a good story is not the same as proof.

The most valuable provenance is the provenance that can be documented, verified and traced back to the source.

For further information on diamond identification, certification and laboratory-grown diamond detection, visit DCLA – Diamond Certification Laboratory of Australia and explore DCLA’s educational resources, including DCLA’s article on diamond mine origin and DCLA’s information on natural and laboratory-grown diamonds.

Independent research

For further scientific reading, GIA’s research on the geographic origin of diamonds explains the limitations of current analytical methods and why documented origin information remains essential. GIA: Methods and Challenges of Establishing the Geographic Origin of Diamonds

GIA also explains its rough-to-polished scientific matching process through its Diamond Origin Report service.

Wednesday, 27 May 2026

India’s Lab Grown Diamond Exports Surpass Natural Diamonds for the First Time

 India’s polished lab grown diamond exports have overtaken natural diamond exports by volume for the first time

India’s polished lab grown diamond exports have overtaken natural diamond exports by volume for the first time, marking a significant shift in the global diamond manufacturing industry.

According to figures released by the Gem and Jewellery Export Promotion Council (GJEPC), exports of polished lab grown diamonds reached 18.84 million carats during the financial year ending March 2026, an increase of almost 31 per cent year on year.

By comparison, polished natural diamond exports fell nearly 4 per cent to 16.00 million carats.

Despite the dramatic rise in lab grown volumes, natural diamonds continue to generate the overwhelming majority of industry revenue due to the substantial price difference between the two categories. Average export values for natural diamonds remain around US$760 per carat, compared to approximately US$60 per carat for lab grown goods.

As a result, natural diamond exports generated approximately US$12.16 billion during the year, while lab grown exports totalled around US$95.52 million.

The figures nevertheless highlight the rapid transformation of India’s diamond manufacturing sector. Just a decade ago, in 2015 to 2016, India exported only around 10,000 carats of polished lab grown diamonds.

Recent monthly data suggests the trend is continuing. During April 2026, India exported 1.36 million carats of polished lab grown diamonds, marginally exceeding natural diamond exports of 1.34 million carats.

The continued growth of lab grown production is reshaping the global diamond trade and placing increasing pressure on the natural diamond pipeline, particularly in the lower price categories.

The Future of Canada’s Ice Road Under Threat

The 370 mile ice road, commonly known as the TCWR, stretches across frozen lakes and remote terrain in the Northwest Territories near the Arctic Circle.

The long term future of Canada’s famous Tibbitt to Contwoyto Winter Road, the critical supply route servicing diamond mines in the country’s far north, is increasingly uncertain amid mine closures, financial instability and warmer winters.

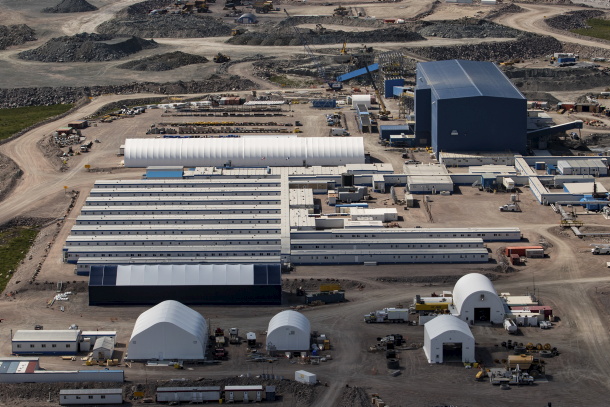
The 370 mile ice road, commonly known as the TCWR, stretches across frozen lakes and remote terrain in the Northwest Territories near the Arctic Circle. For decades it has provided an essential seasonal transport link to the region’s major diamond operations, including Diavik, Ekati and Gahcho Kué.

However, the future viability of the route is now being questioned.

Rio Tinto officially closed the Diavik Diamond Mine in March 2026, while Ekati Diamond Mine entered creditor protection proceedings in April. Meanwhile, De Beers operated Gahcho Kué Mine continues to face significant financial pressure.

The winter road plays a vital logistical role each year, allowing operators to transport fuel, cement, heavy mining equipment, tyres and explosives during a narrow eight to ten week operating window when the lakes remain frozen.

Construction and maintenance of the road reportedly costs around US$20 million annually.

Following the closure of Diavik, De Beers has assumed oversight responsibilities for future operations of the road and has confirmed planning is underway for the 2027 season.

However, uncertainty remains over how long the route can continue operating, particularly as increasingly mild winter conditions shorten the period of safe ice access.

Local media reports have raised concerns over whether sufficient funding and operational support will remain available in coming years, fuelling speculation that the famous ice road may be approaching the end of its operational life.

Source: DCLA

Friday, 27 March 2026

Rio Tinto’s Final Diamond: The Closure of Diavik Marks the End of an Era

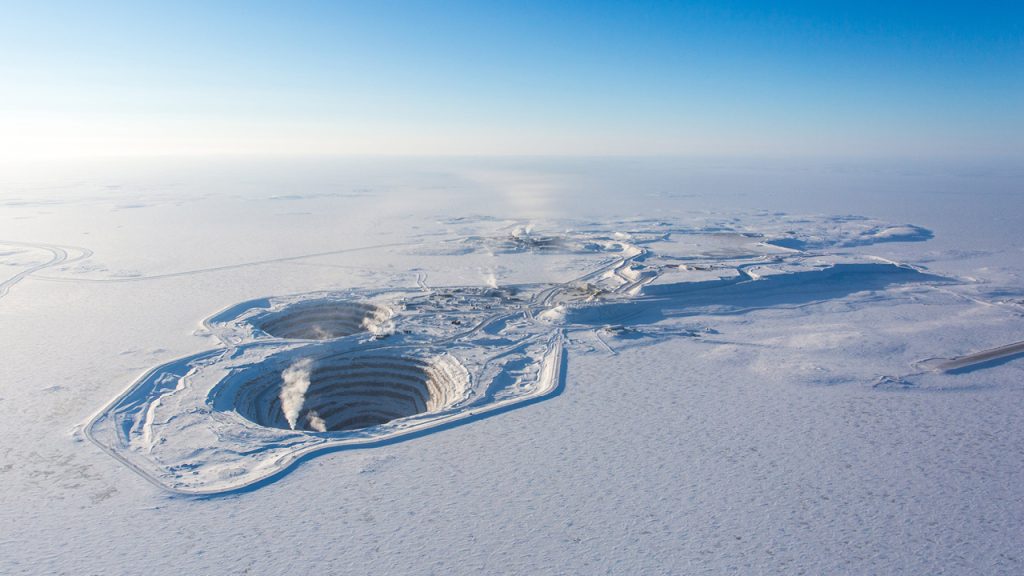
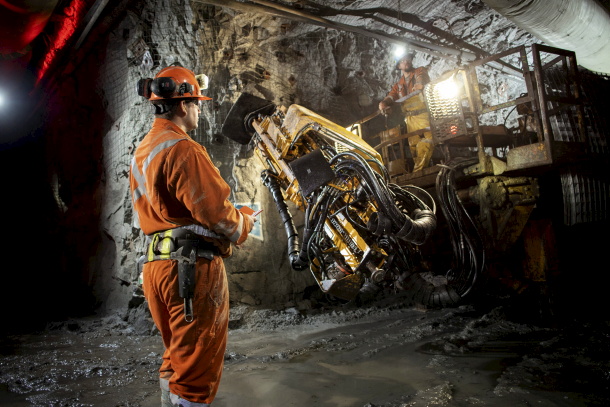
 Diavik mine in Canada’s Northwest Territories

Rio Tinto has officially extracted the last diamond from its Diavik mine in Canada’s Northwest Territories, bringing to a close more than two decades of production and signalling the company’s exit from the diamond sector. The milestone reflects a strategic shift by the global mining giant toward core commodities such as copper and iron ore.

Over its 23 year lifespan, Diavik produced in excess of 150 million carats of rough diamonds, establishing itself as one of Canada’s most significant diamond operations. With economically recoverable reserves now fully depleted, the mine has ceased production, concluding a chapter that began in 2003.

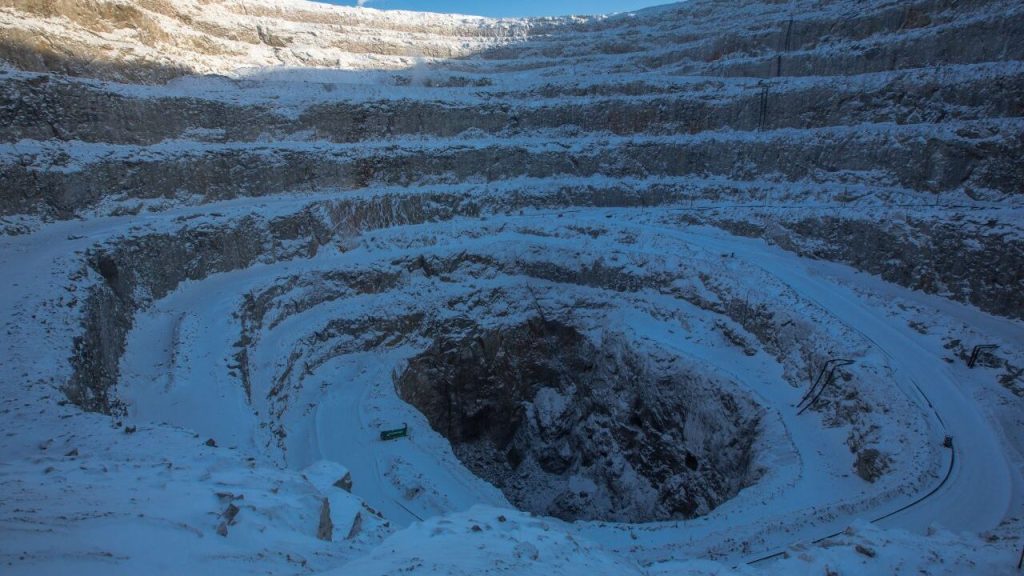
Situated beneath Lac de Gras, approximately 220 kilometres south of the Arctic Circle, Diavik was discovered in 1991 and developed into a world-class operation. The mine exploited four kimberlite pipes through a combination of open pit and underground mining methods, yielding predominantly high-quality white diamonds alongside a smaller proportion of rare yellow stones.

The closure was marked by a formal ceremony attended by Indigenous representatives, government officials, and key stakeholders, highlighting the longstanding partnerships that underpinned the mine’s success. Diavik has been widely recognised as a model of collaboration between industry and Indigenous communities, delivering sustained economic and social benefits to the region.

Despite the end of mining activities, Rio Tinto will continue to process, polish, and distribute the remaining production through its global sales network, including its Select Diamantaires, into 2026 and beyond.

The closure comes at a challenging time for the Northwest Territories’ diamond sector. Operations at the Ekati mine were curtailed last year amid increased competition from lab grown diamonds and softer global pricing, while the Gahcho Kué mine remains in operation with a projected life extending to 2030.

Planning for Diavik’s closure had been integrated from the outset, and rehabilitation efforts will now accelerate. Site reclamation is expected to continue through to 2029, followed by a structured period of environmental monitoring to ensure long term sustainability and land restoration.

The end of Diavik is more than the closure of a mine. It represents the conclusion of one of Canada’s most important diamond producing assets and a notable moment in the evolution of the global diamond industry.

Source: DCLA

Friday, 13 March 2026

Mountain Province Sales Slump in "Very Difficult" Conditions

 The Toronto-based miner said revenue for the full year was down from USD 195.2m to USD 111.5m

Mountain Province Diamonds has reported a 42% drop in sales for FY2025, as “very difficult” market conditions persist.

The Toronto-based miner said revenue for the full year was down from USD 195.2m to USD 111.5m, although there was an improvement in Q4, with the drop in sales down by a relatively modest 11% to USD 33m.

In a quarterly update published on 9 March it blamed continued pressure on rough diamond pricing due to uncertainty surrounding U.S. tariffs, geopolitical factors, and the ongoing threat from lab grown diamonds.

The average price per carat fell 18% from USD 72 to USD 59 in FY2025, and 24% for Q4 2025. The company blamed challenging market conditions and the mix of goods sold for the Q4 average price, reflecting the sale of a finer set of goods held back from previous quarters.

Production guidance for 2026 is 6.6m to 7.2m carats, compared to 4.33m carats recovered in FY2025.

Mountain Province operates the Gahcho Kue mine, in Canada’s Northwest Territories in a joint venture with De Beers.

Last month it said it was pausing plans for the Tuzo Phase 3 project, which would extend the life of the mine, but require substantial capital expenditure.

“While the Tuzo Phase 3 project has demonstrated strong potential, current market conditions have prompted the partners to take a measured approach to its development,” the company said.

Source: DCLA

Wednesday, 26 November 2025

Canada’s $92,000 Yellow Diamond Coins

Canada's $92,000 Yellow Diamond Coins

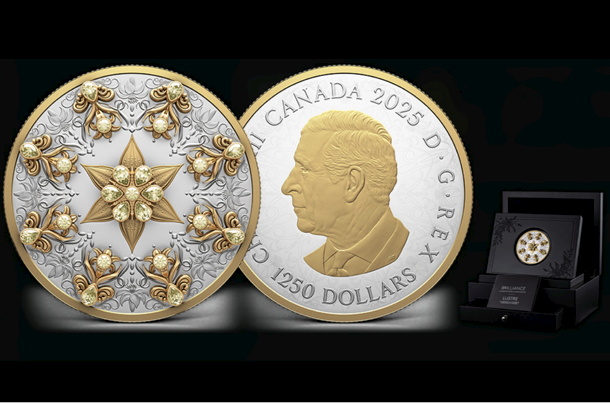
The Royal Canadian Mint has created a limited edition of 10 platinum coins, each set with at least 6.13 carats of fancy yellow diamonds from the Ekati mine, and priced at CAD 128,000 (USD 91,900).

The coins are legal tender, with a nominal value of CAD 1,250 (USD 900), crafted from 10oz of platinum with a Canada lily motif, highlighted with selective gold plating.

Each one is set with 14 pear-cut and nine round-cut fancy yellow diamonds. Seven of the diamonds form the center of the largest lily.

The 10oz coins, known as Brilliance, are a collaboration between Burgundy, the Calgary-based miner that owns and operates the Ekati mine in Northwest Territories, and the Royal Canadian Mint, the crown corporation that mints Canada’s coins.

The mint’s Opulence Collection also includes 30 gold coins, known as Radiance.

They weigh 1oz, feature approximately 1.14 carats of fancy yellow Ekati diamonds, plus white diamonds, and are priced at CAD 39,000 (USD 27,500).

“The Opulence Collection is a testament to the Royal Canadian Mint’s dedication to innovation and coin manufacturing excellence, and the addition of rare fancy yellow diamonds creates visually stunning collector pieces that also celebrate Canada’s vast mineral wealth,” said Marie Lemay, president and CEO of the Royal Canadian Mint.

Source: DCLA

Tuesday, 25 November 2025

Conflict Diamonds: Nations that Vetoed New Definition

A proposal to broaden the term at the KP plenary in Dubai last week was rejected by Australia, Canada, the EU (representing 27 member countries), Switzerland, Ukraine and the UK, according to the African Diamond Producers Association (ADPA). That's a total of 32 countries.

The Kimberley Process (KP) has again failed to reach agreement on a new definition of conflict diamonds.

A proposal to broaden the term at the KP plenary in Dubai last week was rejected by Australia, Canada, the EU (representing 27 member countries), Switzerland, Ukraine and the UK, according to the African Diamond Producers Association (ADPA). That’s a total of 32 countries.

Updating the current definition – diamonds used by rebel groups to finance armed conflict against legitimate governments – would have required a unanimous vote. There have been repeated attempts to broaden the definition since it was first adopted in 2000.

The World Diamond Council (WDC) spoke of its “profound regret” that a small number of participants had blocked consensus on long-awaited reforms designed to strengthen protections for Africa’s diamond-mining communities.

In a statement issued at the end of the plenary it did not identify those who had vetoed the new definition. But ADPA did.

ADPA said: “Six participants – Australia, Canada, the European Union, Switzerland, Ukraine, the United Kingdom and one observer, Civil Society Coalition, refused to support the expanded definition.”

It said its proposed definition “aimed to provide a Pan-African solution to today’s evolving nature of diamond conflicts and the realities on the ground”.

The ADPA’s broader definition would have included “armed groups, non-state armed groups, UN Security Council-sanctioned individuals and entities and their allies, as well as to cover actions aimed at financing armed conflict and other operations, including attempts at undermining legitimate governments, and the well-being of diamond communities”.

It singled out the EU for harsh criticism, claiming it had in recent years “purposefully blurred and made several attempts to bypass the work of the KP.

The World Diamond Council (WDC) said progress had been killed in pursuit of the impossible.

“Today’s outcome is not a failure of the KP,” said WDC president Feriel Zerouki (pictured), as the five-day plenary concluded.

“Most participants stood firmly behind Africa. The setback came from a few, not from the Process itself. And while they halted progress today, they cannot halt the direction of travel.”

Jaff Bamenjo coordinator of the KP Civil Society Coalition, an observer group that represents communities affected by diamond mining and trade, said KP remains detached from reality at a time when challenges are overwhelming and the KP refuses to take responsibility.

“Its scope remains a needle in a haystack,” he said. “Communities affected by diamond mining are left wondering how this scheme can possibly be relevant to the many problems they face.”

Source: IDEX

The Kimberley Process: Control of the Diamond Pipeline, Not the Use of Revenue

When the Kimberley Process Certification Scheme (KPCS) was launched in 2003, it was marketed as a global solution to stop “conflict diamonds” from funding civil wars and human rights abuses. However, more than two decades later, the realities of the initiative paint a very different picture. The Kimberley Process has evolved not into a tool of humanitarian oversight, but into a mechanism that controls the flow of rough diamonds—who mines them, who sells them, who profits—and with little concern for how those profits are ultimately used.

A System Focused on Legitimising Trade, Not Regulating Impact

The entire structure of the Kimberley Process revolves around documentation and export control. Diamonds are certified to ensure that they originate from “legitimate” channels, which mostly means from governments and recognised mining concessions. Once that documentation exists, the diamonds are cleared for international trade.

What the system does not do is monitor or regulate what happens next.

Once revenue enters official state budgets or company accounts, the Kimberley Process has no authority, no mandate, and no interest in determining whether diamond income:

  • Improves living standards in mining communities
  • Funds infrastructure, healthcare, or education
  • Supports social development
  • Or, conversely, fuels corruption, political patronage, or state violence

In many diamond-producing nations, government control of the resource is absolute, while accountability for the use of diamond wealth remains minimal.

Legitimacy Through the Stamp, Not Through the Outcome

A diamond certified under the Kimberley Process is considered “clean” simply because it does not fund a rebel movement. Yet the humanitarian reality is far more complex. In several countries, diamond mining takes place alongside:

  • Widespread corruption
  • Poverty in mining regions
  • Environmental degradation
  • Labour exploitation
  • Lack of reinvestment into the communities that generate the wealth

The certification system provides political legitimacy to the diamond trade while ignoring the social conditions behind it. In other words, the Kimberley Process ensures diamonds are “legitimate to sell,” not that the proceeds are “responsibly used.”

Who Really Controls the Diamond Narrative?

From the beginning, the Kimberley Process was structured by governments and major industry stakeholders, including those with the most to gain from a controlled and regulated supply chain. Control over certification effectively means control over access to export markets—an immense economic advantage.

This has allowed:

  • States to assert exclusive ownership over the resource
  • Major mining companies to maintain their dominant global trading roles
  • Smaller or informal miners to be excluded from legal markets
  • The narrative of “ethical diamonds” to remain tightly managed

In this sense, the Kimberley Process serves more as a trade gatekeeper than a humanitarian framework. It decides who may sell diamonds, where they may be shipped, and under what conditions—while staying silent on whether diamond-rich nations or their citizens truly benefit from the wealth beneath their soil.

A System Out of Step with Modern Expectations

In 2025, consumer expectations have changed dramatically. Jewellery buyers increasingly want:

  • Transparency
  • Ethical assurance
  • Positive social and environmental impact
  • Evidence of fair value distribution

Yet the Kimberley Process remains rooted in a narrow 20-year-old definition of conflict that does not consider:

  • Government-sponsored abuse
  • Corruption
  • Human rights violations
  • Economic exploitation
  • Lack of benefit to local communities

For modern ethical standards, this is an outdated and insufficient framework.

Conclusion

The uncomfortable truth is this: the Kimberley Process is primarily a system for controlling the supply and movement of diamonds, not for ensuring that the immense wealth generated improves lives or supports sustainable development.

It decides who is allowed to trade diamonds, not how diamond money is used. Until the initiative expands beyond its limited mandate and confronts the broader social realities of the diamond industry, the Kimberley Process will remain a trade tool—not a humanitarian safeguard.

Source: DCLA

Thursday, 28 August 2025

Michael Hill Revenue Flat in Challenging Market

Michael Hill

Australia-based jewelry retailer Michael Hill International says revenue for FY 2025 – the year to 29 June 2025 – was broadly flat compared with the previous year, down 0.2 per cent to AUD 643.7m (USD 431.3m).

Trading conditions remained challenging, it said, with the addition of volatile gold and diamond prices and US tariffs.

However group sales for the first seven weeks of FY 2026 were up 3.0 per cent year-on-year, and same store sales were up 3.2 per cent.

The company has 287 stores (down from 300 last year) in Australia, New Zealand and Canada, including low-price retailer Bevilles, Medley, and its new luxury business TenSevenSeven.

“Global economic uncertainty and challenging retail trading conditions persisted across all markets, with full year sales, gross margin and earnings broadly in line with prior year,” the company said in its Full Year Results, published yesterday (25 August).

Michael Hill chair Rob Fyfe paid tribute to CEO Daniel Bracken, aged 57, who died suddenly in February, and to founder Sir Michael Hill who died of cancer, aged 86, in July.

Source: DCLA

Friday, 18 July 2025

Hundreds of Layoffs at Loss-Making Ekati

Hundreds of Layoffs at Loss-Making Ekati

Hundreds of workers have been laid off at the loss-making Ekati diamond mine, in Canada’s Northwest Territories, as owners Burgundy say falling prices have made some of its operations “sub-economic”.

Open pit work at Point Lake kimberlite pipe has been suspended, although operations are continuing at the underground Misery mine 2km away.

Burgundy, the Australian miner that bought Ekati for $136m in 2023, said yesterday (Wednesday 16 July) that “several hundred employees and contractors” were affected, but did not provide an exact figure.

The company requested a trading halt on the Australian Securities Exchange ahead of the layoff announcement.

Workers reportedly learned of the job losses when rotation flights to the remote were cancelled on Wednesday morning – ahead of the actual announcement.

The job losses at Ekati follow layoffs elsewhere in diamond mining, notably the loss of several hundred more jobs at the state-owned Zimbabwe Consolidated Diamond Company (ZCDC).

Ekati, together with Canada’s two other mines – Diavik and Gahcho Kue – is facing the possibility of closure before the end of its lifetime because of dwindling prices. Diavik is due to close in 2029.

Diamond mining is key to NWT’s economy, representing over a quarter of its GDP, but miners have been hit hard by the downturn. Diavik mine lost CAD 127m (USD 94.6m) in 2024.

Source: DCLA

De Beers London launches Vibrations

  De Beers London presents Vibrations: a High Jewellery universe inspired by the quiet yet enduring power of inland water. The collection ce...