Showing posts with label De Beers. Show all posts

Wednesday, 16 September 2026

Diamond Detection Keeps Advancing, And DCLA Has used the Technology for Decades

 DCLA has been at the forefront of diamond detection and disclosure for more than two decades,

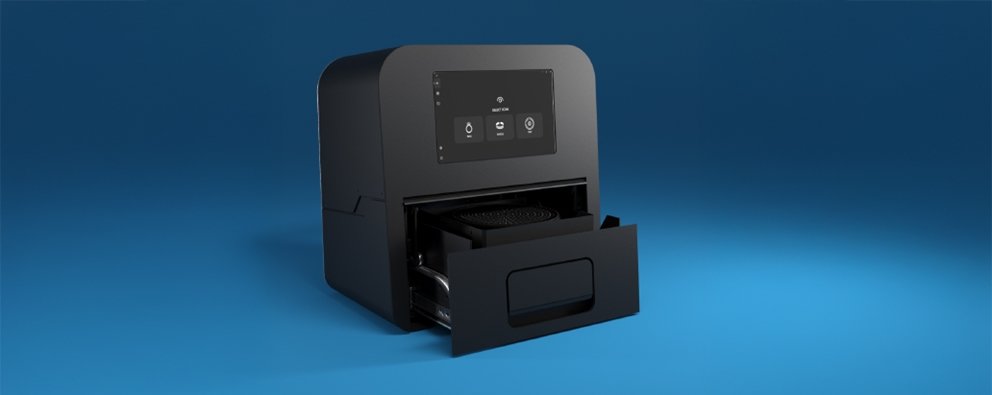
The technology used to identify laboratory-grown diamonds continues to advance, with De Beers Group announcing its next-generation SynthDetect™ 2 desktop diamond screening instrument.

For DCLA, however, the challenge of distinguishing natural diamonds from laboratory-grown diamonds is not new.

DCLA has been at the forefront of diamond detection and disclosure for more than two decades, recognising well before laboratory-grown diamonds became a mainstream commercial product that advances in diamond-growing technology would create a major challenge for the jewellery industry.

The next generation of diamond screening

De Beers says its new SynthDetect™ 2 builds on its earlier SynthDetect and SynthDetect XL instruments, introduced in 2017 and 2018.

According to De Beers, the new system is designed to make screening faster, more automated and easier to integrate into the day-to-day operations of diamond manufacturers, laboratories and retailers.

One of the most significant changes is speed. De Beers says a full tray scan that previously took approximately 30 minutes can now be completed in less than five minutes.

The instrument is designed to screen loose diamonds as well as a wide range of jewellery, including rings, earrings, necklaces, pendants, bracelets and bangles. De Beers states that SynthDetect 2 can screen diamonds from 0.001 to 10 carats in the D–J colour range.

The company says automated results, reporting and software updates are intended to further reduce operator input and improve screening efficiency.

De Beers currently lists SynthDetect 2 as being available from Q1 2027.

De Beers SynthDetect™ 2

DCLA recognised the challenge long before it became mainstream

While new screening technology continues to improve, the underlying problem has been known for many years.

DCLA identified the potential impact of synthetic diamond technology on the Australian diamond industry as early as 2002, when the laboratory warned about advances in technologies such as CVD and HPHT and their potential to produce gem-quality laboratory-grown diamonds that could not be reliably distinguished from natural diamonds by ordinary visual examination.

That early recognition is particularly relevant today.

Laboratory-grown diamonds are real diamonds. They have essentially the same chemical composition and crystal structure as natural diamonds and can look virtually identical to the unaided eye.

The distinction is therefore not something that can reliably be established simply by looking at a stone.

DCLA has previously explained that sophisticated gemmological equipment is required to identify the characteristics associated with different diamond growth processes.

DCLA: Lab-Grown Diamonds — A Structural Disruption to the Traditional Diamond Industry

DCLA: What Is a Lab-Grown Diamond?

Detection has always been part of DCLA’s laboratory process

DCLA’s approach has never been based simply on whether a stone “tests as a diamond”.

That distinction is important.

A basic diamond tester can establish that a stone behaves like diamond. It does not necessarily establish whether that diamond was formed naturally or grown in a laboratory.

DCLA’s laboratory uses advanced analytical technology, combined with experienced gemmological examination, to investigate diamond origin, treatments and other characteristics.

DCLA’s published laboratory process states that diamonds are screened for known treatments and tested to establish whether they are natural or man-made, with grading conducted according to International Diamond Council standards.

The laboratory also uses technologies including DiamondView™ fluorescence imaging, which can reveal growth structures and fluorescence patterns that are not visible under normal lighting.

DCLA Technology & Grading Process

DCLA Our Laboratory and Advanced Diamond Testing Technology

Why the technology race matters

The development of instruments such as SynthDetect 2 demonstrates how quickly diamond-screening technology is evolving alongside diamond-growing technology.

As laboratory-grown diamond production has become more sophisticated, identification technology has had to become more sophisticated as well.

This is not simply a question of identifying whether a stone is “real”.

A laboratory-grown diamond is diamond. The critical question is whether its origin has been correctly identified and disclosed.

That distinction becomes particularly important when diamonds are bought, sold, traded, insured, certified or resold.

DCLA has encountered cases where advanced testing has uncovered synthetic diamonds presented in circumstances where their identity or origin was in question.

In one case documented by DCLA, an HPHT-grown synthetic diamond had been fraudulently inscribed with a report number intended to correspond to a natural diamond. Advanced testing identified differences in the stone’s characteristics and growth origin.

DCLA: Synthetic Diamond Fraudulently Inscribed to Match Natural Diamond Report

More recently, DCLA has also highlighted the risk of certificate swapping, where a genuine certificate may be presented with a different diamond from the one originally examined.

DCLA: Consumer Alert — Certificate Swapping Fraud

Screening is not the same as certification

Modern screening instruments are becoming faster and more accessible to the trade, and that is an important development.

However, screening and independent laboratory certification perform different functions.

A screening instrument can help a business rapidly identify stones requiring further examination.

A professional laboratory can go further by independently examining and documenting the characteristics of the individual diamond.

At DCLA, every diamond submitted for certification is examined by accredited gemmologists in the Sydney laboratory, with advanced instrumentation used alongside traditional gemmological examination.

DCLA — Independent Diamond Certification Laboratory

DCLA’s philosophy has remained consistent

The equipment may change.

The technology may become faster.

The screening process may become increasingly automated.

But the fundamental principle remains the same:

Know what the diamond is.

DCLA has consistently advocated transparency, independent testing and accurate disclosure as laboratory-grown diamond technology has evolved.

From recognising the potential impact of synthetic diamonds more than two decades ago, to using advanced detection technology today, DCLA’s role has been to help the Australian jewellery industry and consumers understand what technology can — and cannot — tell them.

As diamond-growing technology continues to advance, diamond detection technology will continue to evolve with it.

For consumers and the trade, that makes independent verification more important than ever.

A diamond may look natural. A basic tester may say “diamond”. But when origin matters, sophisticated testing and independent documentation provide the evidence.

Thursday, 30 July 2026

From an $18 Billion Giant to a $1 Billion Sale: The Rise and Reinvention of De Beers

 De Beers was the undisputed leader of the global diamond industry.

For more than a century, De Beers was the undisputed leader of the global diamond industry. It transformed diamonds from a relatively rare luxury into the world’s most desired gemstone, creating the modern diamond market through visionary marketing, strict supply management and consumer confidence.

Today, that same company may be sold for as little as US$1 billion, marking one of the most remarkable reversals in the history of the luxury goods industry.

Anglo American Nears Historic Sale

Mining giant Anglo American is reportedly close to selling De Beers as it continues its restructuring following the failed takeover attempt by BHP in 2024.

According to reports, the preferred bidder is the Global Diamond Consortium (GDC), led by former De Beers Chief Executive Gareth Penny and backed by the governments of Namibia and Angola.

The proposed agreement would see GDC pay approximately US$750 million upfront, followed by a further US$250 million at a later stage. Additional performance-based payments may also form part of the final transaction, although negotiations remain ongoing and no final agreement has yet been reached.

The consortium also intends to inject approximately US$500 million into De Beers following the acquisition to strengthen operations and refocus the company on the mining and marketing of natural diamonds.

A Dramatic Fall in Valuation

The potential sale price is extraordinary considering De Beers’ former worth.

When Anglo American acquired the Oppenheimer family’s remaining stake in 2011, the transaction valued De Beers at nearly US$13 billion. During its strongest years, analysts estimated the company’s value exceeded US$18 billion.

However, a combination of falling rough diamond prices, weak Chinese luxury demand, changing consumer spending and the rapid emergence of laboratory-grown diamonds has dramatically reduced profitability across the sector.

Anglo has written down the value of De Beers three times in just three years, reducing its book value to approximately US$2.3 billion earlier this year.

The Company That Built the Modern Diamond Industry

The iconic slogan "A Diamond Is Forever"


While today’s headlines focus on declining valuations, they should not overshadow De Beers’ extraordinary contribution to the global diamond trade.

Few companies have influenced an entire industry as profoundly.

Throughout most of the twentieth century, De Beers controlled the overwhelming majority of the world’s rough diamond supply. Through the Central Selling Organisation (CSO), it managed production, stabilised prices and created confidence that diamonds would retain their value.

Perhaps even more influential was its marketing.

In 1947, De Beers launched the now legendary slogan:

“A Diamond Is Forever.”

That simple phrase fundamentally changed consumer behaviour.

It established the diamond engagement ring as the global symbol of love and commitment and remains one of the most successful advertising campaigns ever created.

For decades, De Beers also invested heavily in consumer education, retailer training, grading standards and worldwide promotional campaigns that helped grow demand across Europe, North America, Japan and later China.

Without De Beers, the global diamond jewellery market as we know it today would likely never have existed.

Botswana Remains Central

Any transaction must also satisfy the Government of Botswana, which owns 15% of De Beers and jointly owns Debswana, the partnership responsible for producing most of Botswana’s diamonds.

President Duma Boko has previously expressed interest in increasing Botswana’s ownership of De Beers, although recent reports suggest the country may instead accept a larger minority stake.

Botswana remains one of the world’s most important diamond-producing nations, and its future relationship with De Beers will be crucial to any successful acquisition.

Gareth Penny Returns

Leading the proposed acquisition is Gareth Penny, who served as Chief Executive of De Beers between 2006 and 2010.

During the Global Financial Crisis, Penny successfully guided the company through one of the most difficult periods in diamond history by temporarily suspending mining operations, reducing supply and securing approximately US$1 billion through a rights offering.

His return signals an intention to restore De Beers’ focus on natural diamonds while adapting to today’s very different market conditions.

Milestones in De Beers History

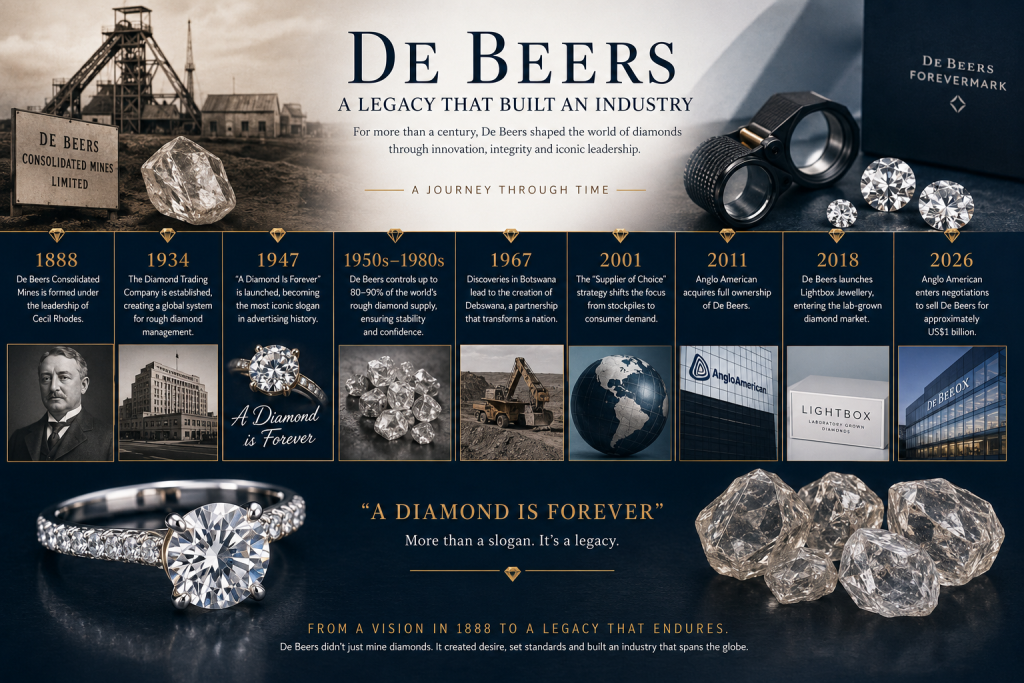
1888 – Cecil Rhodes consolidates South African diamond mining companies to form De Beers Consolidated Mines.

1934 – The Diamond Trading Company is established, laying the foundations for centralised rough diamond distribution.

1947 – The iconic slogan “A Diamond Is Forever” is created by advertising agency N.W. Ayer, forever changing the jewellery industry.

1950s–1980s – De Beers controls as much as 80–90% of the world’s rough diamond supply, creating unprecedented market stability.

1967 – Major discoveries in Botswana eventually lead to the formation of Debswana, transforming Botswana into one of Africa’s greatest economic success stories.

1990s – Increasing production outside the De Beers system begins reducing the company’s market dominance.

2001 – De Beers introduces its “Supplier of Choice” strategy, shifting from stockpiling diamonds to demand-driven marketing.

2011 – Anglo American acquires full ownership of De Beers after purchasing the Oppenheimer family’s stake.

2018 – De Beers launches Lightbox Jewellery to enter the laboratory-grown diamond market, recognising changing consumer trends.

2025 – Lightbox is wound down as De Beers recommits its strategy to natural diamonds.

2026 – Anglo American enters negotiations to sell De Beers for approximately US$1 billion.

A New Beginning Rather Than the End

Although the proposed valuation represents a dramatic decline from De Beers’ former glory, the company still possesses some of the world’s most recognised diamond brands, valuable mining assets and decades of expertise.

More importantly, De Beers leaves behind a legacy that reshaped the global jewellery industry. It pioneered diamond marketing, built international confidence in natural diamonds and helped establish universal grading standards that continue to underpin the modern trade.

The challenge for new ownership will not be rebuilding history—but adapting that remarkable legacy to a new generation of consumers in a market where natural diamonds must increasingly differentiate themselves through rarity, provenance and enduring value.

Source: DCLA

Friday, 24 July 2026

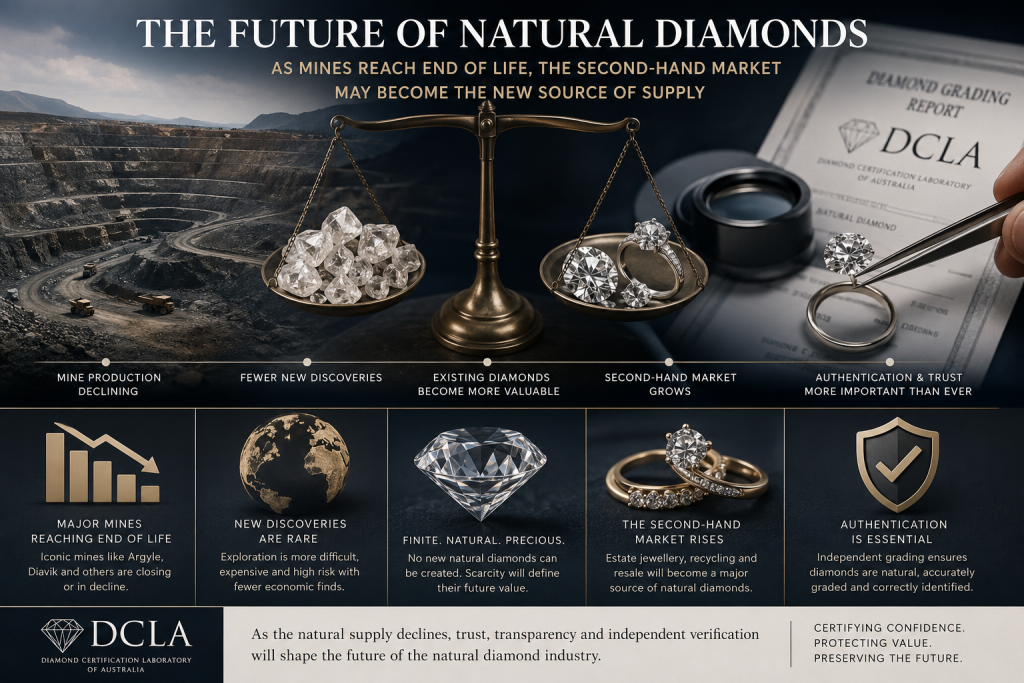
The Future of Natural Diamonds: As Global Mines Reach End of Life, Will the Second-Hand Market Become the New Source of Supply?

 For more than 150 years, the world's natural diamond industry has relied on a steady pipeline of newly mined diamonds entering the market. However, that era is rapidly changing. Many of the world's most productive diamond mines are approaching the end of their economic lives, exploration success has slowed dramatically, and few major new discoveries are expected to replace the enormous production that is disappearing.

For more than 150 years, the world’s natural diamond industry has relied on a steady pipeline of newly mined diamonds entering the market. However, that era is rapidly changing. Many of the world’s most productive diamond mines are approaching the end of their economic lives, exploration success has slowed dramatically, and few major new discoveries are expected to replace the enormous production that is disappearing.

This raises an important question for the jewellery industry, collectors, and consumers alike:

Where will tomorrow’s natural diamonds come from?

The World’s Largest Diamond Mines Are Running Out

Many of the world’s iconic diamond mines are now in decline or nearing closure.

Examples include:

  • Argyle Mine (Australia) – Closed in 2020 after producing more than 865 million carats over its 37-year life. Argyle supplied around 90% of the world’s rare pink diamonds and was once one of the highest-volume producers globally. Its closure permanently removed a significant source of natural diamonds from the market.
  • Diavik Mine (Canada) – Scheduled to cease production around 2026–2027 after two decades of operation.
  • Ekati Mine (Canada) – Although still operating, reserves continue to decline and production has fallen significantly from its peak.
  • Venetia Open Pit (South Africa) – Transitioning to underground mining to extend its life, but at considerably lower production levels and substantially higher operating costs.
  • Jwaneng (Botswana) – Often described as the richest diamond mine in the world, it continues to produce exceptional diamonds, although maintaining production requires increasingly expensive underground expansion projects.
  • Orapa (Botswana) – One of the world’s largest diamond mines by area, but also a mature operation facing the realities of ageing reserves.

Few major discoveries have emerged over the past twenty years that are capable of replacing the millions of carats these operations once produced.

New Discoveries Are Becoming Increasingly Rare

Diamond exploration is an expensive, high-risk undertaking.

Unlike previous decades, when rich kimberlite pipes were discovered in Australia, Canada, Russia and southern Africa, today’s exploration companies face:

  • Much deeper geological targets
  • Increasing environmental approvals
  • Higher capital costs
  • Greater political uncertainty
  • Reduced investor appetite

Even when a new deposit is found, bringing it into commercial production can take well over a decade and require investments measured in billions of dollars.

The result is a steadily shrinking pipeline of new natural diamonds.

Fewer Diamonds Does Not Mean Lower Demand

Although consumer preferences continue to evolve, natural diamonds remain highly sought after for fine jewellery, investment-grade stones and rare collector pieces.

Unlike laboratory-grown diamonds, every natural diamond is a finite geological resource formed between one and three billion years ago. Once mined, no new natural diamonds can be manufactured.

As mining output declines, the existing inventory of polished natural diamonds becomes increasingly important.

The Rise of the Secondary Market

Historically, relatively few diamonds returned to the market.

Natural diamonds were commonly passed through generations as family heirlooms or remained in jewellery collections for decades.

However, several factors are beginning to change this:

  • An ageing population transferring wealth
  • Estate jewellery entering the market
  • Increased recycling by professional jewellers
  • Specialist diamond buying companies
  • Greater consumer awareness of resale value
  • Online marketplaces making resale easier

Over time, previously owned natural diamonds may become one of the largest sources of supply for the jewellery trade.

Much like antique watches, rare coins and fine art, existing natural diamonds may circulate repeatedly between owners while no meaningful replacement supply enters the market.

Recycling Diamonds Is Not New

The diamond trade has quietly recycled diamonds for centuries.

Antique European jewellery has often been dismantled and remounted multiple times as fashions changed.

Victorian diamonds became Edwardian jewellery.

Edwardian diamonds became Art Deco pieces.

Art Deco diamonds have been reset into modern engagement rings.

The diamond itself may have changed settings numerous times while remaining the same natural gemstone throughout its life.

This process is likely to accelerate as newly mined diamonds become increasingly scarce.

Authentication Will Become More Important Than Ever

As more diamonds enter the secondary market, authentication will become increasingly critical.

Consumers will want certainty that the diamond they are purchasing is:

  • Natural rather than laboratory-grown
  • Correctly identified
  • Accurately graded
  • Free from undisclosed treatments
  • Properly documented

This places greater importance on independent laboratory grading.

Professional laboratories such as DCLA play an essential role in verifying the identity and quality of diamonds entering both the primary and secondary markets. Independent examination provides confidence for buyers, sellers, insurers and future owners alike.

The Growing Challenge of Laboratory-Grown Substitution

One emerging concern is the increasing number of natural diamond certificates being fraudulently paired with laboratory-grown diamonds or simulants.

As DCLA has previously reported, certificates can be separated from the original stone, creating opportunities for deliberate substitution. As secondary market activity increases, verifying that the diamond matches its accompanying grading report will become essential.

Independent examination helps protect both consumers and the integrity of the natural diamond market.

A Market That Could Resemble Fine Art

Natural diamonds possess one characteristic that laboratory-grown diamonds can never replicate—true geological scarcity.

As mine production continues to decline, natural diamonds may increasingly resemble other finite luxury assets such as fine art, vintage automobiles and rare watches.

Their value will not simply depend on beauty or craftsmanship, but also on rarity, provenance and authenticated identity.

The second-hand market is therefore likely to evolve from an occasional source of supply into a fundamental pillar of the global natural diamond industry.

Looking Ahead

The natural diamond industry is entering a period of structural change.

Mine production is expected to continue declining over the coming decades, while new discoveries remain scarce and increasingly difficult to develop. Existing polished diamonds already in private ownership represent an enormous reservoir of future supply.

As these stones gradually re-enter the marketplace through resale, estate collections and jewellery recycling, confidence in independent authentication will become more important than ever.

For laboratories such as DCLA, this evolving landscape reinforces a central responsibility: ensuring every diamond can be accurately identified, independently graded and matched to its rightful documentation. In a future where existing natural diamonds become an increasingly valuable and finite resource, trust will be as important as the diamonds themselves.

Disclaimer: This article is intended for general industry information and commentary. Market conditions, mine production and future supply forecasts are subject to change. DCLA encourages consumers and members of the jewellery trade to obtain independent laboratory verification when buying, selling or re-entering natural diamonds into the marketplace.

Wednesday, 8 July 2026

De Beers Slashes Diamond Prices and Reshapes Its Elite Buyer Network


The global diamond industry may have reached a major turning point.

De Beers has implemented some of the largest official rough diamond price reductions in its modern history while simultaneously removing almost one-third of its exclusive group of authorised buyers. The move represents a dramatic shift in strategy after years of attempting to keep official prices well above prevailing market levels.

For the diamond trade, manufacturers and retailers, this is more than simply a pricing adjustment it is a clear acknowledgement that market forces can no longer be ignored.

Official Prices Finally Catch Up With Reality

For much of the past three years, De Beers resisted cutting its published rough diamond prices despite a sharp fall in global demand.

Instead, the company quietly sold selected goods through confidential discounted transactions while maintaining higher official prices to preserve confidence throughout the industry.

That approach has now come to an end.

During its July 2026 sales cycle, De Beers made sweeping reductions across nearly every category of rough diamonds. Industry sources indicate that some categories had previously been priced between 5% and 50% above equivalent goods trading in the secondary market.

The latest reductions bring De Beers’ official pricing much closer to actual market values.

Although the company has declined to comment publicly on the exact reductions, the changes are widely regarded as some of the deepest official price cuts ever made by the company.

Understanding the Sightholder System

To appreciate why these price cuts are so significant, it is important to understand how De Beers sells its diamonds.

Unlike many commodities, rough diamonds are not sold on open exchanges.

Instead, De Beers operates through its long-established Sightholder System, a carefully selected network of approved companies invited to purchase rough diamonds directly from the miner.

These companies attend ten scheduled “sights” each year.

At each sight, buyers are offered parcels or “boxes” of rough diamonds at fixed prices determined by De Beers. There is generally little or no room for negotiation. Buyers may accept or decline the allocation, but historically repeated refusals risked losing their coveted sightholder status.

For decades, this system allowed De Beers to exercise remarkable control over the supply of rough diamonds entering the global manufacturing pipeline.

By carefully managing both supply and pricing, the company was able to influence the broader diamond market more effectively than almost any other mining company.

Fewer Buyers, Greater Concentration

The July 2026 sight is also the first held under newly negotiated supply agreements.

Perhaps the biggest structural change is the reduction in De Beers’ exclusive buyer network.

The number of authorised sightholders has been reduced from around 70 companies to approximately 45–50.

The objective is straightforward.

De Beers wants a smaller group of financially stronger customers capable of purchasing larger volumes while maintaining long-term commitments to the business.

The company believes concentrating sales among its strongest clients should reduce the number of diamonds being immediately resold into secondary markets, where discounted trading has undermined official pricing for several years.

In theory, fewer buyers should allow De Beers to exercise tighter control over the distribution of rough diamonds.

However, the strategy also carries greater risk.

With fewer customers, De Beers becomes increasingly dependent upon the financial health of each remaining sightholder. Should several major buyers reduce purchases or encounter financial difficulties, there are fewer alternative customers available to absorb production.

Why Is De Beers Changing Strategy?

The decision reflects several years of mounting pressure across the global diamond industry.

China, once one of the world’s fastest-growing luxury jewellery markets, has experienced a significant slowdown in consumer spending. Demand for diamond jewellery has weakened substantially, removing one of the industry’s largest growth engines.

At the same time, laboratory-grown diamonds have become increasingly popular, particularly in the bridal jewellery sector, where consumers can purchase much larger stones at a fraction of the price of natural diamonds.

The market has also faced increased competition from additional rough diamond supply entering global markets from countries including Angola.

Adding further uncertainty have been ongoing geopolitical tensions, US trade tariffs and slowing global economic growth, all of which have reduced consumer confidence in luxury spending.

Together, these factors have produced one of the deepest and longest downturns the diamond industry has experienced in decades.

Less Transparency Than Before

Ironically, while prices have become more market-driven, pricing transparency has actually decreased.

Earlier this year De Beers introduced a new “one-line invoicing” system.

Rather than providing detailed prices for each category of rough diamonds within a parcel, buyers now receive a single combined total for the entire box.

At the same time, the company has altered the composition of many assortments.

These changes make it difficult for manufacturers and market analysts to determine exactly how much individual categories of diamonds have increased or decreased in value.

This reduced transparency makes independent price analysis significantly more challenging than under the previous system.

A Business Preparing for Sale

The pricing changes also arrive during a crucial period for parent company Anglo American.

Since May 2024, Anglo American has been working to divest De Beers as part of a broader restructuring programme following years of declining profitability.

Potential buyers continue to evaluate the world’s most famous diamond producer while the company attempts to stabilise earnings and restore confidence throughout the market.

Resetting prices closer to genuine market levels may ultimately make De Beers a more commercially attractive business by reducing the disconnect between official pricing and actual trading conditions.

What It Means for the Diamond Industry

De Beers’ latest decisions signal more than a temporary response to weak trading conditions.

They represent a recognition that the natural diamond market has fundamentally changed.

The company appears to be abandoning a long-standing strategy of defending premium pricing in favour of allowing market realities to shape official valuations.

Whether these changes successfully restore confidence remains to be seen.

For manufacturers, wholesalers and retailers, pricing that more accurately reflects real market conditions may improve margins and encourage renewed trading activity.

For consumers, however, the changes are unlikely to produce dramatic retail price reductions in the short term, as jewellery prices are influenced by manufacturing costs, branding, retail margins and consumer demand as much as the price of rough diamonds themselves.

What is clear is that De Beers has entered a new chapter one where flexibility, commercial realism and supply discipline are becoming more important than maintaining the appearance of price stability.

Disclaimer: This article is provided for general information and industry commentary only. It does not constitute financial, investment or professional advice. Market conditions, diamond prices and industry developments may change without notice. Readers should undertake their own research or seek independent professional advice before making any commercial or investment decisions.

Source: DCLA

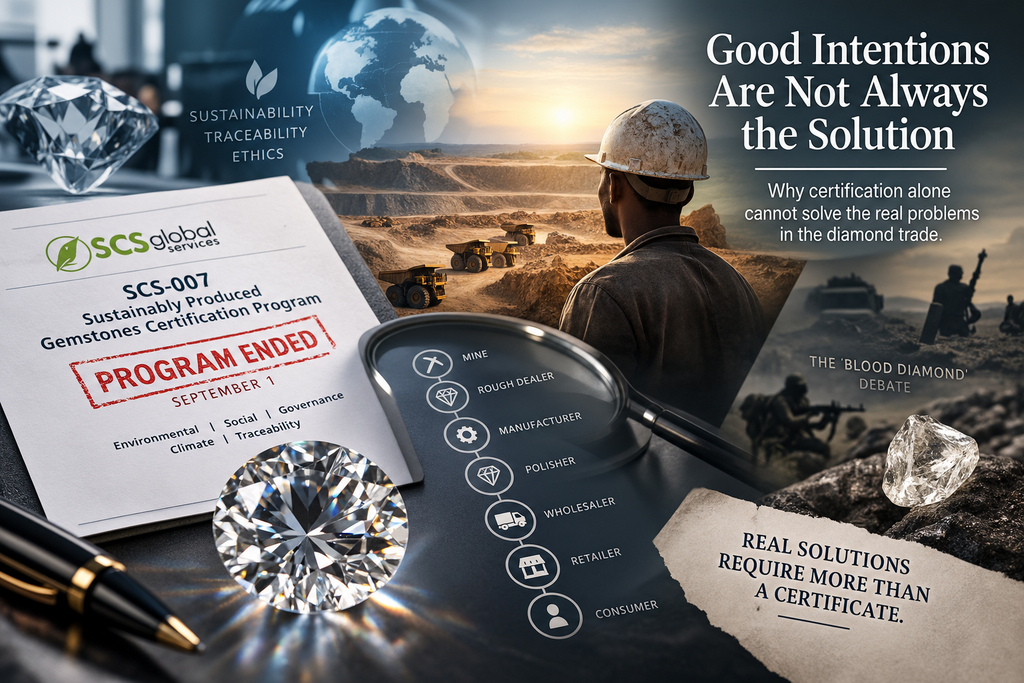
When Good Ideas Do Not Always Solve the Problems in the Diamond Trade

  The diamond industry has spent decades trying to address questions around sustainability, traceability, ethics and responsible sourcing. T...