Showing posts with label Petra Diamonds. Show all posts

Friday, 2 October 2026

Petra Diamonds Weighs Sale as Diamond-Market Pressures Mount

 Strategic review highlights the financial pressure facing one of Africa’s best-known natural diamond producers

Strategic review highlights the financial pressure facing one of Africa’s best-known natural diamond producers

Petra Diamonds has launched a strategic review that could ultimately lead to the sale of some or all of its assets, as the company faces continuing liquidity pressures, weak natural diamond prices and significant operational challenges at its Finsch mine in South Africa.

The London-listed diamond producer announced on 1 October that, following discussions with key stakeholders including its first and second lien creditors, it would examine all available options for addressing its near-term liquidity requirements. These options include a potential sales process involving the company’s assets. Petra is also in the process of appointing a financial adviser to assist with the review.

At the same time, José Manuel Vargas stepped down as chairman and a director of the company. Lerato Molebatsi has been appointed interim chair.

The developments are significant because Petra is not simply another diamond producer. Over almost three decades, the company has built a portfolio around some of the world’s most historically important diamond mines.

From junior explorer to major diamond producer

Petra Diamonds was first admitted to trading on London’s AIM market in April 1997 with a market capitalisation of approximately £8.75 million. It subsequently moved to the Main Market of the London Stock Exchange in December 2011.

The company’s growth was driven in large part by acquiring diamond assets that were considered non-core by larger mining groups, including De Beers.

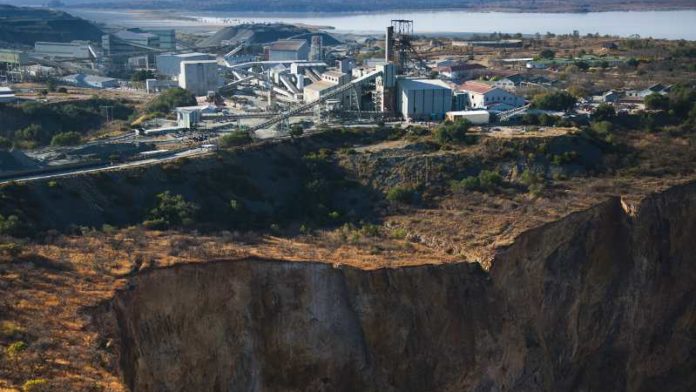
Among its most important acquisitions was the Cullinan Mine in South Africa, acquired by Petra in stages from 2008. In 2011, Petra acquired a majority interest in Finsch, one of South Africa’s most significant diamond mines.

Petra subsequently became associated with an extraordinary collection of diamond-producing assets and some remarkable stones.

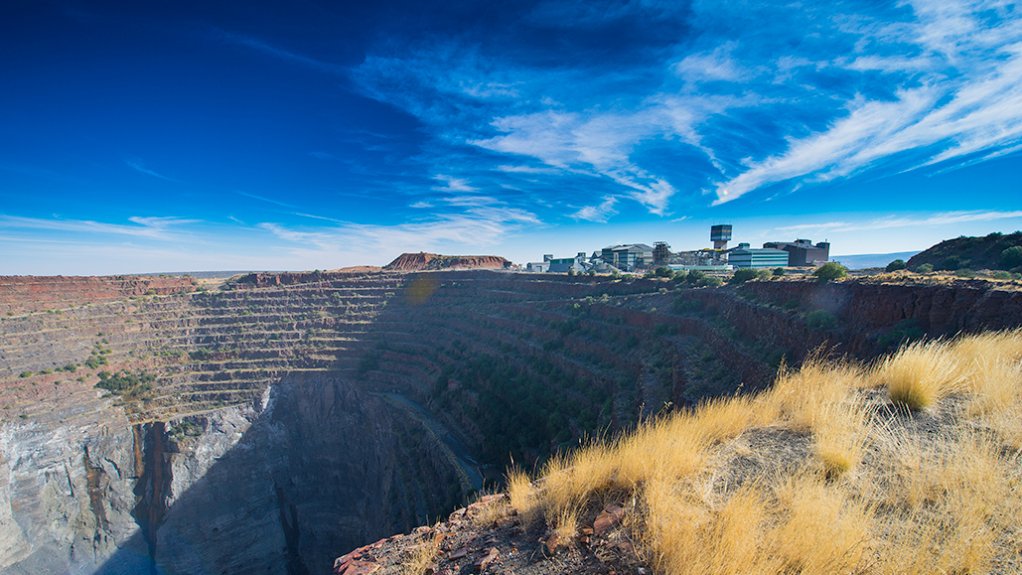
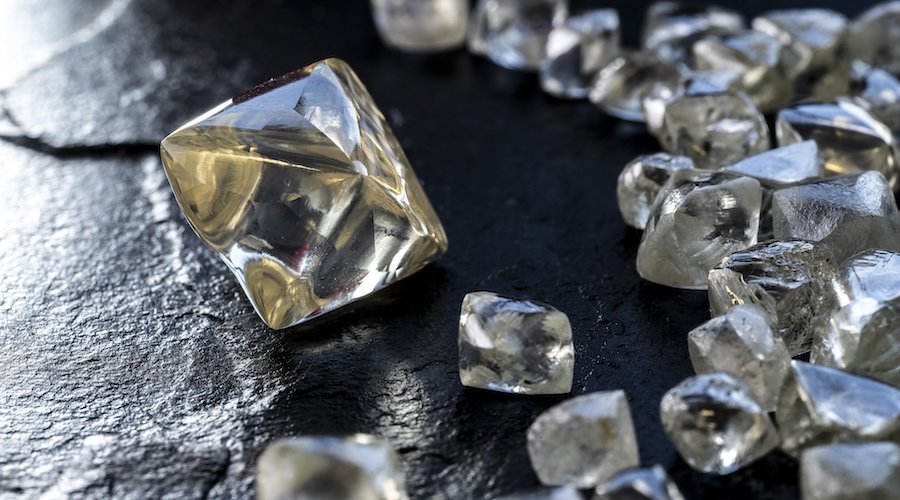
The Cullinan Mine is perhaps the most famous. Originally known as the Premier Mine, it produced the 3,106-carat Cullinan diamond, the largest gem-quality rough diamond ever discovered. The stone was ultimately cut into several important diamonds, including the Great Star of Africa and the Second Star of Africa, both of which form part of the British Crown Jewels.

Cullinan has also produced some of the world’s most notable blue diamonds, including a Type IIb blue diamond that Petra sold in 2021 for US$40.2 million, equivalent to more than US$1 million per carat.

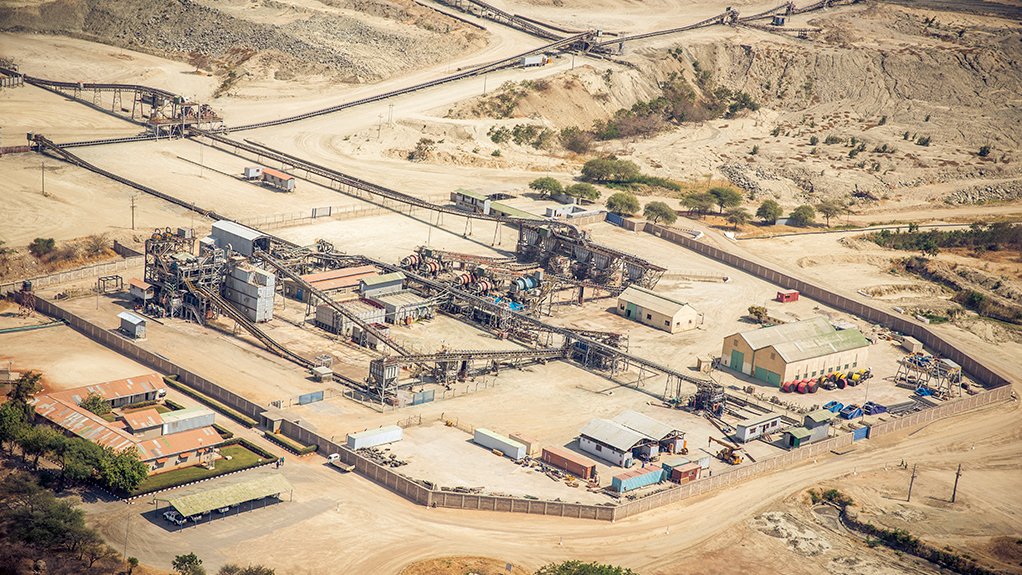
Finsch has its own remarkable history. The mine has been operating since 1967 and is known for producing commercial-quality diamonds, including larger stones above five carats, as well as occasional exceptional diamonds exceeding 50 carats. Petra has operated the mine since 2011.

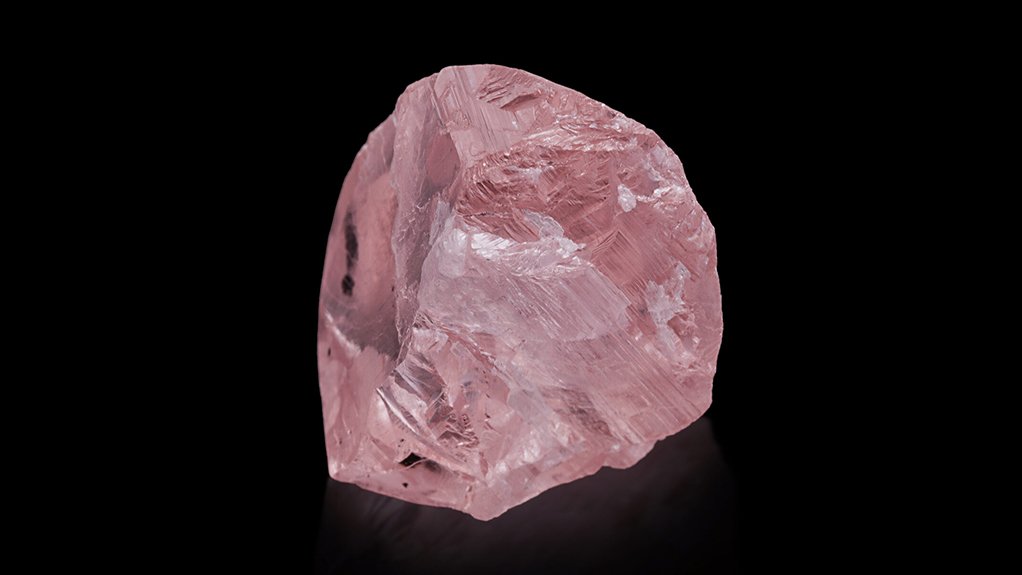
Petra’s history also includes the Williamson mine in Tanzania, famous for the Williamson Pink, a 54-carat rough pink diamond discovered in 1947. The polished stone became a gift to Princess Elizabeth, later Queen Elizabeth II. Petra sold its interest in Williamson in 2025 as part of its strategy to streamline its portfolio.

Finsch becomes a major pressure point

The immediate financial problem, however, is centred on Finsch.

The mine entered business rescue in May 2026 and production was subsequently suspended. Petra has said that, despite strong operating performance, the mine’s high proportion of smaller diamonds, combined with the strength of the South African rand and exceptionally difficult market conditions, made the operation economically unsustainable in its existing form.

Petra reported consolidated net debt of approximately US$322 million at 30 June 2026, compared with US$298 million three months earlier. The company said its cash position had become increasingly constrained by weaker diamond prices and the ring-fencing of cash associated with the Finsch business-rescue process.

The company has already secured additional short-term working capital support from its senior lender, including a R300 million facility, while discussions around a broader refinancing have continued.

The latest strategic review therefore represents a further step in Petra’s efforts to protect liquidity and determine how its remaining assets can be structured for the future.

The wider natural diamond squeeze

Petra’s difficulties should also be viewed within the much broader disruption experienced by the natural diamond industry.

Diamond producers, manufacturers, wholesalers and retailers have faced a combination of weaker consumer demand, economic uncertainty, excess inventory, changing purchasing patterns and increased competition from laboratory-grown diamonds.

The result has been substantial pressure on rough diamond prices and on the economics of mining.

Petra’s own history illustrates the dramatic change in the industry. The company produced more than 4.6 million carats in 2018, whereas its current portfolio is considerably smaller following the disposal of several assets.

The company has also undertaken cost reductions, portfolio rationalisation and debt restructuring in an effort to adapt to the new market environment.

For the natural diamond industry, however, there is an important distinction between falling production and falling demand.

A natural diamond supply reset?

Global diamond production has been falling sharply as producers respond to weaker economics. Industry analyst Paul Zimnisky has pointed to the possibility that declining mine supply could eventually help rebalance the market.

Lower production may gradually remove some of the excess supply that has weighed on rough diamond prices. But that does not guarantee an immediate recovery. The industry still needs sustainable consumer demand, healthy inventories and prices that allow mines to operate profitably.

For companies such as Petra, the timing is critical.

A reduction in global mine supply could ultimately provide support for natural diamond prices, but producers carrying substantial debt cannot necessarily wait indefinitely for a future market recovery.

The changing diamond landscape

The difficulties facing Petra also highlight an important reality about diamonds: a diamond mine is a finite natural resource, and maintaining production is extraordinarily capital intensive.

Laboratory-grown diamonds have introduced another layer of competition into the lower and middle sections of the jewellery market. Unlike natural diamonds, laboratory-grown stones can be manufactured in virtually unlimited quantities, meaning their economics are fundamentally different from a scarce geological resource that can take billions of years to form.

This distinction is increasingly important when considering the long-term value proposition of natural diamonds.

Natural diamonds are not simply manufactured products. They are geological rarities, with their supply ultimately constrained by the number of economically viable deposits that exist on Earth.

The challenge for the natural diamond industry is therefore not simply producing diamonds. It is maintaining a balance between scarcity, consumer demand, mine economics and market confidence.

What happens next?

Petra’s strategic review does not mean that a sale will necessarily occur. The company has said that all potential avenues for addressing its liquidity requirements are being considered, with any outcome dependent on the review and discussions with stakeholders.

Possible outcomes could include asset transactions, further financing, restructuring or a broader corporate transaction.

Whatever the eventual outcome, Petra’s situation is a reminder of how dramatically the natural diamond industry has changed.

A company that grew from a small junior explorer in 1997 into the owner and operator of some of the world’s most celebrated diamond assets is now having to reconsider its structure in response to one of the most challenging periods the modern diamond industry has experienced.

For DCLA, the story also reinforces an important point: the rarity and provenance of a natural diamond remain fundamental to understanding what makes exceptional diamonds different from mass-produced alternatives.

From the Cullinan diamond and historic blue diamonds to the Williamson Pink and the exceptional stones recovered at Finsch, Petra’s history is intertwined with some of the most important diamonds ever discovered.

The question now is whether the next chapter of that history will be written under Petra’s ownership — or by a new generation of owners.

Wednesday, 3 June 2026

Another Diamond Mine in Trouble, But Signs of Recovery Are Emerging

 Petra diamonds

The global diamond industry has suffered another setback, with Petra Diamonds announcing a business rescue plan for its financially distressed Finsch Mine in South Africa. The move highlights the ongoing pressure facing natural diamond producers after several years of declining prices and weakening demand.

Under South African law, a business rescue practitioner can be appointed when a company is unlikely to meet its financial obligations within the next six months. Petra Diamonds said the decision was necessary to preserve the future of the operation and maximise value for stakeholders.

Petra Chief Executive Vivek Gadodia cited a combination of persistently weak diamond prices and the strength of the South African rand as key factors behind the mine’s financial difficulties. While mining costs have remained elevated, revenue from diamond sales has failed to keep pace, placing significant strain on profitability.

The Finsch Mine, one of South Africa’s most important diamond producing assets, now joins a growing list of operations worldwide that have faced closure, suspension, or restructuring during the deepest downturn the diamond industry has experienced in decades.

A major factor behind the crisis has been the rapid rise of laboratory grown diamonds. The dramatic fall in the retail price of synthetic stones has disrupted traditional diamond markets and placed downward pressure on natural diamond prices. As consumers increasingly compare natural and laboratory grown products, mining companies have been forced to navigate one of the most challenging periods in the history of the industry.

The impact has been felt across the entire diamond supply chain. Russian mining giant Alrosa continues to struggle with weak prices, compounded by geopolitical pressures and sanctions. The company’s share price recently fell to an all time low of 25 rubles, representing a decline of almost 50 per cent over the past year and more than 80 per cent over the past five years.

De Beers has also been forced to confront the new market reality. Parent company Anglo American has recorded a series of substantial write downs on its diamond business, including US$2.3 billion in the most recent reporting period. This follows impairments of US$2.9 billion in 2024 and US$2.6 billion in 2023, reflecting the severe decline in the value of diamond inventories and mining assets.

Despite the continued challenges, there are emerging signs that the worst of the crisis may be passing. Several major producers have significantly reduced rough diamond production over the past two years, helping to rebalance supply with demand. Inventories throughout the pipeline have also been gradually worked down, while the widening price gap between natural and laboratory grown diamonds is reinforcing the unique rarity and investment appeal of natural stones.

Industry analysts are increasingly suggesting that the natural diamond market may be approaching a turning point. Although a rapid recovery is unlikely, production cuts, reduced inventories, and stabilising consumer demand could lay the foundation for a healthier market in the years ahead.

For now, the restructuring of Petra’s Finsch Mine serves as another reminder of the profound transformation taking place within the global diamond industry. However, after years of falling prices and mine closures, there is growing evidence that the sector may finally be moving closer to a long awaited recovery.

Source: DCLA

Wednesday, 14 January 2026

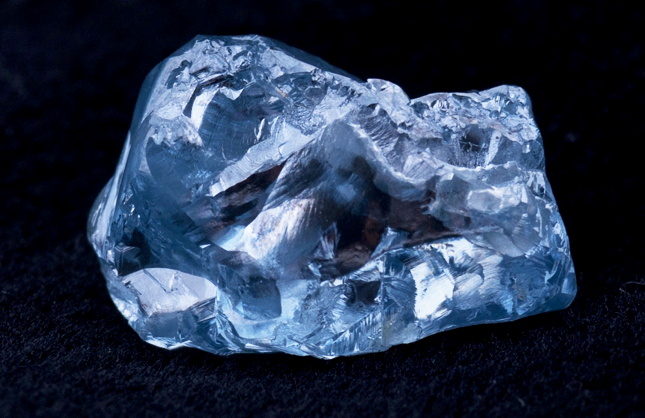
Petra Recovers Huge 41.82-ct Blue Diamond

 Petra  41.82-carat Type IIb blue diamond

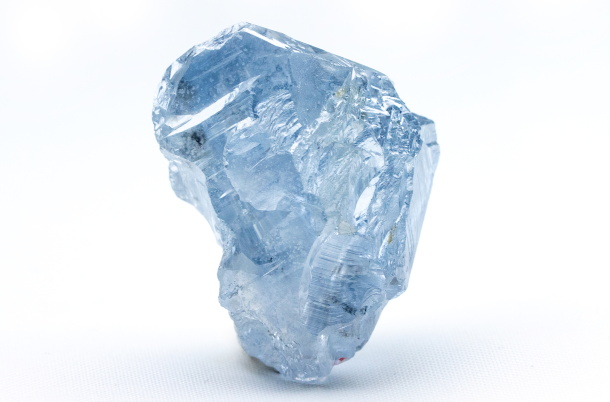
Petra Diamonds today announced the recovery of a huge 41.82-carat Type IIb blue diamond at its Cullinan Mine, in South Africa.

The UK-based miner described the stone as being of “seemingly exceptional quality in terms of both its colour and clarity”.

The iconic Cullinan mine is known for recovering high-value blue stones.

Last April it sold a 14.76ct blue stone, of “exceptional color and clarity” for $8.2m.

In July 2021 it sold a 39.34-carat blue diamond for $40.18m. The Letlapa Tala collection of five blue diamonds sold in November 2020 for $40.36m.

And a 29.60-carat rough that was cut into the Blue Moon sold for $25.6m in February 2014. It was subsequently auctioned in 2015 for $48.5m to Hong Kong billionaire Joseph Lau, who renamed it the Blue Moon of Josephine.

Petra says it is in the process of analyzing the stone and deciding on a preferred method of the sale.

In October Petra Diamonds announced details of a $25m rights issue to keep the company afloat as it battles falling prices and production, together with rising debt and cash flow difficulties.

Revenue for FY2025 was $206m, down 33 per cent year-on-year from $309m and net debt increased to $264m.

Source: DCLA

Monday, 12 January 2026

Global Diamond Industry Shows Signs of Recovery: What Is Driving the Rebound?

 Global Diamond Industry Shows Signs of Recovery

After three challenging years marked by geopolitical disruption, shifting trade routes, and weakened consumer confidence, the global diamond industry is beginning to stabilise and recover. While price volatility persists in certain segments, demand is gradually rebuilding, particularly across the world’s primary luxury markets. Industry professionals broadly agree that the recovery remains uneven, but the direction is clear: a slow yet meaningful turnaround is underway.

Senior figures within the international jewellery trade point to improving economic sentiment as a key catalyst behind renewed interest in diamonds. Changing consumer behaviour is also playing a central role. Natural diamonds continue to dominate global engagement ring sales, retaining their status as the benchmark for long-term value and emotional significance. However, competition from lab-grown diamonds is intensifying, and the market share gap is narrowing.

In major Western markets, lab-grown diamonds are gaining traction, particularly among younger buyers who place greater emphasis on size, clarity, and price accessibility than on tradition. This generational shift is reshaping purchasing decisions and influencing how value is assessed at the point of sale.

Pricing dynamics underscore this transformation. Over the past year, prices for smaller natural diamondsespecially those under one carat have experienced notable declines. At the same time, lab-grown diamond prices have fallen even further, driven by rapid technological advancements and expanding production capacity. Together, these opposing movements have redefined the competitive landscape, prompting consumers to compare value propositions more closely than ever before.

While challenges remain, the combination of stabilising demand, evolving consumer preferences, and market-driven price realignment suggests the diamond industry has entered the early stages of recovery, with long-term implications for both natural and lab-grown sectors.

Source: DCLA

Tuesday, 12 August 2025

Petra to Refinance as Sales Slide by a Third

Petra Diamonds - Cullinan Diamond Mine

Petra Diamonds has announced plans for a major refinancing program – together with a 33 per cent slide in revenue for FY2025.

The UK-based miner, which has recently sold off two of its four diamond mines, is facing substantial financial and operational challenges.

It is proposing an extension of senior secured bank debt and notes due early next year to 2029 and 2030 respectively, together with a $25m rights issue.

The moves are designed to preserve cash, extend debt repayment timelines, and ensure Petra can continue investing in its two remaining core mines – Cullinan and Finsch, both in South Africa.

Petra’s latest sales results, published on the same day (8 August) as its refinancing package, show some positive momentum in the market with like-for-like rough diamond prices from its latest tender, but revenue for Q4 was down 49 per cent year-on-year to $50m.

Revenue for FY2025 was $206m, down 33 per cent year-on-year from $309m and net debt increased to $264m.

“We would once again like to acknowledge the resilience shown by our employees in navigating a very difficult period for the company and the diamond sector as whole,” the company said in its Q4 and FY 2025 Operating Update.

Meanwhile, in its refinancing proposal Petra said: “Petra has, over the past 18 months, been focused on an internal restructuring that has resulted in a simpler and more streamlined business and operating model.

“This has included the sale of the Koffiefontein and Williamson mines, multiple labour restructuring initiatives and an optimisation and smoothing of the group’s capital development profiles.”

Source: DCLA

Tuesday, 10 June 2025

Petra Diamonds rethinks sales tactics as market slump drags on

Africa-focused Petra Diamonds has scrapped regular diamond tenders in favour of opportunistic sales as the market for rough stones continues to slump.

Africa-focused Petra Diamonds has scrapped regular diamond tenders in favour of opportunistic sales as the market for rough stones continues to slump.

The miner reported $53 million in sales from its fifth and sixth tenders of the year, covering production from its two South African mines. Petra will now report sales on a quarterly basis instead of following a fixed tender schedule.

“In response to fluctuations in diamond prices and demand, the company no longer follows regular tender cycles and may postpone portions of tenders or sell goods as run-of-mine,” the company said.

The strategic pivot mirrors De Beers’ reported off-market sales of discounted diamonds to selected clients. The move aimed to reduce inventory without officially slashing prices.

Petra said it sold 613,747 carats in the two tenders, a 29% increase from its fourth tender in February. The average price was $86 per carat, about 4% higher than February’s auction. On a like-for-like basis, prices were down 16% compared to the first six tenders of 2024, largely due to lower-value goods.

Year-to-date, the company has sold 2.39 million carats for $239 million, down from $329 million over the six first tenders of its 2024 financial year.

Petra delayed its April and May tenders due to a weaker product mix at its flagship Cullinan mine. The Finsch mine, meanwhile, saw improved pricing thanks to better ore access. The company expects an improved product mix as it ramps up production from the CC1E and the western side of the C-Cut block.

Petra also drew an additional $33 million in debt, bringing its consolidated net debt to $258 million by the end of March. It attributed this to working capital requirements.

“The continuing challenges in the diamond market and the weaker sales do not bode well given the ongoing negotiations to refinance Petra’s debt obligations,” Raj Ray, an analyst at BMO Capital Markets, wrote on Monday.

Petra has been restructuring to cut costs, including the sale of its stake in Koffiefontein in October and the recent $16 million sale of the Williamson mine in Tanzania.

Petra shares fell almost 3.5% on the news to 19.5 pence each, putting its market cap at about £38 million ($51 million).

Source: DCLA

Friday, 23 May 2025

Petra Diamonds hits all-time low as cash burn continues

Petra's Cullinan mine

Petra Diamonds is to begin discussions with financiers on refinancing a $273m bond that matures in March next year amid scepticism that the company will survive the event.

The ratings agency S&P last week downgraded the company’s credit to CCC on the increased likelihood of default, and maintained a negative outlook.

Shares in the company fell 10% today shortly after the company posted its third quarter results. Petra is now trading at a fresh all-time low and is valued at only £34m on the London Stock Exchange.

While its remaining two assets – the Cullinan and Finsch mines in South Africa – had a solid three months operationally, with a quarter to go, full year guidance has been maintained at 2.4 to 2.7 million carats.

However, the company is still burning cash.

Petra drew on a further $33m as consolidated net debt increased to $258m as of end-March, which the company put down to working capital requirements.

The truth is that the company is desperately in need of improved diamond prices, which have continued to trough this year amid economic uncertainty generated by US President Donald Trump’s on-off tariff regime.

Petra said in April that it had postponed the sale of about 200,000 carats of diamonds from the Cullinan mine near Pretoria because of the “considerable diamond market uncertainty caused by the US tariffs announcement”.

“S&P believes the company faces mounting liquidity challenges amid uncertainty regarding the recovery of the rough diamond market and approaching debt maturities in 2026, with increased likelihood of default – including distressed exchange or debt restructuring – over the next 12 months, if Petra is unable to refinance its debt maturities on time,” said analysts at Berenberg Bank in a note last week.

Commenting on the third quarter results – in which revenue fell to $42m from $106m in the comparative quarter last year (buoyed by sales from a deferred tender) – interim joint CEOs Vivek Gadodia and Juan Kemp, said Petra had experienced “a very difficult diamond market”.

They added: “We believe the steps we have taken over the past 12 months position Petra well for a successful refinancing. We will now look to commence engagements with our lenders on the refinancing of our debt maturing in early 2026.”

Source:miningmx.com

Friday, 16 May 2025

Tanzania’s Williamson Diamonds goes totally Pink

Williamson Pink Diamonds

London-listed and South Africa-active Petra Diamonds has sold its entire shareholding in Williamson Diamonds of Tanzania, plus all shareholder loans owed to it, to Pink Diamonds Investments, also of Tanzania.

Pink diamonds are known for their pink hue, ranging from light to deep rose.

The up-to-$16-million transaction has obtained Tanzanian Fair Competition Commission approval for Williamson ownership now vesting entirely with Pink, a Taifa affiliate, which is viewed as possessing the technical and financial capability to conduct operations for the benefit of stakeholders.

With more than three decades of mining-related experience, Taifa’s working relationships extend to mining majors such as De Beers, Barrick and AngloGold Ashanti, and the company is now entering a phase of exclusive ownership of an asset where about 1 100 people are employed, most of them Tanzanian.

The mine’s reserves and resources as of June 30 were reported as 37.17-million carats. With liquidity challenges continuing, further capital investment will be required.

Petra Diamonds

Twenty per cent of any distributable cash generated annually by Williamson will be payable by Pink Diamonds to Petra until the selling price is met, Petra joint interim CEO Vivek Gadodia outlined in a release to Mining Weekly, in which he wished Pink all of the best as its takes over the mine, the kimberlite pipe of which was discovered by Canadian geologist John Williamson in 1940 and which led to ongoing operation since then, making it one of the world’s oldest continuous operating diamond mines. Its yield of 19-million-plus diamond carats includes a 54.5 ct Williamson pink diamond that was presented to British royalty in 1947.

Meanwhile, Petra, with the Cullinan and Finsch underground diamond mines in South Africa, is focusing on value rather than volume at a time when diamond-mining headwinds are tending to dominate the headlines and the usual sale of rough diamonds at acceptable prices is reportedly proving difficult.

This has resulted in the stockpile of rough diamonds held by De Beers, for example, rising to $2-billion, which, according to a report in the Financial Times, is the biggest hold back of rough diamonds since the financial crisis of 2008.

Source: DCLA

Thursday, 10 April 2025

Petra Diamonds delays sale amid US tariffs uncertainty

Tender of diamonds from the Williamson mine in Tanzania proceeded as planned.

Africa-focused Petra Diamonds has postponed a scheduled sale of about 200,000 carats of diamonds from its Cullinan mine in South Africa, citing uncertainty over the impact of new US tariffs.

Last week, US President Donald Trump announced sweeping import tariffs ranging from 10% to over 100%, including a 30% duty on many South African goods. The move has injected volatility into the global diamond market.

Petra, which holds the world’s third-largest diamond resource, said the decision to delay the Cullinan sale aims to secure stronger market prices once the tariff situation becomes clearer. The sale had been expected to generate approximately $18 million in revenue.

Despite the disruption, the company managed to complete sales from its Finsch mine in South Africa and the Williamson mine in Tanzania before the tariffs were introduced.

South Africa remains one of the largest diamond exporters to the US, alongside India.

So far in the 2025 financial year, Petra has earned $103 million from rough diamond sales, down from $138 million during the first five tenders of the previous year.

Source: mining.com

Tuesday, 18 February 2025

Duffy resigns as Petra CEO, interim revenue knocked by market weakness

Petra Diamonds, which owns and operates diamond mines in South Africa

Independent mining group Petra Diamonds, which owns and operates diamond mines in South Africa, has appointed two interim CEOs Vivek Gadodia and Juan Kemp to succeed Richard Duffy, who has resigned by mutual agreement and with immediate effect.

Gadodia will oversee all corporate matters of the group, while Kemp will oversee all operational matters.

At this point, they will not be appointed as directors.

Vivek joined Petra in 2021 with his roles having included planning and corporate planning executive and chief restructuring officer. He previously worked for Sasol in various engineering, project management and corporate positions over a 15-year period.

Kemp, meanwhile, joined Petra in 2009 when the company bought its flagship Cullinan mine from fellow miner De Beers.

Kemp was GM of the mine since 2011 before having been appointed as a chief technical officer in 2019 and operations executive for the Cullinan mine in 2024.

His earlier career included positions at De Beers and AngloGold Ashanti.

The appointments of the interim CEOs come as Petra struggles with lower earnings generation and high debt.

The company’s results for the six months ended December 31, 2024, reflect Petra’s progress in implementing cost reduction plans and smoothed capital profiles, despite weakness in the diamond market.

Petra managed to reduce its mining and processing costs from continuing operations by 19% year-on-year to $98-million.

However, the group’s revenue was also lower by 30% year-on-year, or $49-million, at $115-million owing to additional revenue of $50-million having been carried over from tenders into the prior comparable period.

Adjusted earnings before interest, taxes, depreciation and amortisation amounted to $15-million, which was lower than the $38-million adjusted Ebitda reported in the first half of the prior financial year.

The company’s basic loss a share from continuing operations was $0.30, or $0.13 on an adjusted basis.

Operational free cash inflow of $16-million in the six months under review compares with a $21-million outflow in the first half of the prior year, which Petra says largely reflects the impact of its cost reduction measures, capital smoothing and working capital management.

The lower revenue and earnings over the financial year of 2024, caused Petra to not meet its required leverage and interest cover covenant ratios in its revolving credit facility measured at December 31, 2024.

Petra has since obtained a waiver from the lender, Absa Bank, related to these covenant breaches, and is restarting engagements with lenders regarding the refinancing of its debt.

The group’s consolidated net debt was $215-million as at December 31, compared with $193-million at the end of June, owing to diamond market weakness and the timing of Petra’s tender sales.

Three tender sales took place during the first half of the 2025 financial year (the six months ended December 31), while four have been scheduled for the remainder of the financial year.

Petra realised an average price of $103/ct in the reporting period, which reflects the positive impact of product mix over the period offsetting the overall weaker diamond pricing environment.

OPERATIONS

The group has achieved cost reductions through sustainably lowering overheads and on-mine cost optimisation with limited impact to its operations.

Petra completed the sale of its interest in the Koffiefontein mine to the Stargems Group in the six months under review, which allowed the group to avoid closure-related costs of $23-million.

Petra also entered into an agreement in January to sell its interest in the Williamson mine, in Tanzania, to Pink Diamonds Investments for a headline consideration of $16-million.

The group expects the sale of its interest in the Williamson mine to be completed by the end of the calendar year.

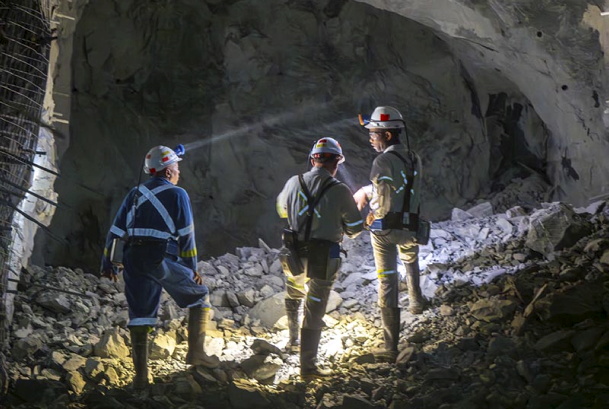
The Finsch mine has transitioned into new production areas called 78-Level Phase 2, with steady operations having been reported over the past few months.

In turn, production from the CC1E zone at the Cullinan mine has also started in the interim period, while Petra continues to advance more extension projects at both of these mines, as well as life-of-mine plan reviews.

Petra intends to re-engage its lenders with a revised business plan and updated cost-savings initiatives, as part of its overall restructuring plan.

The group is targeting net free cashflow generation for the remainder of the financial year, as well as more efforts to make the company resilient to pricing weakness.

Source: DCLA

Tuesday, 29 October 2024

Revenue Slump as Petra Defers Sales

Cullinan Diamond Mine

Petra reported a revenue slump for Q1 2025 after deferring the sale of almost all its South African goods because of persistent weak demand.

The UK-based miner said its only revenue for the quarter ending 30 September was $8.5m for an 18.85-carat blue diamond recovered at Cullinan Mine, South Africa, and $14m for goods from its Williamson mine, in Tanzania.

Total revenue for the quarter, including profit share arrangements, was $23m, down 77 per cent compared to Q1 FY 2024 and 80 per cent compared to Q4 2024.

Petra said its combined tenders 1 and 2, which took place this month, after the end of Q1, brought in $76m.

Average per carat prices were up 13 per cent to $113, compared to the last tender it held, in June. But like-for-like prices were down 9 per cent. Higher prices were due to a better product mix. The company said it had withdrawn 88,000 carats (worth around $3m) of brown goods because of poor demand.

“Our combined first and second tenders indicate continued weakness in the rough diamond market, more than offset by Petra’s product mix,” said CEO Richard Duffy in the Q1 FY 2025 operating update and final sales results for Tenders 1 and 2 FY 2025.

He said Petra was further reviewing cash generation opportunities in the face of ongoing market weakness and a stronger rand.

“We remain committed to our target of net cash generation for the full year in FY 2025,” he said.

“We continue to expect prices to show some improvement in CY 2025, with market fundamentals being supportive in the medium-to-longer term.”

Source: DCLA

Friday, 27 September 2024

Petra Sales Up, Prices Down

Petra Diamonds Operations

Petra Diamonds Operations

Petra Diamonds reported increased sales for FY 2024, despite weak market conditions.

The UK based miner said it had saved $75m by deferring capital expansion programs and sustainably reducing its cost base.

Revenue for the year was $367m, an increase of 13 per cent on FY 2023, according to its Audited Full Year 2024 Results, published on Tuesday (24 September).

“Petra demonstrated its agility in responding to a weaker pricing environment by building greater business resilience,” said CEO Richard Duffy.

“We acknowledge the difficult market conditions through FY 2024 and believe that prices will stabilise through to the end of CY 2024 with some improvement expected in CY 2025.”

Petra sold 3.2m carats of rough during the year an increase of 36 per cent but achieved lower average prices per carat, down 17 per cent to $116, attributable to a 12.4 per cent decline in like for like prices, as well as product mix movements.

Last month Petra today Petra canceled its August/September tender to restrict supply amid ongoing weak demand.

Goods from its Cullinan and Finsch mines, in South Africa, will be sold instead at its next tender, which is expected to close in mid-October.

Source: DCLA

Wednesday, 7 August 2024

Petra defers another diamond tender amid weak demand

Petra Diamonds

Petra Diamonds has once again postponed the sale of roughs, holding on to the diamonds from its South African operations that would have been offered during the August/September event of the year, amid low demand.

The tender of diamonds from Petra’s Williamson mine in Tanzania will proceed as planned, the company said. It noted that this decision aimed to “support steps taken by major producers to restrict supply during this period of weaker demand.”

Rough diamond parcels from the miner’s South African operations, originally earmarked for sale as part of the first tender of fiscal year 2025, are now planned to be offered in the second tender, expected to close mid-October 2024.

Petra will sell diamonds from its Williamson mine in Tanzania during August/September as planned.

Petra’s South African producing operations include the Cullinan and Finsch mines.

“Our expectation is that supply discipline, together with the expected seasonally stronger demand as we head towards the festive season, will provide some pricing support later in the calendar year,” chief executive Richard Duffy said in the statement.

Petra had differed in June the majority of what would have been its sixth sale for its 2024 fiscal year to the August/September offering, or tender one of fiscal 2025.

The company said recent steps taken to improve its financial position have provided it with the ability to adjust the timing of its tenders based on market conditions.

Source: DCLA

Thursday, 18 July 2024

Petra Diamonds focusing on refinancing $250-million loan notes

Petra Diamonds

Having reset its cost base, delivering new life-of-mine (LoM) plans with a smooth capital profile, the focus of Petra Diamonds is very much on refinancing its $250-million loan notes.

“We plan to get that done before the end of this calendar year,” Petra Diamonds CEO Richard Duffy outlined to Mining Weekly in a Zoom interview. (attached Creamer Media video.)

The refinancing of the loan notes will place the London-listed, Africa-active diamond mining company in a position to execute on the growth potential of its long-life assets.

These are Petra’s historic Cullinan diamond mine, located 100 km north-west of Johannesburg, its Finsch diamond mine, which is 160 km north-west of Kimberley, and the Williamson mine, 140 km south-west of Mwanza, in Tanzania.

It will also allow the company to begin to execute on its value-led growth strategy presented by not only its existing asset base, but also through other opportunities.

“We’ll be able to deliver and leverage what we believe will be a much more supported market from next calendar year,” Duffy commented.

The main focus of Petra’s recent investor day was to demonstrate the resilience of the business through steps implemented over the recent months.

The key features were cutting the cost base by $30-million on a sustainable annualised basis.

Through mine replanning, Petra has also smoothed its capital profile going forward basis to around $100-million a year or less.

The main reason is to ensure that the business is cash generative from this financial year (FY) 2025 and to refinance its loan notes, which mature in March 2026.

Mining Weekly: What, specifically, were the LoM updates?

Duffy: In the case of Cullinan mine, we have a board-approved mine plan that goes through to 2033, and the potential through further extensions in the mine itself to be mining beyond 2050. At Finsch mine, we highlighted that the board-approved mine plan sees mining through to 2032 but with the potential to continue mining below the current Block 5 through to 2040. Williamson has an approved mine plan to 2030 with extension opportunities and growth opportunities well into the 2040s. We also provided guidance for the next five years so that we could create some visibility in terms of our production, which we see growing from the current levels of around 2.8-million carats annually to around 3.5-million carats a year by 2028. Most of that growth comes from increasing grade, both at Cullinan and at Finsch.

When you speak of a lower-for-longer diamond market, how does that impact Petra?

What we’re seeing is a diamond market that we expect will continue to remain a little softer through to the end of this calendar year. We took measures towards the end of last year in recognition of what we expected to be a weaker-for-longer market. The steps we took back in October 2023 around deferring some of our capital spend and initiating that cost savings programme meant that we were able to reduce net debt by $11-million from the end of December 2023 to the end of June 2024, the end of our FY 2024. The measures taken ensured that we stopped any cash burn in the business, even in a tougher market. The steps we’ve taken around costs and smooth capital profile mean that we’ll continue to be resilient as a business, and be cash generative from this financial year 2025 onwards. So, we’re well placed to benefit from an improving market, which we expect to see from next calendar year.

What makes you more confident about the market in the medium- to long-term?

What we’ve seen in the market is the culmination of a number of factors that have created some headwinds for us, and that really has been on the back of the higher interest and inflation rates that have been a little more stubborn than expected, the slower return of demand from China, which is an important market for diamonds, and the disruption caused by the rapid growth of lab-grown diamonds. Those were the factors that led to the softer market, which we expect to continue through to the end of December. Why we’re more encouraged in the medium to longer term about what we expect to be a supportive diamond market is around some of the underlying supply-demand fundamentals. If you look at projected supply, or global production of diamonds, all the way through to 2033, the projections are that we’ll see an average 1% decline on an annual basis over that period. When you look at the demand side, there’s projected growth to 2033, of 2% to 4%, so from a fundamental supply-demand perspective, there’s a structural supply deficit. The US buys around 50% of all diamonds, and the projections are that US demand will continue to grow through to 2033. Interestingly, China isn’t projected to grow at the same rate as the US, but India is emerging as a very strong consumer, with 30% growth forecast through to 2033. We see India and its growing middle class as a new, increasingly important market for diamonds that is likely to overtake China.

How are natural diamonds faring against laboratory-grown diamonds?

If you look at lab-grown diamonds, the disruption they caused initially was largely the result of consumers not properly understanding this new lab-grown diamond category. Over the last few years, we’ve seen the price of lab-growns collapse to now sell at a discount of 80% to 90% of a natural diamond. As a result, lab-growns are now firmly established as a different product category in the diamond space. They’re a cheap early entry point and that differentiation will become more discernible and clearer over time. Also, importantly, retailers, jewellers are shifting back to natural simply because the price of lab-grown has collapsed. The margins have collapsed, and it doesn’t make economic sense for them to continue to push lab-growns. We see, in a sense, some reversal of the displacement of lab-grown that we saw previously, in favour of natural diamonds. Another important point is a number of lab-grown producers have stated that they’re moving out of producing gem lab-grown diamonds, and they’re shifting their lab-grown production to industrial applications, around semiconductors, etc. This is led by De Beers’ Lightbox business, where they’ve indicated they’re no longer going to be producing gem lab-grown diamonds, and the same is true of a number of other large lab-grown producers. For all of those reasons, we see inventory levels starting to come down across that value chain going into next year, a shift away from lab-grown back to natural, and the general economics starting to shift in favour of diamonds with the structural supply deficit providing the support.

How do you see traceability unfolding?

We see traceability technology as being part of the differentiation between lab-grown and natural diamonds. What this technology allows us to do, and we’re busy piloting this at the moment, in collaboration with De Beers’ Tracr™ and Sarine Diamond Journey™ technology, is to map all of our half-a-carat gem-quality diamonds, and half-a-carat in the rough and larger. The data around a diamond gets block-chained in a register, and we then trace that diamond through the cutting and polishing. Our clients link the polished diamonds back to the original rough, and that enables traceability all the way through to the retail jeweller – essentially from mine-to-finger. For a consumer who then walks into a jewellery store in New York to buy a one-carat engagement ring, there would be a certificate associated with that, stating that the diamond was recovered from, for example, Cullinan mine in 2020. It would set up the number of employees that the Cullinan mine employs, provide details on all of the social and community projects undertaken by the mine, and include the carbon footprint associated with that polished diamond. So, there’s a whole story around the diamond that reinforces that purchase experience for the consumer, creating an opportunity to grow margin as part of that story, around the mine-to-finger journey.

DIAMOND VERACITY

The traceability that Petra expects to implement during the course of this calendar year will enable it to clearly verify that the diamonds:

are from a Petra mine;
are natural and not lab-grown; and
are not subject to any sanctions.
The application of Tracr™ means that the diamonds from these mines will be subjected to the Internet of Things, AI and blockchain technology to provide comprehensive supply transparency.

In addition, the application of Sarine Diamond Journey™ begins with three-dimensional scanning to establish a verifiable image of the physical diamond and a definitive link to its digital report.

This enables the creation of an unbroken chain of authentication at every stage of the diamond’s journey – from rough to rough, rough to polished, polished to report.

Securely stored in the cloud, this data provides the foundation of end-to-end traceability.

Source: DCLA

A Rare 24 Carat Diamond Set to Make Auction History

  A remarkable pink diamond, hidden from public view for more than 70 years, is preparing to take centre stage at Christie’s Magnificent Jew...