Showing posts with label De Beers Cullinan Blue Diamond. Show all posts

Friday, 2 October 2026

Petra Diamonds Weighs Sale as Diamond-Market Pressures Mount

 Strategic review highlights the financial pressure facing one of Africa’s best-known natural diamond producers

Strategic review highlights the financial pressure facing one of Africa’s best-known natural diamond producers

Petra Diamonds has launched a strategic review that could ultimately lead to the sale of some or all of its assets, as the company faces continuing liquidity pressures, weak natural diamond prices and significant operational challenges at its Finsch mine in South Africa.

The London-listed diamond producer announced on 1 October that, following discussions with key stakeholders including its first and second lien creditors, it would examine all available options for addressing its near-term liquidity requirements. These options include a potential sales process involving the company’s assets. Petra is also in the process of appointing a financial adviser to assist with the review.

At the same time, José Manuel Vargas stepped down as chairman and a director of the company. Lerato Molebatsi has been appointed interim chair.

The developments are significant because Petra is not simply another diamond producer. Over almost three decades, the company has built a portfolio around some of the world’s most historically important diamond mines.

From junior explorer to major diamond producer

Petra Diamonds was first admitted to trading on London’s AIM market in April 1997 with a market capitalisation of approximately £8.75 million. It subsequently moved to the Main Market of the London Stock Exchange in December 2011.

The company’s growth was driven in large part by acquiring diamond assets that were considered non-core by larger mining groups, including De Beers.

Among its most important acquisitions was the Cullinan Mine in South Africa, acquired by Petra in stages from 2008. In 2011, Petra acquired a majority interest in Finsch, one of South Africa’s most significant diamond mines.

Petra subsequently became associated with an extraordinary collection of diamond-producing assets and some remarkable stones.

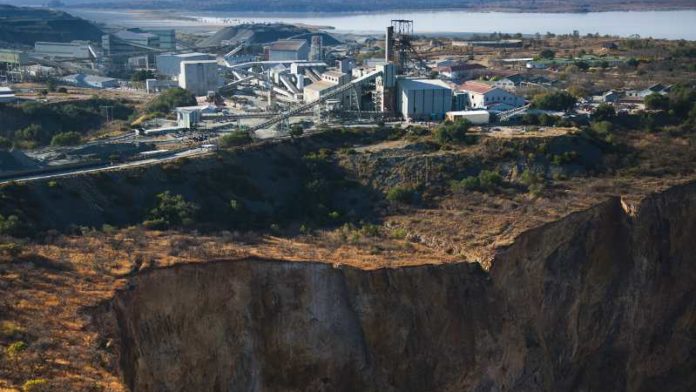
The Cullinan Mine is perhaps the most famous. Originally known as the Premier Mine, it produced the 3,106-carat Cullinan diamond, the largest gem-quality rough diamond ever discovered. The stone was ultimately cut into several important diamonds, including the Great Star of Africa and the Second Star of Africa, both of which form part of the British Crown Jewels.

Cullinan has also produced some of the world’s most notable blue diamonds, including a Type IIb blue diamond that Petra sold in 2021 for US$40.2 million, equivalent to more than US$1 million per carat.

Finsch has its own remarkable history. The mine has been operating since 1967 and is known for producing commercial-quality diamonds, including larger stones above five carats, as well as occasional exceptional diamonds exceeding 50 carats. Petra has operated the mine since 2011.

Petra’s history also includes the Williamson mine in Tanzania, famous for the Williamson Pink, a 54-carat rough pink diamond discovered in 1947. The polished stone became a gift to Princess Elizabeth, later Queen Elizabeth II. Petra sold its interest in Williamson in 2025 as part of its strategy to streamline its portfolio.

Finsch becomes a major pressure point

The immediate financial problem, however, is centred on Finsch.

The mine entered business rescue in May 2026 and production was subsequently suspended. Petra has said that, despite strong operating performance, the mine’s high proportion of smaller diamonds, combined with the strength of the South African rand and exceptionally difficult market conditions, made the operation economically unsustainable in its existing form.

Petra reported consolidated net debt of approximately US$322 million at 30 June 2026, compared with US$298 million three months earlier. The company said its cash position had become increasingly constrained by weaker diamond prices and the ring-fencing of cash associated with the Finsch business-rescue process.

The company has already secured additional short-term working capital support from its senior lender, including a R300 million facility, while discussions around a broader refinancing have continued.

The latest strategic review therefore represents a further step in Petra’s efforts to protect liquidity and determine how its remaining assets can be structured for the future.

The wider natural diamond squeeze

Petra’s difficulties should also be viewed within the much broader disruption experienced by the natural diamond industry.

Diamond producers, manufacturers, wholesalers and retailers have faced a combination of weaker consumer demand, economic uncertainty, excess inventory, changing purchasing patterns and increased competition from laboratory-grown diamonds.

The result has been substantial pressure on rough diamond prices and on the economics of mining.

Petra’s own history illustrates the dramatic change in the industry. The company produced more than 4.6 million carats in 2018, whereas its current portfolio is considerably smaller following the disposal of several assets.

The company has also undertaken cost reductions, portfolio rationalisation and debt restructuring in an effort to adapt to the new market environment.

For the natural diamond industry, however, there is an important distinction between falling production and falling demand.

A natural diamond supply reset?

Global diamond production has been falling sharply as producers respond to weaker economics. Industry analyst Paul Zimnisky has pointed to the possibility that declining mine supply could eventually help rebalance the market.

Lower production may gradually remove some of the excess supply that has weighed on rough diamond prices. But that does not guarantee an immediate recovery. The industry still needs sustainable consumer demand, healthy inventories and prices that allow mines to operate profitably.

For companies such as Petra, the timing is critical.

A reduction in global mine supply could ultimately provide support for natural diamond prices, but producers carrying substantial debt cannot necessarily wait indefinitely for a future market recovery.

The changing diamond landscape

The difficulties facing Petra also highlight an important reality about diamonds: a diamond mine is a finite natural resource, and maintaining production is extraordinarily capital intensive.

Laboratory-grown diamonds have introduced another layer of competition into the lower and middle sections of the jewellery market. Unlike natural diamonds, laboratory-grown stones can be manufactured in virtually unlimited quantities, meaning their economics are fundamentally different from a scarce geological resource that can take billions of years to form.

This distinction is increasingly important when considering the long-term value proposition of natural diamonds.

Natural diamonds are not simply manufactured products. They are geological rarities, with their supply ultimately constrained by the number of economically viable deposits that exist on Earth.

The challenge for the natural diamond industry is therefore not simply producing diamonds. It is maintaining a balance between scarcity, consumer demand, mine economics and market confidence.

What happens next?

Petra’s strategic review does not mean that a sale will necessarily occur. The company has said that all potential avenues for addressing its liquidity requirements are being considered, with any outcome dependent on the review and discussions with stakeholders.

Possible outcomes could include asset transactions, further financing, restructuring or a broader corporate transaction.

Whatever the eventual outcome, Petra’s situation is a reminder of how dramatically the natural diamond industry has changed.

A company that grew from a small junior explorer in 1997 into the owner and operator of some of the world’s most celebrated diamond assets is now having to reconsider its structure in response to one of the most challenging periods the modern diamond industry has experienced.

For DCLA, the story also reinforces an important point: the rarity and provenance of a natural diamond remain fundamental to understanding what makes exceptional diamonds different from mass-produced alternatives.

From the Cullinan diamond and historic blue diamonds to the Williamson Pink and the exceptional stones recovered at Finsch, Petra’s history is intertwined with some of the most important diamonds ever discovered.

The question now is whether the next chapter of that history will be written under Petra’s ownership — or by a new generation of owners.

Monday, 7 September 2026

The Infinite Blue: The Extraordinary Story Behind a $25 Million Blue Diamond

 Rare blue diamond from South Africa’s Cullinan Mine demonstrates why colour, origin and rarity can transform a diamond into a global treasure

Rare blue diamond from South Africa’s Cullinan Mine demonstrates why colour, origin and rarity can transform a diamond into a global treasure

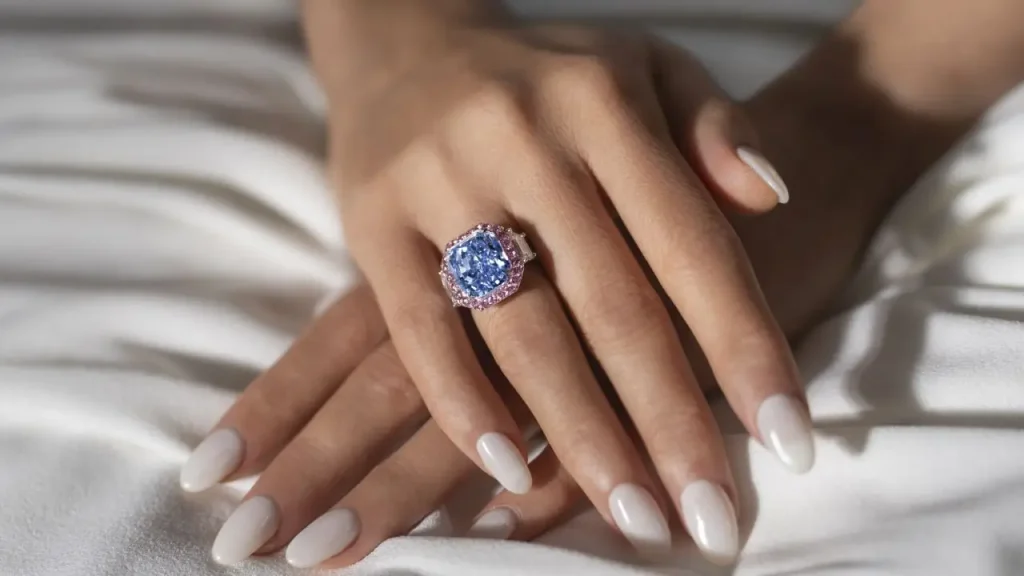
Few diamonds capture the imagination quite like a natural Fancy Vivid blue diamond. In 2023, one of the most remarkable examples in recent years the 11.28-carat Infinite Blue attracted worldwide attention when Sotheby’s Hong Kong offered it as a single-lot auction.

The diamond carried an ambitious pre-sale estimate of US$26 million to US$37 million, reflecting its extraordinary colour, size, provenance and rarity. However, the final result demonstrated just how unpredictable the market for exceptional coloured diamonds can be: the Infinite Blue sold for approximately US$25.3 million, below its low estimate.

A diamond born at the Cullinan Mine

The Infinite Blue has an exceptional pedigree.

Its rough origin was the famous Cullinan Mine in South Africa, operated by Petra Diamonds. Cullinan is internationally recognised as one of the world’s most important sources of natural blue diamonds and has produced some of the most celebrated diamonds ever offered at auction.

The Infinite Blue was cut from a 25.75-carat rough blue diamond, the largest stone in Petra’s Letlapa Tala collection. That collection itself was sold by Petra in 2020, and the rough was subsequently transformed into the polished 11.28-carat gem.

The transformation from rough to polished diamond illustrates one of the fundamental challenges of exceptional coloured diamonds: cutters must balance weight retention with the optimisation of colour, brilliance, proportions and overall appearance.

Why is a blue diamond so rare?

Blue diamonds occupy a very special position in the world of natural diamonds.

Unlike most colourless diamonds, where nitrogen is an important factor in colour, the blue colour in natural Type IIb diamonds is associated with the presence of boron within the diamond’s crystal structure.

The Infinite Blue is classified as a Type IIb diamond, a category representing an exceptionally small proportion of natural diamonds. Petra describes Type IIb diamonds as among the rarest stones recovered from the Cullinan Mine.

Its Fancy Vivid Blue colour grade is equally significant. In the world of coloured diamonds, the intensity and distribution of colour can have an enormous influence on value.

This is why two diamonds of similar size can have dramatically different market values.

The significance of 11.28 carats

There is also a deliberate piece of symbolism in the Infinite Blue’s final weight.

The diamond weighs 11.28 carats, with the number eight incorporated into its final carat weight. Eight is widely regarded as an auspicious number in Chinese and other Asian cultures, where it is associated with prosperity and good fortune.

There is another connection: when the number eight is turned on its side, it resembles the mathematical symbol for infinity.

That symbolism inspired the name Infinite Blue and added an element of cultural meaning to an already extraordinary gemstone.

What makes the Infinite Blue different?

According to published gemological information, the diamond is a Fancy Vivid Blue, VS2-clarity, radiant-cut diamond. Its combination of colour, size and natural origin puts it into an exceptionally small group of diamonds.

The distinction between colour grade and clarity is particularly important when assessing coloured diamonds.

With colourless diamonds, clarity can have a major influence on value. With strongly coloured diamonds, however, colour intensity, hue, saturation and distribution can be fundamental drivers of rarity and price.

This is one reason coloured diamonds require specialised knowledge when they are being evaluated.

Joining an extraordinary group

The Infinite Blue also belongs to a remarkable family of large blue diamonds associated with the Cullinan Mine.

The mine has produced several diamonds that have achieved extraordinary prices at international auctions.

Among them are:

  • The Oppenheimer Blue — 14.62 carats, sold for approximately US$57.5 million in 2016.
  • The De Beers Blue — 15.10 carats, sold for approximately US$57.5 million in 2022.
  • The Infinite Blue — 11.28 carats, sold for approximately US$25.3 million in 2023.

Another famous Cullinan blue diamond, the Blue Moon of Josephine, weighs 12.03 carats and achieved US$48.5 million at auction in 2015.

These stones demonstrate an important fact about the diamond market: rarity does not automatically translate into a predictable price.

Auction values depend on a combination of factors including colour, clarity, size, cut, provenance, market conditions, collector demand and the circumstances of the sale.

A lesson in diamond valuation

The Infinite Blue is an excellent example of why a diamond’s value cannot be determined simply by multiplying carat weight by a price per carat.

A natural Fancy Vivid blue diamond of more than 10 carats belongs to an entirely different market from an ordinary commercial diamond.

Its value is influenced by a complex combination of:

Natural origin + colour + intensity + size + clarity + cut + provenance + rarity + market demand.

For consumers and collectors, this reinforces the importance of independent gemological assessment and accurate documentation when dealing with significant diamonds.

Nature creates the rarity — expertise reveals it

The Infinite Blue ultimately sold for less than its original estimate, but the auction result did little to diminish the gemological importance of the stone.

What makes diamonds such as the Infinite Blue fascinating is that their story begins millions and often billions of years before they ever reach an auction room.

A combination of geological conditions, trace elements, crystal structure and extraordinary rarity created the blue colour. Human expertise then transformed an unusual piece of rough into a polished gemstone capable of commanding more than US$25 million.

For the diamond industry, stones such as the Infinite Blue provide an important reminder that the true value of a rare diamond lies not simply in its size, but in the combination of characteristics that make that particular stone unique.

At DCLA, we believe that understanding those characteristics is fundamental to understanding diamonds themselves.

Wednesday, 8 July 2026

De Beers Slashes Diamond Prices and Reshapes Its Elite Buyer Network


The global diamond industry may have reached a major turning point.

De Beers has implemented some of the largest official rough diamond price reductions in its modern history while simultaneously removing almost one-third of its exclusive group of authorised buyers. The move represents a dramatic shift in strategy after years of attempting to keep official prices well above prevailing market levels.

For the diamond trade, manufacturers and retailers, this is more than simply a pricing adjustment it is a clear acknowledgement that market forces can no longer be ignored.

Official Prices Finally Catch Up With Reality

For much of the past three years, De Beers resisted cutting its published rough diamond prices despite a sharp fall in global demand.

Instead, the company quietly sold selected goods through confidential discounted transactions while maintaining higher official prices to preserve confidence throughout the industry.

That approach has now come to an end.

During its July 2026 sales cycle, De Beers made sweeping reductions across nearly every category of rough diamonds. Industry sources indicate that some categories had previously been priced between 5% and 50% above equivalent goods trading in the secondary market.

The latest reductions bring De Beers’ official pricing much closer to actual market values.

Although the company has declined to comment publicly on the exact reductions, the changes are widely regarded as some of the deepest official price cuts ever made by the company.

Understanding the Sightholder System

To appreciate why these price cuts are so significant, it is important to understand how De Beers sells its diamonds.

Unlike many commodities, rough diamonds are not sold on open exchanges.

Instead, De Beers operates through its long-established Sightholder System, a carefully selected network of approved companies invited to purchase rough diamonds directly from the miner.

These companies attend ten scheduled “sights” each year.

At each sight, buyers are offered parcels or “boxes” of rough diamonds at fixed prices determined by De Beers. There is generally little or no room for negotiation. Buyers may accept or decline the allocation, but historically repeated refusals risked losing their coveted sightholder status.

For decades, this system allowed De Beers to exercise remarkable control over the supply of rough diamonds entering the global manufacturing pipeline.

By carefully managing both supply and pricing, the company was able to influence the broader diamond market more effectively than almost any other mining company.

Fewer Buyers, Greater Concentration

The July 2026 sight is also the first held under newly negotiated supply agreements.

Perhaps the biggest structural change is the reduction in De Beers’ exclusive buyer network.

The number of authorised sightholders has been reduced from around 70 companies to approximately 45–50.

The objective is straightforward.

De Beers wants a smaller group of financially stronger customers capable of purchasing larger volumes while maintaining long-term commitments to the business.

The company believes concentrating sales among its strongest clients should reduce the number of diamonds being immediately resold into secondary markets, where discounted trading has undermined official pricing for several years.

In theory, fewer buyers should allow De Beers to exercise tighter control over the distribution of rough diamonds.

However, the strategy also carries greater risk.

With fewer customers, De Beers becomes increasingly dependent upon the financial health of each remaining sightholder. Should several major buyers reduce purchases or encounter financial difficulties, there are fewer alternative customers available to absorb production.

Why Is De Beers Changing Strategy?

The decision reflects several years of mounting pressure across the global diamond industry.

China, once one of the world’s fastest-growing luxury jewellery markets, has experienced a significant slowdown in consumer spending. Demand for diamond jewellery has weakened substantially, removing one of the industry’s largest growth engines.

At the same time, laboratory-grown diamonds have become increasingly popular, particularly in the bridal jewellery sector, where consumers can purchase much larger stones at a fraction of the price of natural diamonds.

The market has also faced increased competition from additional rough diamond supply entering global markets from countries including Angola.

Adding further uncertainty have been ongoing geopolitical tensions, US trade tariffs and slowing global economic growth, all of which have reduced consumer confidence in luxury spending.

Together, these factors have produced one of the deepest and longest downturns the diamond industry has experienced in decades.

Less Transparency Than Before

Ironically, while prices have become more market-driven, pricing transparency has actually decreased.

Earlier this year De Beers introduced a new “one-line invoicing” system.

Rather than providing detailed prices for each category of rough diamonds within a parcel, buyers now receive a single combined total for the entire box.

At the same time, the company has altered the composition of many assortments.

These changes make it difficult for manufacturers and market analysts to determine exactly how much individual categories of diamonds have increased or decreased in value.

This reduced transparency makes independent price analysis significantly more challenging than under the previous system.

A Business Preparing for Sale

The pricing changes also arrive during a crucial period for parent company Anglo American.

Since May 2024, Anglo American has been working to divest De Beers as part of a broader restructuring programme following years of declining profitability.

Potential buyers continue to evaluate the world’s most famous diamond producer while the company attempts to stabilise earnings and restore confidence throughout the market.

Resetting prices closer to genuine market levels may ultimately make De Beers a more commercially attractive business by reducing the disconnect between official pricing and actual trading conditions.

What It Means for the Diamond Industry

De Beers’ latest decisions signal more than a temporary response to weak trading conditions.

They represent a recognition that the natural diamond market has fundamentally changed.

The company appears to be abandoning a long-standing strategy of defending premium pricing in favour of allowing market realities to shape official valuations.

Whether these changes successfully restore confidence remains to be seen.

For manufacturers, wholesalers and retailers, pricing that more accurately reflects real market conditions may improve margins and encourage renewed trading activity.

For consumers, however, the changes are unlikely to produce dramatic retail price reductions in the short term, as jewellery prices are influenced by manufacturing costs, branding, retail margins and consumer demand as much as the price of rough diamonds themselves.

What is clear is that De Beers has entered a new chapter one where flexibility, commercial realism and supply discipline are becoming more important than maintaining the appearance of price stability.

Disclaimer: This article is provided for general information and industry commentary only. It does not constitute financial, investment or professional advice. Market conditions, diamond prices and industry developments may change without notice. Readers should undertake their own research or seek independent professional advice before making any commercial or investment decisions.

Source: DCLA

Tuesday, 13 January 2026

De Beer’s 1873 Diamond, Still in Kimberlite

 De Beer's 1873 Diamond Still in Kimberlite

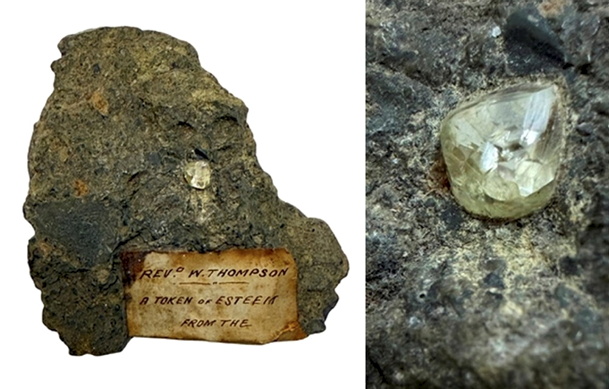
An extremely rare relic from the earliest years of the Kimberley diamond rush – a rough stone, still embedded in kimberlite – sold at auction in London for £10,500 ($14,000).

It dates back to the New Rush at Colesberg Kopje (now better known as the Kimberley mine), in South Africa that began when diamonds were first discovered there in 1871.

Furlong Auction House, at the London Diamond Bourse, in Hatton Garden, included it in a collection of “rare and highly desirable items across jewellery history” in its Collectables & Memorabilia auction on 8 January.

“This hand specimen of kimberlite (“blue ground”) contains a visible natural diamond crystal embedded in the matrix and retains its original manuscript presentation label dated May 23rd, 1873,” it said in the lot notes.

“The handwritten note – both on the specimen itself and on a later transcribed slip – reads: “Rev’d W. Thompson – A token of esteem from the Cong’l Church, De Beers New Rush, May 23, 1873. M.M.S., Sec’y.”

It said surviving labelled geological specimens from this period – especially with an exposed diamond crystal – were exceptionally scarce.

Source: DCLA

Friday, 31 October 2025

De Beers Rough Sales Triple in Q3

De Beers sold $700m worth of rough diamonds

De Beers sold $700m worth of rough diamonds across its two sights in the three months to 30 September – more than tripling the $213m recorded during the same period last year.

In the third quarter of 2024, the company held only one sight, having cancelled the August session due to weak demand.

During the Q3 2025 sights, specific assortments were offered at discounted prices. De Beers no longer provides sight by sight updates.

It noted that trading conditions “continued to be challenging,” although consumer demand for natural diamond jewelry remained broadly stable, particularly in the US.

The company said progress seen in the first half of 2025 was hindered by newly imposed US tariffs on diamond imports from India, according to its production report published on 28 October.

However, it welcomed the recent exemption granted for natural diamond imports from countries participating in “aligned partner” trade agreements, announced last month.

Meanwhile, quarterly production increased year-on-year by 38 per cent, to 7.7m carats, although it is down 5 per cent for the year to date (17.9m carats).

Production guidance for 2025 is unchanged at 20 to 23m carats.

Source: IDEX

Tuesday, 12 August 2025

Petra to Refinance as Sales Slide by a Third

Petra Diamonds - Cullinan Diamond Mine

Petra Diamonds has announced plans for a major refinancing program – together with a 33 per cent slide in revenue for FY2025.

The UK-based miner, which has recently sold off two of its four diamond mines, is facing substantial financial and operational challenges.

It is proposing an extension of senior secured bank debt and notes due early next year to 2029 and 2030 respectively, together with a $25m rights issue.

The moves are designed to preserve cash, extend debt repayment timelines, and ensure Petra can continue investing in its two remaining core mines – Cullinan and Finsch, both in South Africa.

Petra’s latest sales results, published on the same day (8 August) as its refinancing package, show some positive momentum in the market with like-for-like rough diamond prices from its latest tender, but revenue for Q4 was down 49 per cent year-on-year to $50m.

Revenue for FY2025 was $206m, down 33 per cent year-on-year from $309m and net debt increased to $264m.

“We would once again like to acknowledge the resilience shown by our employees in navigating a very difficult period for the company and the diamond sector as whole,” the company said in its Q4 and FY 2025 Operating Update.

Meanwhile, in its refinancing proposal Petra said: “Petra has, over the past 18 months, been focused on an internal restructuring that has resulted in a simpler and more streamlined business and operating model.

“This has included the sale of the Koffiefontein and Williamson mines, multiple labour restructuring initiatives and an optimisation and smoothing of the group’s capital development profiles.”

Source: DCLA

Friday, 23 May 2025

Petra Diamonds hits all-time low as cash burn continues

Petra's Cullinan mine

Petra Diamonds is to begin discussions with financiers on refinancing a $273m bond that matures in March next year amid scepticism that the company will survive the event.

The ratings agency S&P last week downgraded the company’s credit to CCC on the increased likelihood of default, and maintained a negative outlook.

Shares in the company fell 10% today shortly after the company posted its third quarter results. Petra is now trading at a fresh all-time low and is valued at only £34m on the London Stock Exchange.

While its remaining two assets – the Cullinan and Finsch mines in South Africa – had a solid three months operationally, with a quarter to go, full year guidance has been maintained at 2.4 to 2.7 million carats.

However, the company is still burning cash.

Petra drew on a further $33m as consolidated net debt increased to $258m as of end-March, which the company put down to working capital requirements.

The truth is that the company is desperately in need of improved diamond prices, which have continued to trough this year amid economic uncertainty generated by US President Donald Trump’s on-off tariff regime.

Petra said in April that it had postponed the sale of about 200,000 carats of diamonds from the Cullinan mine near Pretoria because of the “considerable diamond market uncertainty caused by the US tariffs announcement”.

“S&P believes the company faces mounting liquidity challenges amid uncertainty regarding the recovery of the rough diamond market and approaching debt maturities in 2026, with increased likelihood of default – including distressed exchange or debt restructuring – over the next 12 months, if Petra is unable to refinance its debt maturities on time,” said analysts at Berenberg Bank in a note last week.

Commenting on the third quarter results – in which revenue fell to $42m from $106m in the comparative quarter last year (buoyed by sales from a deferred tender) – interim joint CEOs Vivek Gadodia and Juan Kemp, said Petra had experienced “a very difficult diamond market”.

They added: “We believe the steps we have taken over the past 12 months position Petra well for a successful refinancing. We will now look to commence engagements with our lenders on the refinancing of our debt maturing in early 2026.”

Source:miningmx.com

Monday, 24 February 2025

Anglo American writes down value of diamond firm De Beers by $2.9bn

Sale of De Beers, which is now valued at $4bn, may be delayed following ‘really, really difficult’ market

The world’s biggest diamond miner, De Beers, cost its parent company almost $3bn last year as the growth in lab-grown stones continues to take the shine off the industry.

Anglo American was forced to write down the value of the renowned gem producer for a second consecutive year as its chief executive admitted the diamond markets had proved “really, really difficult for the company”.

Duncan Wanblad, the chief executive of Anglo American, added that its plan to shrug off De Beers as part of a radical strategy to dismantle parts of the 108-year-old group – which coined the slogan “a diamond is forever” in 1947 – may be delayed.

He added that the FTSE 100 company did not expect “much traction or progress” on its plans to spin off De Beers in the first half of the year, which could be via a trade sale or a listing via an IPO or demerger, but it might “pick up” towards the end of the year.

Diamond prices have slumped over the past decade because of the rising popularity of cheaper, lab-grown versions and a slowdown in consumer spending in China.

In response, Anglo has taken impairments of $2.9bn on De Beers last year, after a $1.6bn writedown of the company in its annual results last year. This drove Anglo to a $3.1bn net loss in 2024, from a $283m profit the previous year.

The latest writedown of De Beers, which once controlled 90% of the world’s diamond market, means the company is now valued at $4bn.

Anglo laid bare the ongoing losses at De Beers after setting out a plan last year to sell the diamond business as part of a historic corporate overhaul to defend the company against a £34bn takeover plot by the Australian miner BHP.

Anglo hopes to guard the company against further unsolicited advances from BHP, which attempted to force the board to offload two Johannesburg-listed subsidiaries, the platinum miner Amplats and the iron ore miner Kumba, in order to complete a takeover.

Wanblad said the company had received unsolicited interest in the diamond business but a formal process had not started. At least part of the company is expected to be purchased by the government of Botswana, which hosts many of the company’s diamond mines.

Source: Theguardiam

Tuesday, 12 November 2024

De Beers Finds High-Potential Kimberlite Sites in Angola

De Beers shows Al Cook, CEO, De Beers Group (left) and Ganga Junior, CEO of Endiama signing the MoU.

De Beers says it has identified eight new high-potential kimberlite sites in Angola, according to the Portuguese news agency Lusa.

It resumed explorations in the country in 2022, after a 10-year gap, and signed a memorandum of understanding (MoU) in February with Angola’s National Mineral Resource Agency, and its state-owned mining and trading companies, Endiama and Sodiam.

Aerial surveys by De Beers have so far identified eight sites in Lunda Sul, the northeastern province that is home to the huge Catoca mine. De Beers is now exploring six more areas, together with Endiama.

Angola has yet to explore 60 per cent of its diamond-rich territories. It opened its new Luele diamond mine last November, in a move that is forecast to increase annual production from 9.7m carats in 2023 to 14.6m carats this year.

Under the terms of the MoU there will be a review of kimberlite deposits to be explored and the transparency and traceability of diamond production will be promoted.

Source: IDEX

Tuesday, 29 October 2024

Revenue Slump as Petra Defers Sales

Cullinan Diamond Mine

Petra reported a revenue slump for Q1 2025 after deferring the sale of almost all its South African goods because of persistent weak demand.

The UK-based miner said its only revenue for the quarter ending 30 September was $8.5m for an 18.85-carat blue diamond recovered at Cullinan Mine, South Africa, and $14m for goods from its Williamson mine, in Tanzania.

Total revenue for the quarter, including profit share arrangements, was $23m, down 77 per cent compared to Q1 FY 2024 and 80 per cent compared to Q4 2024.

Petra said its combined tenders 1 and 2, which took place this month, after the end of Q1, brought in $76m.

Average per carat prices were up 13 per cent to $113, compared to the last tender it held, in June. But like-for-like prices were down 9 per cent. Higher prices were due to a better product mix. The company said it had withdrawn 88,000 carats (worth around $3m) of brown goods because of poor demand.

“Our combined first and second tenders indicate continued weakness in the rough diamond market, more than offset by Petra’s product mix,” said CEO Richard Duffy in the Q1 FY 2025 operating update and final sales results for Tenders 1 and 2 FY 2025.

He said Petra was further reviewing cash generation opportunities in the face of ongoing market weakness and a stronger rand.

“We remain committed to our target of net cash generation for the full year in FY 2025,” he said.

“We continue to expect prices to show some improvement in CY 2025, with market fundamentals being supportive in the medium-to-longer term.”

Source: DCLA

The Perfect Diamond Without Compromise

  Your dream diamond should never be limited by your budget. At DCLA , expertise, craftsmanship and personal service come together to help y...