Showing posts with label botswana. Show all posts

Monday, 14 September 2026

Where Did My Diamond Come From?

 How can you prove the provenance of a polished diamond?

How can you prove the provenance of a polished diamond?

When buying a natural diamond, one question is becoming increasingly important:

Where did it come from?

A diamond may have been mined in Botswana, South Africa, Canada, Australia, Angola, Namibia, Lesotho, Russia or one of the many other diamond-producing regions around the world. But once that rough diamond has been cut and polished, can a laboratory actually look at the finished stone and determine which mine it came from?

For the vast majority of polished diamonds, the answer is no.

This is an important distinction between identifying what a diamond is and identifying where it came from.

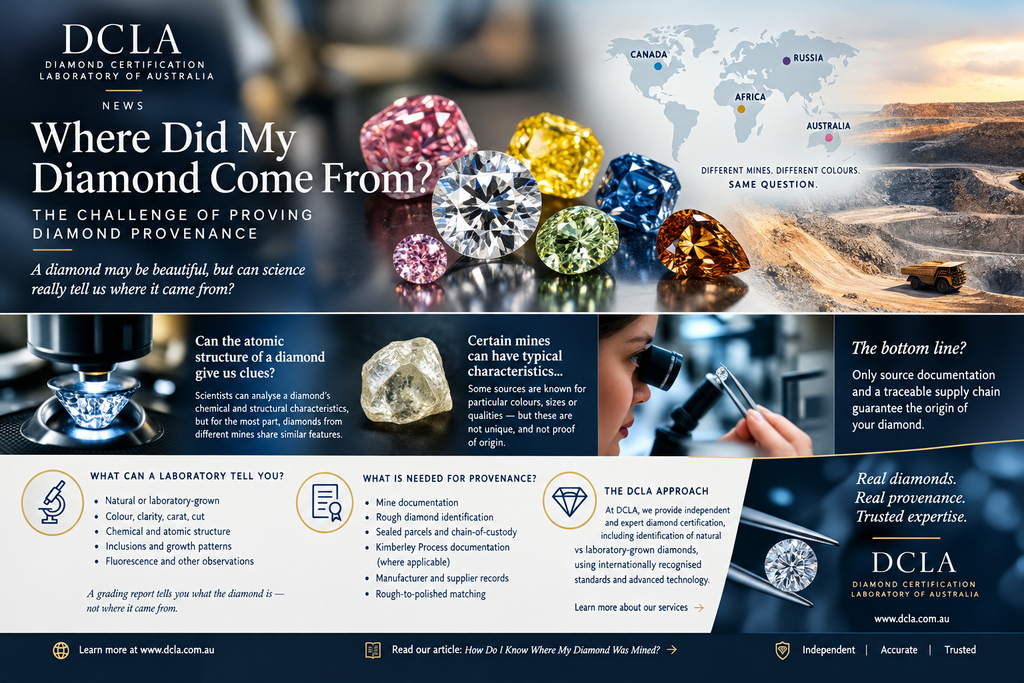
A gemmological laboratory can examine a polished diamond and determine many things about it, including its natural or laboratory-grown origin, colour, clarity, carat weight and other characteristics. But determining the geographic origin of a natural diamond is a very different scientific problem.

DCLA has previously addressed the difficulty of determining where a diamond was mined and the importance of documentation and traceability. DCLA: How Do I Know Where My Diamond Was Mined?

Can the atomic structure of a diamond reveal its mine?

This is where the science becomes particularly interesting.

A diamond is made primarily from carbon atoms arranged in a highly organised crystal structure. Small amounts of nitrogen, boron and other trace elements can also occur within the crystal.

Scientists can examine characteristics such as:

  • Crystal structure
  • Nitrogen characteristics
  • Trace elements
  • Isotopic composition
  • Inclusions
  • Growth patterns
  • Spectroscopic characteristics
  • Fluorescence and luminescence

These characteristics can sometimes provide clues.

The problem is that diamonds from different mines can share remarkably similar geological and chemical characteristics.

Research published by the Gemological Institute of America has found that diamond characteristics overlap extensively between deposits around the world. There is currently no scientifically robust method that can independently determine the geographic origin of a random individual polished diamond simply by analysing the stone.

In other words, the atomic structure can tell scientists a great deal about a diamond but for most polished diamonds, it cannot provide a unique geographic fingerprint saying, for example, “this diamond came from Mine X.”

Diamonds from particular mines can have characteristics but that is not proof

This does not mean that diamonds from particular mines are completely indistinguishable.

Certain mines and deposits can become associated with particular characteristics.

For example, some sources have become famous for producing particular sizes, qualities or colours of diamonds. The Argyle mine in Australia became particularly associated with pink and other rare coloured diamonds, while the Cullinan mine in South Africa became famous for producing exceptionally large, high-quality diamonds.

However, these associations are not the same thing as scientific proof of origin.

A diamond may display characteristics that are more common in diamonds from a particular locality without those characteristics being exclusive to that locality.

As GIA research explains, experienced professionals may sometimes make an educated assessment of the likely origin of certain rough diamonds or parcels. But for the majority of polished diamonds, there are no distinctive characteristics that independently reveal their geographic origin.

This distinction is particularly important when a diamond is being marketed with a premium based on its supposed geographical origin.

“This diamond looks like it could have come from that mine” is not the same as “this diamond has been proven to have come from that mine.”

What happens when the diamond is polished?

The journey from rough to polished is critical.

A rough diamond can contain information that is lost or altered when it is cut and polished. Surface characteristics disappear, inclusions may be removed or avoided during cutting, and the original crystal shape is transformed into a finished gemstone.

This makes retrospective identification extremely difficult.

GIA’s research describes the problem clearly: the characteristics of diamonds from different geological environments overlap, while gem-quality diamonds contain extremely low concentrations of many trace elements. The research concludes that, at present, reliable diamond provenance depends on retaining origin information from the time of mining rather than attempting to determine the origin analytically after the fact.

So how can the origin of a polished diamond actually be proven?

The answer is traceability.

Instead of trying to work backwards from the finished diamond, the origin needs to be established at the beginning of the diamond’s journey.

One of the strongest scientific approaches is to analyse the rough diamond when its origin is documented, record its characteristics, and then match the resulting polished diamond back to that original rough.

This is the principle behind the GIA Diamond Origin Report.

GIA requires the rough diamond to be received in a documented, sealed and tamper-resistant parcel directly from the mining company. The rough is analysed and assigned an identification number. After cutting and polishing, the finished diamond can then be submitted and scientifically matched against the original rough.

The matching process can use a combination of physical measurements, spectroscopy, imaging and other characteristics recorded from the rough.

This is fundamentally different from taking an unknown polished diamond and attempting to guess its mine of origin.

What about the Kimberley Process?

The Kimberley Process is also an important part of the broader diamond supply chain.

It was established to prevent the international trade in conflict diamonds and provides a system of controls surrounding the international trade in rough diamonds.

DCLA’s own terms and conditions require diamonds listed through its website to have been imported under the Kimberley Process.

However, it is important to understand what this means.

A Kimberley Process certificate and supply-chain documentation can provide important evidence concerning the legal movement and declared origin of rough diamonds, but it is not the same as a gemmological laboratory looking at an unknown polished diamond and scientifically determining its mine.

What does a normal diamond certificate prove?

A diamond grading report is extremely useful, but consumers should understand what it does and does not establish.

A conventional grading report can document characteristics such as the diamond’s:

Carat weight
Colour
Clarity
Cut
Measurements
Proportions
Fluorescence and other laboratory observations

It may also identify whether a diamond is natural or laboratory-grown, depending on the laboratory and examination performed.

But a standard grading report does not automatically establish the mine where a natural diamond was extracted.

DCLA has also warned consumers about another important issue: a legitimate grading certificate can sometimes be presented with a different stone. The laboratory’s recent consumer alert highlights why matching the physical diamond to its report and verifying inscriptions and characteristics is so important.

You can read more about DCLA’s approach to diamond identification and certification through the DCLA Diamond Certification Laboratory.

What about coloured diamonds?

The situation becomes particularly interesting with natural coloured diamonds.

Certain geographic sources have become strongly associated with particular colours and colour ranges.

Australia’s Argyle mine, for example, became internationally famous for its pink diamonds. Other deposits have produced distinctive populations of yellow, blue, brown and other coloured diamonds.

Colour, hue and saturation can therefore sometimes provide useful clues about a possible source.

But again, a clue is not proof.

A particular colour may be much more frequently encountered from one locality than another, while similar colours can occur elsewhere.

The same principle applies to other characteristics such as inclusions, growth features and trace chemistry.

A laboratory may be able to say that a stone displays characteristics that are consistent with diamonds seen from a particular source. That does not necessarily mean the laboratory can prove that the individual diamond came from that mine.

The difference between identification and provenance

This is perhaps the most important distinction for consumers.

Identification asks:

What is this diamond?

Provenance asks:

Where did this particular diamond come from and can its journey be documented?

A laboratory can provide powerful scientific evidence about the first question.

The second question requires something more: a chain of evidence connecting the individual diamond to its source.

That evidence can include:

  • Mine documentation
  • Rough diamond identification
  • Sealed parcels
  • Export documentation
  • Kimberley Process documentation where applicable
  • Manufacturer records
  • Rough-to-polished matching
  • Laser inscriptions
  • Grading reports
  • Purchase invoices
  • Supplier records
  • Chain-of-custody documentation
  • Verified digital traceability systems

Documentation is the key to provenance

The simplest way to think about diamond provenance is this:

You cannot reliably create provenance after the diamond has lost its documented history.

If a diamond is mined, mixed with thousands of other diamonds, sold through several companies, cut and polished, and eventually appears years later without its original documentation, scientific examination may be unable to reconstruct its exact mine of origin.

By contrast, if the diamond’s identity is established at the mine and maintained throughout the manufacturing process, its journey can potentially be verified.

This is why modern diamond traceability systems are becoming increasingly important.

GIA itself has stated that there is currently no scientific method capable of determining country of origin simply by examining a random natural diamond. Its origin services instead rely on verified origin information and scientific matching between the rough and polished diamond.

The DCLA view

At DCLA, we believe consumers should be given a clear distinction between what can be scientifically established and what may simply be an educated opinion.

Diamonds from certain mines can share characteristics. Certain colours, qualities, inclusions and growth features may occur more frequently in particular deposits.

But the majority of gem-quality white diamonds, once polished, do not carry a unique scientific fingerprint that allows their mine of origin to be established with certainty.

And while some coloured diamonds may display characteristics strongly associated with particular sources, those characteristics are not automatically proof of origin.

The bottom line is simple:

If you want to know where your diamond came from, look at the chain of evidence not just the appearance of the stone.

A diamond grading report can tell you what the diamond is.

Scientific examination can identify many of its characteristics.

But provenance comes from being able to connect that individual diamond to its documented source.

For a diamond whose geographic origin is important to the buyer, the strongest evidence is documentation and traceability maintained from the rough diamond through cutting, polishing and sale.

In the world of diamond provenance, a good story is not the same as proof.

The most valuable provenance is the provenance that can be documented, verified and traced back to the source.

For further information on diamond identification, certification and laboratory-grown diamond detection, visit DCLA – Diamond Certification Laboratory of Australia and explore DCLA’s educational resources, including DCLA’s article on diamond mine origin and DCLA’s information on natural and laboratory-grown diamonds.

Independent research

For further scientific reading, GIA’s research on the geographic origin of diamonds explains the limitations of current analytical methods and why documented origin information remains essential. GIA: Methods and Challenges of Establishing the Geographic Origin of Diamonds

GIA also explains its rough-to-polished scientific matching process through its Diamond Origin Report service.

Thursday, 2 July 2026

Messika Showcases Botswana’s Extraordinary Okavango Blue Diamond in One of the World's Rarest High Jewellery Creations

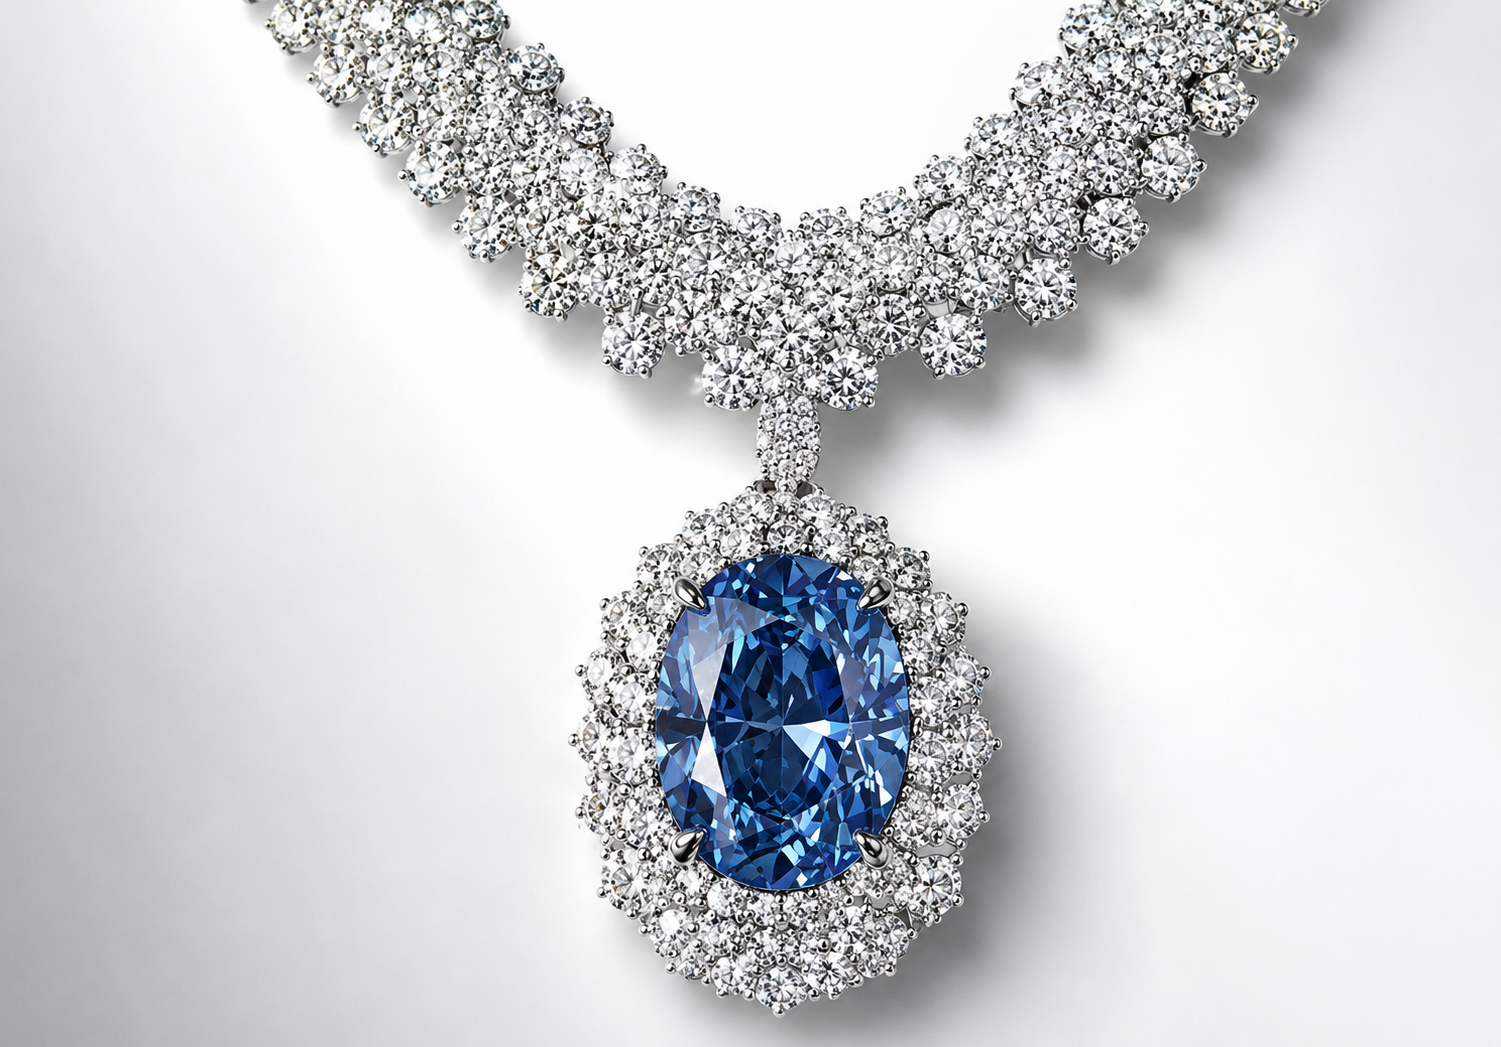
 20.46 carat Okavango Blue Diamond

French high jewellery house Messika has unveiled an exceptional necklace featuring one of the rarest natural diamonds ever discovered, the remarkable 20.46 carat Okavango Blue Diamond. The extraordinary gem, recovered from Botswana’s renowned Orapa mine, represents one of the finest blue diamonds ever unearthed and highlights the country’s position as a leading source of exceptional natural diamonds.

The story of the Okavango Blue began in 2019 when a 41.11 carat rough blue diamond was discovered at the Orapa mine. Following an extensive cutting and polishing process, the crystal was transformed into a breathtaking 20.46 carat Fancy Deep Blue VVS2 Type IIb oval diamond, a combination of colour, clarity and rarity seldom encountered in the natural world.

Recognising the significance of the gem, the Government of Botswana commissioned celebrated jewellery designer Valérie Messika to create a one of a kind masterpiece worthy of such an extraordinary diamond. Rather than overwhelming the centre stone, Messika chose a timeless design that allows the blue diamond to remain the undisputed focal point.

The completed necklace features the Okavango Blue suspended within a halo of white diamonds and attached to a collar containing more than 500 meticulously set diamonds. The contrast between the brilliant white diamonds and the deep blue centre stone intensifies the diamond’s remarkable colour while emphasising its exceptional size and beauty.

Messika explained that her objective was to create a design that honoured the diamond itself rather than compete with it. The elegant medallion inspired setting gives the necklace a classic appearance while showcasing one of nature’s rarest geological treasures.

Founded in Paris in 2005, Messika has become one of the world’s most recognised contemporary luxury jewellery brands. Valérie Messika inherited generations of diamond expertise through her father, renowned diamond dealer André Messika, and has built an international reputation for modern diamond jewellery collections that combine technical craftsmanship with contemporary design.

Despite its extraordinary value, the necklace has not been created for commercial sale. Instead, it serves as a celebration of Botswana’s natural diamond heritage and the country’s commitment to showcasing its exceptional mineral resources through world class craftsmanship.

The project also reflects Botswana’s long standing partnership with leading jewellers to promote the value and rarity of natural diamonds on the global stage. Messika previously collaborated with Botswana on another remarkable high jewellery creation featuring a rare 33 carat flawless diamond recovered from the country’s mining industry.

Blue diamonds remain among the rarest gemstones on Earth. Their distinctive colour is produced by trace amounts of boron incorporated into the diamond crystal during its formation billions of years ago under extreme geological conditions. Experts estimate that only a tiny fraction of all natural diamonds display a blue colour, making stones such as the Okavango Blue exceptionally scarce.

The Okavango Blue stands as both a geological marvel and a showcase of exceptional craftsmanship. While many of the world’s finest diamonds ultimately enter private collections, this extraordinary necklace has been created as a symbol of Botswana’s natural wealth and the enduring beauty of rare natural diamonds, demonstrating that some treasures transcend commercial value and become part of diamond history.

Source: DCLA

Wednesday, 20 May 2026

Botswana and Angola Governments Join WFDB as Industry Seeks Closer Producer Links


The governments of Botswana and Angola have officially become affiliated members of the World Federation of Diamond Bourses in a significant move that strengthens ties between major diamond producing nations and the global trading sector.

The announcement was made on 18 May during the WFDB International Summit held in Gaborone.

Although neither country currently operates a fully established standalone diamond bourse, both nations have sought representation within the WFDB due to the critical role diamonds play in their economies. Botswana remains the world’s second largest producer of natural diamonds, while Angola continues to expand its position as a major African diamond producer and trading hub.

This marks the first time governments have been admitted into the WFDB, which represents the world’s leading diamond bourses and trading centres. Botswana and Angola have initially been granted affiliate membership status, with both countries expected to participate as full WFDB members at the World Diamond Congress 2026 in Singapore this July.

Bogolo Kenewendo, Botswana’s Minister of Minerals and Energy, said the membership demonstrates the country’s commitment to international co operation, responsible industry growth, and strengthening the position of natural diamonds in an increasingly competitive market shaped by synthetic stones.

For Botswana, direct engagement with the trading community is expected to enhance collaboration around transparency, traceability, and the differentiation of natural diamonds from lab grown products.

Diamantino Azevedo, Angola’s Minister of Mineral Resources, described the move as an important step in deepening Angola’s engagement with the international diamond trade while supporting broader industry collaboration. Angola has spent several years developing plans for its own diamond exchange as part of wider reforms aimed at modernising the country’s diamond sector.

Kimberley Process Faces Renewed Criticism Ahead of Mumbai Meeting

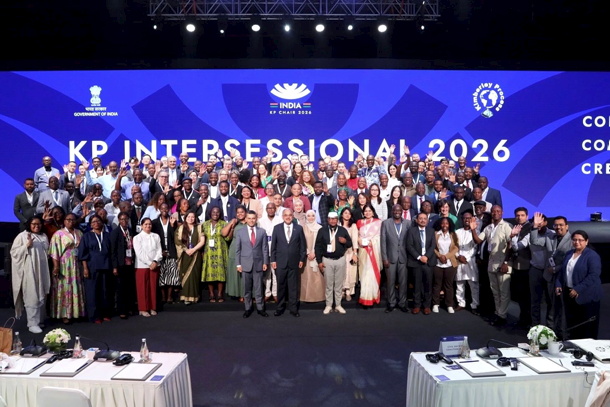
Meanwhile, the Kimberley Process has come under renewed pressure from civil society groups ahead of last week’s intersessional meeting in Mumbai.

The Kimberley Process Civil Society Coalition issued a strongly worded assessment criticising what it described as another failed reform cycle. The group argued that the KP continues to struggle with redefining conflict diamonds, addressing compliance concerns, and delivering meaningful transparency measures.

Farai Maguwu, vice coordinator of the KP Civil Society Coalition, said the natural diamond industry often focuses on competition from lab grown diamonds while failing to confront long standing structural issues within the sector itself.

He stated that the Kimberley Process must move beyond “superficial marketing adjustments” and instead become more transparent, accountable, and capable of responding to modern diamond related abuses.

However, World Diamond Council president Ronnie VanderLinden offered a far more optimistic assessment following the conclusion of the meeting.

VanderLinden praised the co operation shown by participants and said the KP demonstrated its ability to work through difficult issues under pressure. He also commended India’s leadership and its focus on the “3Cs” vision of Confidence, Credibility, and Compliance.

He added that the industry must now find the determination to modernise the definition of conflict diamonds so it better reflects current global realities and expectations surrounding responsible sourcing and ethical trade.

Source: DCLA

Tuesday, 14 April 2026

Diamond Debut for De Beers and Sotheby's Collaboration

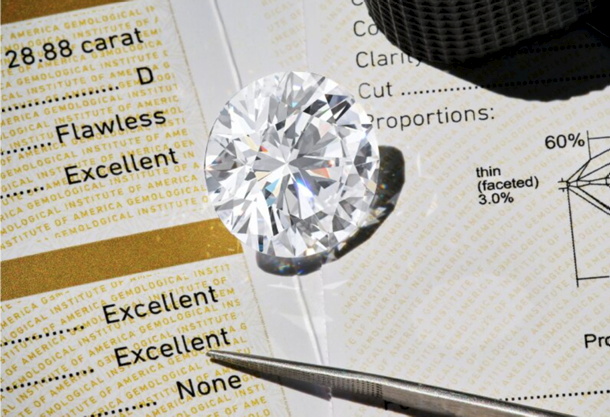
 The flawless D-color unmounted Jwaneng 28.88 - cut from a 114.83-carat rough recovered at Botswana's Jwaneng mine

The sale of the Jwaneng 28.88 diamond later this month marks the start of a collaboration between De Beers and Sotheby’s.

Together they aim to “present exceptional diamonds as works of art,” although no details on the terms or scope of the agreement have been made public.

The collaboration centers on joint marketing and storytelling, going beyond a standard consignment, in which the miner selects an auction house.

Both companies co-create a branded narrative – “earth to art” – to promote across their channels

The flawless D-color unmounted Jwaneng 28.88 – cut from a 114.83-carat rough recovered at Botswana’s Jwaneng mine (Debswana, De Beers’ 50-50 government venture) -leads the auction at Sotheby’s Magnificent Jewels & Jadeite sale in Hong Kong on 23 April.

It carries an estimate of HKD 17 million to HKD 22 million (USD 2.2 million to USD 2.8 million).

Other De Beers diamonds from Jwaneng will be offered at the same sale, including a solitaire ring and a pair of diamond earrings.

Source: DCLA

Monday, 13 April 2026

Botswana’s President Challenges De Beers for Greater Control of the Diamond Industry

Botswana’s President Challenges De Beers for Greater Control of the Diamond Industry


Botswana’s escalating challenge to De Beers marks a defining moment in the global diamond sector, as resource-rich nations increasingly pursue greater control over their natural assets. The long-standing model where multinational mining firms oversee operations while host nations receive royalties is now being reshaped by state-driven strategies aimed at securing a larger share of the value chain.

This shift reflects a broader geopolitical trend, with emerging economies seeking vertical integration across critical mineral supply chains. By moving beyond extraction and into cutting, polishing, and distribution, countries like Botswana are positioning themselves to capture more of the downstream value traditionally dominated by international corporations.


What Is Driving Resource Sovereignty in Diamond-Producing Nations?

At the core of this movement is a clear economic reality: controlling extraction alone limits long-term wealth creation. In the diamond industry, mining accounts for just 15–20% of the final retail value, while the remaining 80–85% is generated through downstream activities such as processing, branding, and retail distribution.

Governments across Africa are increasingly aware of this imbalance and are taking steps to address it. The push for resource sovereignty is not only about increasing revenue, but also about building sustainable, locally anchored industries that create employment and long-term economic resilience.


The Economics of Vertical Integration

Botswana’s ongoing negotiations highlight the financial logic behind vertical integration. The current bid process for a significant stake in De Beers represents a strategic opportunity to restructure ownership and maximise national returns.

A breakdown of the diamond value chain illustrates the potential:

  • Upstream mining: 15–20% of total value
  • Midstream processing and sorting: 25–30%
  • Downstream distribution and retail: 45–55%
  • Branding and marketing premiums: 10–15%

By expanding into these higher-margin segments, producing nations can significantly enhance revenue capture and reduce reliance on external operators.

A comparable long-term strategy can be seen in Government Pension Fund Global, which transformed oil revenues into a globally diversified investment portfolio demonstrating how resource wealth can be leveraged beyond commodity cycles.


Geopolitical Implications of Resource Control

Beyond economics, control over diamond resources provides substantial geopolitical leverage. Botswana’s reported engagement with Gulf-based investment partners, including sovereign wealth funds from Oman, signals a shift toward diversified strategic alliances.

Such partnerships extend beyond mining, encompassing energy, infrastructure, and broader mineral development. This multi-sector approach strengthens negotiating power while aligning with global trends in supply chain security.

Across Africa, similar strategies are emerging:

  • Democratic Republic of the Congo tightening control over cobalt
  • Ghana refining gold sector regulations
  • Zambia restructuring its copper industry

These developments highlight a continent-wide shift towards sovereign resource management, driven by both economic ambition and geopolitical necessity.


A Structural Shift in the Diamond Industry

Botswana’s stance represents more than a contractual dispute it signals a structural transformation in how diamond resources are owned, managed, and monetised. As producing nations assert greater control, the traditional dominance of multinational mining companies is being challenged.

For the global diamond industry, this evolution could redefine supply chains, pricing dynamics, and the balance of power for decades to come.

Source: DCLA

Wednesday, 1 April 2026

Botswana to Settle for Smaller De Beers' Stake?

 Botswana De Beers

Botswana may now settle for a minority stake in De Beers rather than seeking majority control, according to a report in The Economist.

It says the government is now pursuing at “least 25%,” which would indicate a significant softening in President Duma Boko’s position.

He has previously insisted, on many occasions, that he wants a controlling stake in the company, framing such a move as a matter of “economic sovereignty”.

The Economist also quotes an unnamed executive at Debswana – the government’s joint venture with De Beers, as saying: “It probably doesn’t make sense to go all out.”

Botswana currently owns 15% of the loss-making diamond miner, which is being sold by parent company Anglo American.

In December 2025, the IMF cautioned against Botswana’s plans to increase its stake, given the country’s struggling economy.

The president rejected that call in no uncertain terms saying it was for the people of Botswana to decide, not the IMF.

“It’s our people who are running this country, and we said we want De Beers, and we are going to take it,” he said.

Angola’s government has also expressed an interest in acquiring a significant stake in De Beers, and Namibia is also a potential bidder.

Experts believe the most likely outcome will be that a consortium or private investors will buy a controlling stake, and African governments including Botswana will hold minority shares.

Source: DCLA

Thursday, 26 March 2026

Botswana seeks to raise debt ceiling to weather diamond market downturn

 Natural rough diamond embedded in rock, mineral extraction challenge

Natural rough diamond embedded in rock, mineral extraction challenge

Botswana’s finance minister sought parliamentary approval on Wednesday to raise the country’s statutory debt ceiling from 40% to 60% of gross domestic product, as a prolonged downturn in the global market for diamonds has pressured public finances.

Ndaba Gaolathe said the proposal was aimed at giving the government flexibility during periods of economic stress, such as the one it is going through now.

The diamond market downturn has hit the southern African country hard, with two successive economic contractions in 2024 and 2025. Botswana had been viewed as an economic success story, partly because of its low public debt.

Raising the debt ceiling “does not imply immediate borrowing up to that level but rather establishes prudent headroom,” Gaolathe told lawmakers.

In last month’s budget, he said Botswana was expected to breach a debt-to-GDP ratio of 40% in the fiscal year that starts in April.

Late last year International Monetary Fund staff recommended raising the debt ceiling to 50% of GDP to give fiscal space to respond to economic shocks.

S&P Global this month downgraded Botswana’s sovereign ratings, saying diamond market weakness would weigh on its economy for longer than expected.

Diamonds typically account for about a third of Botswana’s national revenue and 75% of its foreign-exchange earnings.

Source: DCLA

Wednesday, 25 March 2026

DCLA News | Botswana Doubles Down as Diamond Supply Tightens and Demand Strengthens

 Botswana Doubles Down as Diamond Supply Tightens

The diamond pendant worn by Bogolo Kenewendo at a recent Cape Town mining conference was more than a personal statement it symbolised Botswana’s unwavering commitment to the very resource that transformed its economy.

For decades, De Beers has been synonymous with Botswana’s rise, helping elevate the nation into one of Africa’s most prosperous economies. Now, Botswana is preparing to deepen that relationship, signalling intentions to increase its existing 15% stake in the iconic diamond firm a bold move that underscores its long-term confidence in the sector.

Supply Tightens as Market Shows Early Recovery

At the same time, signs of recovery are emerging across the global diamond market. Russian mining giant Alrosa has reported price increases of between 6% and 9% on rough diamonds since the start of the year, with the strongest gains seen in the high-value 2 to 10 carat segment a category that represents roughly 80% of its production value.

According to CEO Pavel Marinychev, the market for larger stones — particularly those above 3 carats — has stabilised, with tightening supply now becoming increasingly evident. Price improvements, initially modest in January, have accelerated through February and March, with nearly half of Alrosa’s regular assortment seeing upward revisions.

Global Production Faces Structural Decline

Looking ahead, the supply side of the diamond industry is under significant pressure. Alrosa forecasts that global diamond production will fall below 100 million carats by 2026 the lowest level in two decades.

This decline is being driven by a combination of resource depletion and operational cutbacks. Alrosa itself has already suspended output at several smaller projects, while major deposits are reaching the end of their lifecycle. Notably, the Diavik Diamond Mine, operated by Rio Tinto, is approaching closure, with other Canadian mines expected to follow.

The result is a growing scarcity of large, high-quality stones a dynamic that could underpin prices in the years ahead.

Auction Market Confirms Demand for Rarity

Further evidence of resilience in the diamond market comes from the secondary sector. Christie’s New York recently reported strong results from its “Jewels Online” sale, which achieved $8.5 million and exceeded expectations by reaching 131% of its low estimate.

Among the highlights was a 10.02-carat D-colour, internally flawless Type IIa diamond ring by Tiffany & Co., which sold for $521,000. Another 10.03-carat D-colour Type IIa diamond achieved $508,000 significantly above its estimate.

Provenance also played a key role, with a historic jewellery set from Elizabeth Taylor’s collection selling for over seven times its low estimate.

Christie’s noted strong global participation, with buyers spanning the Americas, Asia-Pacific, and EMEA regions reinforcing the enduring demand for rare, high-quality, and well-documented diamonds.

Strategic Outlook

Botswana’s move to increase its exposure to De Beers is not without risk but it is a calculated one. With global supply tightening, major deposits depleting, and demand for exceptional stones holding firm, the country is effectively positioning itself to capture greater long-term value from a shrinking resource base.

For the global diamond trade, the message is clear: scarcity is returning and with it, the potential for renewed price strength, particularly at the top end of the market.

Source: DCLA

Natural Diamond Prices Begin to Stabilise, But Has the Market Turned?

After several challenging years for the natural diamond industry, there are growing signs that the market may finally be reaching a period o...