Showing posts with label Pandora that lab-grown diamonds. Show all posts

Friday, 16 October 2026

The Hidden Cost of Falling Diamond Prices, Lab-Grown Competition and Lost Livelihoods

 The unintended consequences of the 'blood diamond' narrative

The potential sale of De Beers highlights the challenges facing the natural diamond industry. The rise of lab-grown diamonds, weakening consumer demand, deteriorating economic conditions and years of changing consumer perceptions have combined to place unprecedented pressure on an industry that supports millions of livelihoods around the world.

The natural diamond industry is facing a defining moment. De Beers, one of the world’s most recognised diamond producers, is at the centre of a proposed ownership change as its controlling shareholder, Anglo American, seeks to sell its 85% stake in the business.

According to reports, luxury group Richemont, owner of Cartier and Van Cleef & Arpels, is considering joining a consortium led by former De Beers chief executive Gareth Penny. Other potential participants reportedly include Belgian diamond manufacturer Pluczenik and US jewellery retailer Signet.

The involvement of major luxury, manufacturing and retail businesses reflects the strategic importance of natural diamonds to the jewellery trade. However, it also raises a difficult question: are the challenges facing the diamond industry temporary, or are they evidence of a fundamental structural change?

The rise of lab-grown diamonds has changed the market

One of the most significant developments affecting natural diamonds has been the rapid growth of lab-grown diamonds.

Chemically and physically similar to natural diamonds, lab-grown stones can offer consumers comparable visual characteristics at substantially lower prices. Advances in production technology have increased supply and intensified price competition, particularly in the commercial and lower-priced segments of the diamond market.

For consumers primarily interested in appearance and size, lab-grown diamonds can be an attractive alternative. But their growing availability has also changed expectations about what a diamond should cost.

Natural diamonds and lab-grown diamonds are produced through very different processes. Natural diamonds are geological products formed over immense periods of time and recovered through mining. Lab-grown diamonds are manufactured using industrial processes that require equipment, energy and ongoing technological investment.

As manufacturing capacity expands and production becomes more efficient, lab-grown diamond prices can fall sharply. This creates a challenge for natural diamonds, whose supply depends on geological discoveries, mining operations, labour, infrastructure and substantial capital investment.

The consequences extend beyond competition at the retail counter. When consumers begin comparing natural diamonds with substantially cheaper laboratory-grown alternatives, natural diamond producers, manufacturers, wholesalers and retailers must reconsider pricing, marketing and inventory strategies.

The result has been significant pressure on diamond prices, although the impact varies according to size, quality, rarity and market segment. Higher-quality and genuinely rare natural diamonds may behave differently from more readily available commercial goods.

Economic uncertainty is adding to the pressure

Lab-grown diamonds are not the only factor affecting the natural diamond market.

Diamonds are discretionary purchases. When household budgets are under pressure, interest rates remain elevated, employment prospects become uncertain or consumers worry about the economic outlook, expensive jewellery can be postponed or removed from the shopping list altogether.

Weakening consumer confidence in major markets, economic uncertainty and changing spending priorities can therefore reduce demand for natural diamonds at the same time that lab-grown supply is expanding.

This combination is particularly difficult for an industry that relies on consumer confidence, luxury spending and the willingness of buyers to pay premiums for natural stones.

When demand weakens, retailers reduce orders, manufacturers become more cautious, wholesalers hold inventory for longer and miners may be forced to reduce production or sell rough diamonds at lower prices.

These pressures can reinforce one another. Lower prices affect profitability, weaker profitability reduces investment, and uncertainty throughout the supply chain makes it harder for businesses to plan for the future.

De Beers illustrates the scale of the challenge

De Beers has been loss-making since 2023, according to the figures reported in the source material. For 2024, it recorded an underlying earnings loss before interest and tax of approximately US$787 million, on revenue of nearly US$3.5 billion.

The proposed sale of Anglo American’s controlling stake has consequently attracted considerable attention.

For Richemont and other potential investors, ownership could provide greater influence over an important part of the natural diamond supply chain. For the industry as a whole, however, the central issue is whether consumer demand can recover sufficiently to support a sustainable business.

If the downturn is cyclical, an improvement in economic conditions and luxury spending could provide relief. If the market is undergoing a more permanent structural change because of lab-grown competition and evolving consumer preferences, a recovery may be considerably more difficult.

The distinction matters. A temporary decline can be managed by reducing costs and adjusting production. A structural decline requires businesses to reconsider their long-term strategies, their target markets and the reasons consumers should continue choosing natural diamonds.

The unintended consequences of the ‘blood diamond’ narrative

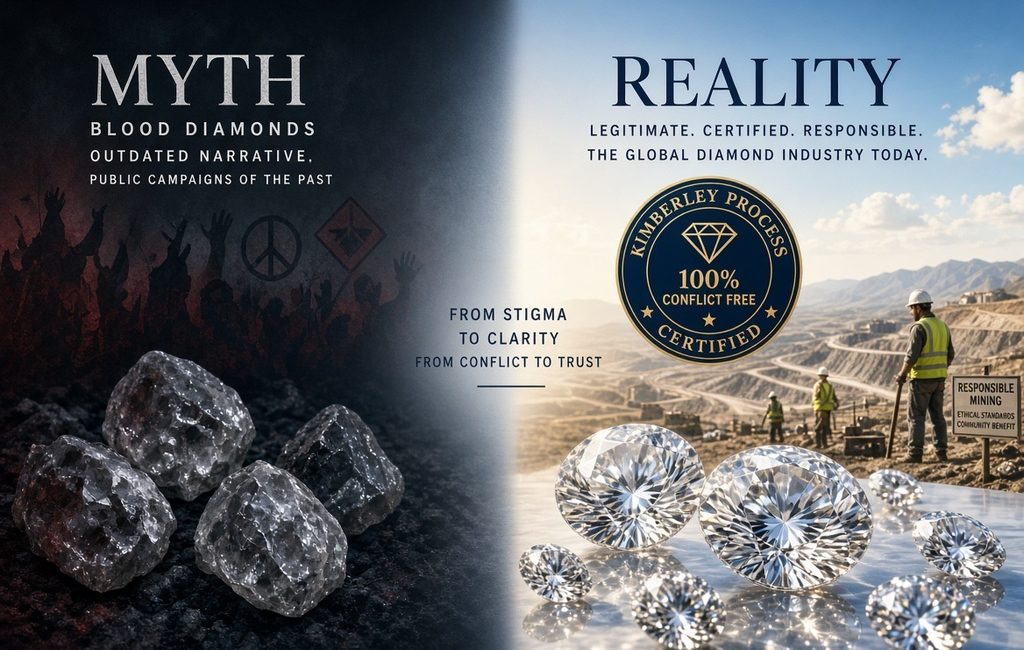
Another important chapter in the industry’s difficulties concerns the public campaigns against so-called blood diamonds.

The term emerged from genuine and serious concerns about diamonds being used to finance armed conflict and human rights abuses. These issues deserved attention, and initiatives such as the Kimberley Process were developed to help prevent conflict diamonds from entering legitimate international trade.

However, there is a difference between exposing documented wrongdoing and allowing a broad public narrative to create the impression that the entire natural diamond industry is associated with conflict or exploitation.

In the public debate, the distinction between diamonds from conflict areas and diamonds responsibly mined in other parts of the world has not always received the attention it deserves.

Botswana, Namibia, South Africa and other diamond-producing regions have developed legitimate mining industries that provide employment, government revenue, infrastructure and opportunities for local communities. In some countries, diamond revenues have played a significant role in funding public services and supporting economic development.

When consumers are encouraged to view natural diamonds as inherently unethical, without understanding where individual stones originate or how they were produced, the consequences can extend well beyond the intended target of the campaign.

The uncomfortable question is whether well-intentioned campaigns can sometimes cause harm to the very people they are meant to protect.

A campaign designed to discourage the purchase of diamonds associated with conflict may also discourage purchases of responsibly sourced diamonds from communities whose livelihoods depend on mining.

When demand falls, the consequences can reach miners, independent diggers, cutters, polishers, traders and local businesses. Workers who have spent years developing specialised skills cannot necessarily transfer those skills to another industry overnight.

Small-scale miners and independent diggers are particularly vulnerable. Unlike large corporations, they may have limited financial reserves and few alternative sources of income. If their stones become harder to sell or their prices fall below the cost of extraction, their livelihoods can disappear.

This does not mean that concerns about human rights, environmental damage or conflict financing should be dismissed. They remain important. It means that campaigns should be evidence-based, specific and attentive to the economic consequences of their demands.

The problem with being an armchair warrior

Public advocacy can play an important role in exposing misconduct and encouraging responsible business practices. But there is a danger when people who have little direct experience of an industry campaign for sweeping changes without fully considering the consequences.

It is relatively easy to demand that consumers stop buying a product. It is much harder to understand what happens to the workers, families and communities whose incomes depend on producing it.

An armchair warrior can advocate for a seemingly simple solution from a comfortable distance, without having to live with the consequences if the solution fails.

In the diamond industry, a blanket rejection of natural diamonds can affect people far removed from the controversies that prompted the original campaign. A responsible miner in southern Africa, an independent digger, a diamond polisher in India or a small jewellery business may have no connection to the conduct being condemned, yet still suffer from the resulting decline in demand.

The same principle applies to many industries. Campaigns that focus exclusively on one perceived problem can overlook the broader economic system in which millions of people work.

Good intentions do not automatically produce good outcomes. Effective advocacy requires an understanding of both the problem being addressed and the people who may bear the cost of the proposed solution.

Natural diamonds have a story lab-grown diamonds cannot replicate

Despite the challenges, natural diamonds retain characteristics that distinguish them from their laboratory-grown counterparts.

Their geological origins, natural rarity and individual histories form part of their appeal. For many buyers, a natural diamond represents more than its appearance. It can symbolise a milestone, a family connection, a relationship or an object intended to be passed from one generation to the next.

Lab-grown diamonds offer a different proposition. They can provide size and visual appeal at a lower purchase price, but their economics are closely connected to manufacturing capacity, production costs and technological development.

Neither distinction means every natural diamond will retain its value or that every lab-grown diamond is a poor purchase. Diamond prices depend on many variables, and consumers should not assume that either category guarantees future appreciation.

The important point is that the two products have different supply dynamics and different market propositions. Treating them as interchangeable simply because they may look similar overlooks the factors that influence their long-term supply and commercial value.

For the natural diamond industry, the challenge is to explain these differences honestly and convincingly, without relying on outdated assumptions or promising consumers that natural diamonds will always rise in price.

What happens next?

The proposed sale of De Beers is more than a corporate transaction. It is a test of confidence in the future of the natural diamond business.

Potential investors must weigh the company’s renowned position in the industry against its recent financial performance, the cost of mining, changing consumer preferences and the uncertainty surrounding future demand.

The outcome will depend on several interconnected factors:

  • Consumer confidence: Whether improving economic conditions encourage households to resume spending on discretionary luxury goods.
  • Lab-grown competition: Whether natural diamond producers can establish a clear and compelling distinction between mined and manufactured diamonds.
  • Responsible sourcing: Whether the industry can demonstrate credible standards while ensuring that legitimate producing communities are not unfairly stigmatised.
  • Supply discipline: Whether production can be aligned with genuine demand without undermining the long-term viability of mining operations.
  • Consumer education: Whether buyers receive balanced information about origin, rarity, manufacturing, environmental considerations and the differences between natural and laboratory-grown stones.

The industry may emerge smaller and more focused, with greater emphasis on quality, provenance and genuinely rare natural diamonds. However, a sustained recovery cannot simply be assumed. If consumer preferences have permanently shifted in some market segments, businesses will need to adapt accordingly.

A final thought: good intentions need real-world understanding

The diamond industry is experiencing the combined effects of technological change, economic uncertainty, shifting consumer preferences and decades of debate about ethical sourcing.

Lab-grown diamonds have introduced a powerful new source of competition. Deteriorating economic conditions can weaken discretionary spending. Meanwhile, campaigns against conflict diamonds, although rooted in legitimate concerns, demonstrate why broad public messaging must distinguish between documented abuses and responsible producers.

Behind every price chart and corporate announcement are real people: miners, independent diggers, cutters, polishers, jewellers and families whose livelihoods depend on the trade.

Holding businesses accountable for genuine wrongdoing is necessary. But damaging an entire industry through inaccurate generalisations or poorly considered campaigns can create consequences that extend far beyond their original objectives.

Before demanding that an industry disappear, it is worth asking who will pay the price, what alternatives will replace the lost livelihoods, and whether the intended beneficiaries will ultimately be better off.

The future of natural diamonds will depend not only on corporate ownership and market prices, but also on whether the industry can rebuild consumer confidence, communicate its value and demonstrate that responsible diamond production can support both economic opportunity and ethical standards.

DCLA is the Diamond Certification Laboratory of Australia. Understanding the differences between natural and laboratory-grown diamonds, including their origins and identification, is increasingly important for consumers navigating today’s changing diamond market.

Friday, 11 September 2026

Lab-Grown Diamonds: Is the Era of Falling Prices Coming to an End?

 Rising production costs, energy consumption and shrinking margins could change the economics of the lab-grown diamond industry

Rising production costs, energy consumption and shrinking margins could change the economics of the lab-grown diamond industry

For several years, the lab-grown diamond industry has been defined by one dominant story: falling prices.

What was once promoted as a lower-cost alternative to natural diamonds has become dramatically cheaper as manufacturers around the world expanded production capacity. In India, which has become one of the world’s major lab-grown diamond manufacturing and polishing centres, the rapid growth in production has created intense competition and severe pressure on margins.

But the economics of the industry may now be reaching an important turning point.

Recent developments in Surat suggest that manufacturers and traders are increasingly concerned that prices and discounts have fallen too far.

At a meeting of the Surat Lab Grown Diamond Association on September 7, industry participants called for greater discipline in pricing and an end to aggressive discounting. Reports from India said polished lab-grown diamond prices had recently increased by approximately 20% to 25%, while traders were reducing discounts from around 7% to approximately 3% to 4%.

This does not necessarily mean that lab-grown diamond prices are about to return to previous levels.

Instead, it may signal something more fundamental: the industry is beginning to confront the cost of actually producing a diamond.

A decade of falling prices

The scale of the price decline has been extraordinary.

According to data reported by the Times of India, India’s average export value for polished lab-grown diamonds fell from approximately US$246 per carat in 2016–17 to around US$60 per carat in 2025–26.

During 2025–26, India exported approximately 18.8 million carats of polished lab-grown diamonds, up substantially in volume, while the total export value fell to approximately US$1.133 billion.

That means the industry was producing and exporting significantly more diamonds while receiving considerably less per carat.

The same report found that the average export value had improved to almost US$69 per carat during April and May 2026, suggesting that the long decline may have started to stabilise.

The latest developments in Surat provide another indication that the market may be attempting to establish a floor.

The problem with selling below cost

The Surat Lab Grown Diamond Association has warned that excessive discounting is damaging manufacturers’ earnings.

Association president Babu Vaghani reportedly said that continued price reductions were reducing manufacturers’ profits and putting pressure on wages.

The concern is straightforward.

A diamond manufacturer has to pay for:

  • sophisticated growing equipment
  • electricity
  • cooling systems
  • gases such as hydrogen and methane for CVD production
  • diamond seed plates
  • maintenance
  • skilled technicians
  • factory buildings
  • financing and equipment depreciation
  • cutting and polishing
  • grading and certification
  • rejected or lower-quality production
  • logistics and administration

If the finished diamond is continually sold for less, eventually something has to give.

Manufacturers can reduce margins, reduce wages, reduce investment, reduce production or leave the industry altogether.

Reports from Surat indicate that some polishing units have already considered moving into other industries as prolonged price erosion has reduced earnings and contributed to skilled-worker shortages.

Energy: the hidden cost of a laboratory diamond

One of the most important factors in understanding the future cost of lab-grown diamonds is energy.

Lab-grown diamonds are not simply manufactured like an ordinary consumer product. They are grown under highly controlled conditions using enormous amounts of technology, heat, pressure, vacuum systems, plasma and cooling.

There are two principal technologies used to grow gem-quality laboratory diamonds: HPHT, or High Pressure High Temperature, and CVD, or Chemical Vapour Deposition.

DCLA’s information on synthetic diamonds and laboratory-grown diamond certification explains the technologies used to produce laboratory-grown diamonds and the importance of identifying their origin.

The Gemological Institute of America explains that HPHT involves temperatures of approximately 1,300°C to 1,600°C and pressures exceeding 870,000 pounds per square inch. CVD uses a vacuum chamber, gases and an energy source to create a plasma in which carbon atoms are deposited onto diamond seed plates.

For CVD production in particular, electricity is a critical ongoing input because the reactor, plasma generation, vacuum equipment, pumps and cooling systems must operate for extended periods.

Research into synthetic diamond production has identified electricity as a major environmental and production hotspot for microwave-CVD manufacturing.

The exact electricity consumption varies considerably depending on equipment, efficiency, production scale, cooling systems and operating conditions. Published estimates range from several dozen kilowatt-hours per carat to substantially more in less-efficient systems.

One recent technical analysis estimates modern HPHT production at around 36 kWh per carat under particular operating conditions, while CVD systems can vary substantially, with some commercial systems using around 77 kWh per carat and less-efficient systems exceeding 200 kWh per carat. These figures should be treated as indicative rather than a universal industry standard.

The important point is not one particular number.

It is that electricity is a recurring cost for every diamond produced.

Once a manufacturing plant has been built, the machines still have to run.

Why energy could become a price driver

This is where the economics become particularly interesting.

The initial investment in a laboratory-grown diamond factory is largely a capital cost. The manufacturer buys reactors, presses, vacuum equipment, cooling systems, power infrastructure and other machinery.

Once the factory is operating, however, the manufacturer faces continuing costs.

Electricity is one of them.

Unlike the purchase of a machine, electricity cannot be depreciated away. Every production cycle consumes power.

That means energy prices can have a direct effect on the minimum economic price at which a manufacturer can operate.

If electricity prices increase, production costs rise.

If manufacturers are already operating on very small margins, they may have little ability to absorb those increases.

The effect can be particularly significant for producers using electricity-intensive CVD or HPHT systems for long production cycles.

This creates an important potential turning point for the lab-grown diamond industry.

The lower the selling price becomes, the more important the underlying production cost becomes.

At some point, manufacturers have to decide whether producing another carat is economically worthwhile.

The economics of oversupply

The spectacular fall in lab-grown diamond prices was not caused simply by consumers suddenly deciding that diamonds were worth less.

A major factor has been the expansion of production capacity.

India alone produced more than 3 million lab-grown diamonds in 2023 and accounted for more than 15% of global output, according to India’s NITI Aayog.

Other major production centres, particularly China, also expanded capacity.

The result was a classic supply-and-demand problem.

When production capacity grows faster than consumer demand, manufacturers compete for buyers.

One manufacturer reduces its price.

Another offers a discount.

A trader offers an additional discount.

A broker undercuts another broker.

The process can continue until the market price is significantly below the level manufacturers originally expected.

This is precisely why the recent call from Surat for an end to excessive discounting is significant.

The industry is effectively saying that price competition has gone too far.

DCLA has previously examined this broader transformation in the diamond industry in its article on lab-grown diamonds as a structural disruption to the traditional diamond industry.

The cost floor

Every manufactured product has an economic cost floor.

That does not mean prices can never fall below the cost of production. Companies can sell inventory at a loss, factories can operate below capacity and distressed businesses can liquidate stock.

But those conditions cannot continue indefinitely.

If manufacturers consistently lose money, production capacity eventually disappears.

Machines are switched off.

Investment stops.

Workers leave.

Companies close or move into other businesses.

Supply then begins to contract.

This is potentially what the lab-grown diamond industry is now trying to avoid.

The Times of India reported that persistent price erosion has already forced some polishing units to consider alternative industries and has placed pressure on wages.

Could this lead to higher lab-grown diamond prices?

Possibly — but it is important not to confuse a price stabilisation with a return to the prices of several years ago.

There are still enormous production capacities around the world, and technological improvements can continue to reduce manufacturing costs.

Competition also remains intense.

However, the recent 20% to 25% reported increase in polished prices in Surat, combined with the reduction in discounts from approximately 7% to 3%–4%, suggests that parts of the industry are already attempting to establish greater pricing discipline.

If manufacturers continue to reduce production, consolidate capacity or refuse to sell below sustainable levels, prices could eventually find a stronger floor.

Energy costs could become an important part of that floor.

Why energy matters more as prices fall

There is an interesting economic paradox here.

When lab-grown diamonds were expensive, energy represented only one component of a much larger selling price.

As the selling price falls dramatically, however, every operating cost becomes proportionally more important.

Imagine a manufacturer producing a diamond at a total cost of $100 per carat.

Selling it for $200 leaves room for overheads, financing and profit.

Selling it for $120 leaves very little.

Selling it for $90 creates a loss.

The actual numbers vary enormously between manufacturers, technologies, electricity prices, yields and diamond specifications. Therefore, there is no single industry-wide production cost that can be applied to every lab-grown diamond.

But the economic principle remains the same.

There is a point at which further price reductions stop being sustainable.

The next phase of the lab-grown diamond market

The laboratory-grown diamond industry may therefore be entering a different phase.

The first phase was technological.

Could diamonds be grown commercially in laboratories?

The second phase was expansion.

How quickly could manufacturers increase production?

The third phase was price competition.

How cheaply could those diamonds be sold?

The next phase may be about economics.

How cheaply can a diamond realistically be produced while still providing a sustainable return to the manufacturer?

That question could become increasingly important.

The industry has already demonstrated that laboratory-grown diamonds can be produced at dramatically lower prices than natural diamonds.

What it has not yet demonstrated is where the long-term sustainable price floor lies.

Energy will be one of the factors determining that answer.

So will equipment depreciation, financing, labour, gases, seeds, yields, polishing, grading and the cost of maintaining sophisticated manufacturing facilities.

What this means for consumers

For consumers, lower lab-grown diamond prices have been an obvious advantage.

They have made larger and higher-specification diamonds accessible to a much wider market.

But consumers should also understand that cheap does not necessarily mean the price cannot fall further — and it does not mean the price cannot eventually rise.

The current market is still evolving.

The recent developments in Surat suggest that manufacturers are increasingly unwilling to continue absorbing falling margins and aggressive discounts.

If production is reduced and pricing discipline improves, the market could begin to stabilise.

If energy and other operating costs rise at the same time, those costs could become increasingly important in determining the minimum sustainable price of a lab-grown diamond.

The DCLA view

For consumers, the most important point remains understanding exactly what they are buying.

A laboratory-grown diamond is a real diamond with essentially the same chemical composition and crystal structure as a natural diamond, but its origin is different.

DCLA’s recent article, Natural or Laboratory-Grown? How Can You Tell What Diamond Is in Your Ring?, explains why laboratory-grown and natural diamonds can be difficult to distinguish visually and why independent laboratory testing is important.

DCLA recommends independent diamond identification and certification where appropriate, particularly when establishing whether a diamond is natural or laboratory-grown.

The DCLA Diamond Grading Report records important characteristics including carat weight, colour, clarity, measurements, treatments and whether the diamond is natural or laboratory-grown.

The laboratory-grown diamond industry has undergone an extraordinary period of technological development and price compression.

The next question is whether it can achieve something arguably more difficult:

long-term economic stability.

If manufacturers can no longer operate profitably at today’s heavily discounted prices, and if energy and other production costs continue to rise, the economics of the industry suggest that prices may eventually have to move higher or production capacity will have to contract.

The recent events in Surat may be an early indication that this process has already begun.

Monday, 11 May 2026

The Natural Diamond Council has strongly rejected recent claims by Pandora

 The council warned that reducing the discussion solely to carbon comparisons risks misleading consumers

The Natural Diamond Council has strongly rejected recent claims by Pandora that lab-grown diamonds carry a carbon footprint up to 90 per cent lower than natural diamonds, describing the campaign as misleading and damaging to the global natural diamond industry.

Pandora based its claims on a 2019 study conducted by the former Diamond Producers Association, now operating as the Natural Diamond Council. However, the NDC argues the data relied upon is outdated, with some figures tracing back more than a decade, and says the study only reflected a limited segment of the natural diamond sector rather than the industry as a whole.

In an open letter addressed to Pandora CEO Berta De Pablos-Barbier, the NDC criticised what it described as a “PR stunt” designed to unfairly discredit natural diamonds in favour of synthetic alternatives.

The organisation further stated that comparisons between natural and lab-grown diamonds are inherently flawed because they represent two fundamentally different categories. According to the NDC, natural diamonds are rare geological creations formed over billions of years, while lab-grown diamonds are manufactured products capable of being produced in virtually unlimited quantities.

The council warned that reducing the discussion solely to carbon comparisons risks misleading consumers and spreading misinformation about the broader social and economic contribution of the natural diamond industry, which supports millions of people globally through mining, manufacturing and trade.

The NDC also called on Pandora to engage more constructively with industry bodies focused on improving sustainability, environmental stewardship and social responsibility across both the natural and synthetic diamond sectors.

Source: DCLA

Inherited Jewellery and Family Valuables, Why Expert Assessment Matters

  Inherited jewellery, diamonds, gold and family heirlooms can represent significant financial and sentimental value. Before dividing an est...