
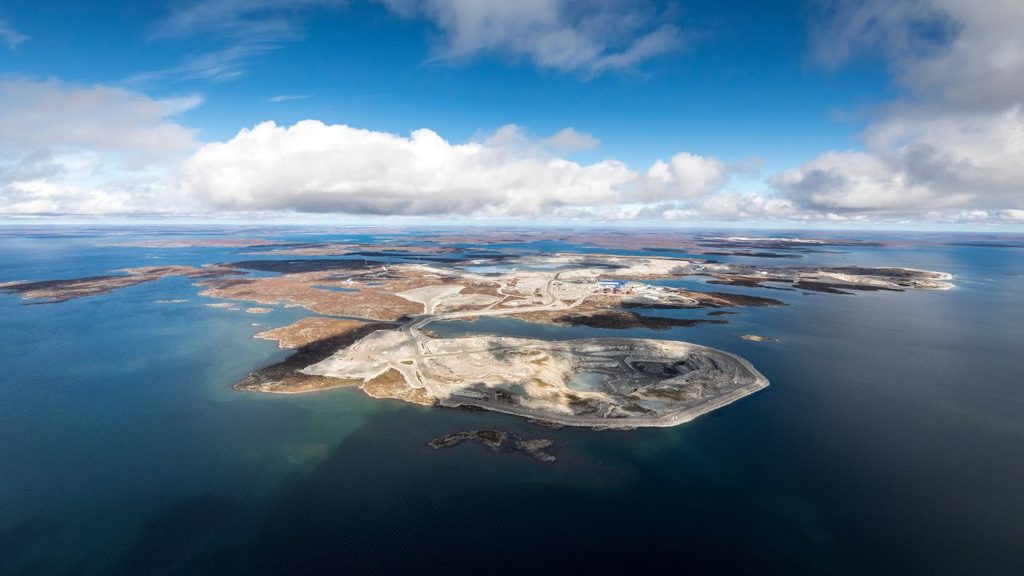
The closure of Canada’s Diavik diamond mine marks the end of Rio Tinto’s active diamond mining operations, highlighting a wider shift in the natural diamond industry as established sources of rough diamonds reach the end of their productive lives.
Rio Tinto’s rough diamond production fell sharply during the first nine months of 2026, following the closure of its Diavik mine in Canada. According to the mining group’s latest production figures, the company recovered approximately 1.074 million carats during the period, down from 3.317 million carats in the corresponding period of 2025.
The decline of approximately 68% reflects the winding down of operations at Diavik, which produced its final diamonds in March 2026 after 23 years of operation.
The figures underline a significant development for the global diamond industry: Rio Tinto, once one of the world’s most prominent diamond producers, has now ended active diamond mining operations.
Diavik’s closure ends an important chapter
Located in Canada’s Northwest Territories, Diavik was a major source of natural rough diamonds for more than two decades. During its operating life, the mine produced more than 150 million carats.
Mining activity concluded in March 2026 after the deposit’s economically recoverable reserves were exhausted. Although production has ceased, Rio Tinto has indicated that it will continue processing and selling its remaining diamond inventory through at least the end of 2026.
Diavik’s closure follows the shutdown of Western Australia’s Argyle diamond mine in November 2020. Argyle was internationally recognised for its extraordinary pink and red diamonds, alongside its substantial production of other natural diamonds.
For further background, read DCLA’s coverage of the Diavik mine expansion and its final years of operation and the closure of the Argyle diamond mine.
Rio Tinto shifts its focus away from diamonds
The end of production at Diavik represents the latest stage in Rio Tinto’s withdrawal from much of the diamond sector.
The company closed Argyle in 2020 and subsequently exited its interest in the Fort à la Corne diamond exploration project in Saskatchewan, Canada. Its broader business strategy has increasingly focused on other commodities, including iron ore, copper and other minerals.
Rio Tinto continues to explore for diamonds in Angola, but it no longer has an operating diamond mine producing rough stones.
The distinction between mining and selling is important. Existing inventories can continue to reach the market after a mine closes, meaning that the end of production does not immediately eliminate all supply from that source.
What does declining mine production mean for natural diamonds?
The reduction in Rio Tinto’s diamond output comes amid wider changes across the natural diamond industry. Producers have been dealing with challenging market conditions, shifting consumer preferences and competition from laboratory-grown diamonds.
However, declining production alone does not guarantee higher diamond prices. Prices also depend on consumer demand, the quality and size of available stones, inventories held throughout the supply chain and broader economic conditions.
DCLA has examined these competing pressures in its coverage of declining rough diamond supply and the changing outlook for natural diamond prices.
The market is not uniform. Commercial-grade natural diamonds can experience very different pricing conditions from exceptional stones with unusual colour, size, clarity or historical significance.
Argyle’s legacy and the rarity of natural pink diamonds
The closure of Argyle is particularly significant for the fancy-coloured diamond market. For decades, the Western Australian mine was the world’s leading source of rare pink diamonds, producing stones that became highly sought after by collectors and luxury jewellers.
Unlike a mine that temporarily suspends production, a permanently closed deposit cannot supply newly mined diamonds once its remaining inventory has been exhausted. Existing stones can, however, continue to circulate through private collections, auctions and the jewellery trade.
DCLA recently reported on Boodles’ acquisition of the remaining Argyle Pink Diamonds inventory, demonstrating how the legacy of a closed mine can continue to influence the market years after mining ends.
The history of Argyle also illustrates why provenance, documented origin and rarity can matter when assessing exceptional natural diamonds.
The importance of independent diamond expertise
As the diamond industry evolves, understanding the differences between natural and laboratory-grown diamonds, assessing quality accurately and verifying relevant documentation remain important for consumers, jewellery businesses and collectors.
A diamond’s value cannot be established from its carat weight alone. Colour, clarity, cut, proportions, treatments, market conditions and, where relevant, provenance all contribute to an assessment.
DCLA provides independent diamond examination and reporting services to help clients understand the characteristics of their diamonds. Its work supports informed decisions in a market where the distinction between different diamond types and qualities is increasingly important.
The bigger picture: Rio Tinto’s exit from active diamond mining is a reminder that natural diamond production depends on finite geological resources. While the effect of declining supply will vary across the market, the closure of major mines is reshaping the industry’s long-term supply landscape.
For further information about diamond examination and reporting, visit DCLA.


No comments:
Post a Comment