Showing posts with label russia. Show all posts

Monday, 14 September 2026

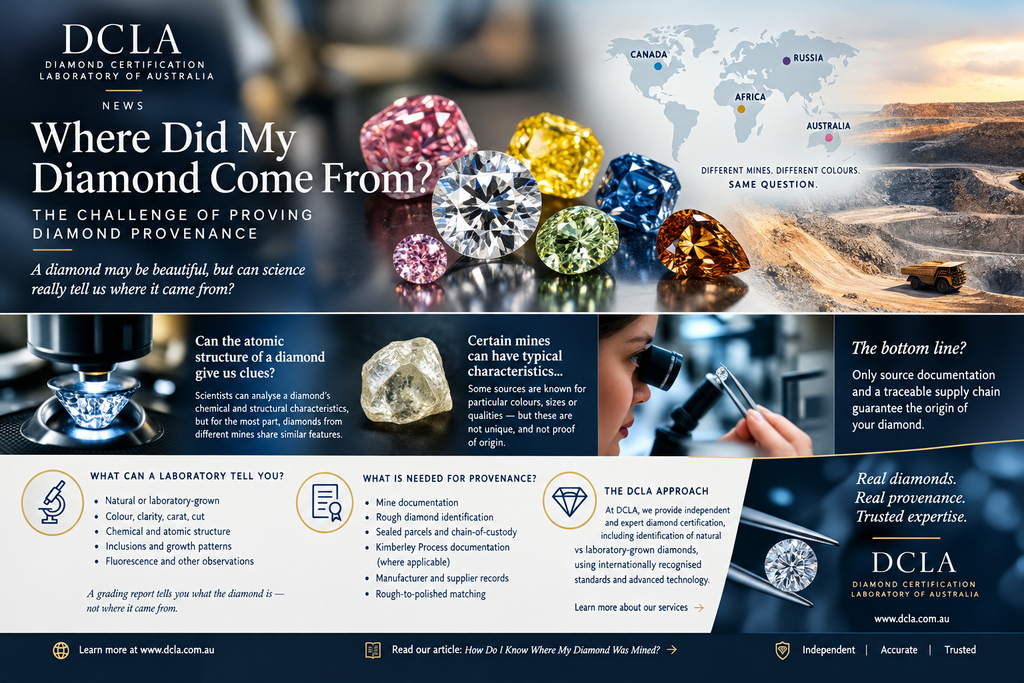
Where Did My Diamond Come From?

 How can you prove the provenance of a polished diamond?

How can you prove the provenance of a polished diamond?

When buying a natural diamond, one question is becoming increasingly important:

Where did it come from?

A diamond may have been mined in Botswana, South Africa, Canada, Australia, Angola, Namibia, Lesotho, Russia or one of the many other diamond-producing regions around the world. But once that rough diamond has been cut and polished, can a laboratory actually look at the finished stone and determine which mine it came from?

For the vast majority of polished diamonds, the answer is no.

This is an important distinction between identifying what a diamond is and identifying where it came from.

A gemmological laboratory can examine a polished diamond and determine many things about it, including its natural or laboratory-grown origin, colour, clarity, carat weight and other characteristics. But determining the geographic origin of a natural diamond is a very different scientific problem.

DCLA has previously addressed the difficulty of determining where a diamond was mined and the importance of documentation and traceability. DCLA: How Do I Know Where My Diamond Was Mined?

Can the atomic structure of a diamond reveal its mine?

This is where the science becomes particularly interesting.

A diamond is made primarily from carbon atoms arranged in a highly organised crystal structure. Small amounts of nitrogen, boron and other trace elements can also occur within the crystal.

Scientists can examine characteristics such as:

  • Crystal structure
  • Nitrogen characteristics
  • Trace elements
  • Isotopic composition
  • Inclusions
  • Growth patterns
  • Spectroscopic characteristics
  • Fluorescence and luminescence

These characteristics can sometimes provide clues.

The problem is that diamonds from different mines can share remarkably similar geological and chemical characteristics.

Research published by the Gemological Institute of America has found that diamond characteristics overlap extensively between deposits around the world. There is currently no scientifically robust method that can independently determine the geographic origin of a random individual polished diamond simply by analysing the stone.

In other words, the atomic structure can tell scientists a great deal about a diamond but for most polished diamonds, it cannot provide a unique geographic fingerprint saying, for example, “this diamond came from Mine X.”

Diamonds from particular mines can have characteristics but that is not proof

This does not mean that diamonds from particular mines are completely indistinguishable.

Certain mines and deposits can become associated with particular characteristics.

For example, some sources have become famous for producing particular sizes, qualities or colours of diamonds. The Argyle mine in Australia became particularly associated with pink and other rare coloured diamonds, while the Cullinan mine in South Africa became famous for producing exceptionally large, high-quality diamonds.

However, these associations are not the same thing as scientific proof of origin.

A diamond may display characteristics that are more common in diamonds from a particular locality without those characteristics being exclusive to that locality.

As GIA research explains, experienced professionals may sometimes make an educated assessment of the likely origin of certain rough diamonds or parcels. But for the majority of polished diamonds, there are no distinctive characteristics that independently reveal their geographic origin.

This distinction is particularly important when a diamond is being marketed with a premium based on its supposed geographical origin.

“This diamond looks like it could have come from that mine” is not the same as “this diamond has been proven to have come from that mine.”

What happens when the diamond is polished?

The journey from rough to polished is critical.

A rough diamond can contain information that is lost or altered when it is cut and polished. Surface characteristics disappear, inclusions may be removed or avoided during cutting, and the original crystal shape is transformed into a finished gemstone.

This makes retrospective identification extremely difficult.

GIA’s research describes the problem clearly: the characteristics of diamonds from different geological environments overlap, while gem-quality diamonds contain extremely low concentrations of many trace elements. The research concludes that, at present, reliable diamond provenance depends on retaining origin information from the time of mining rather than attempting to determine the origin analytically after the fact.

So how can the origin of a polished diamond actually be proven?

The answer is traceability.

Instead of trying to work backwards from the finished diamond, the origin needs to be established at the beginning of the diamond’s journey.

One of the strongest scientific approaches is to analyse the rough diamond when its origin is documented, record its characteristics, and then match the resulting polished diamond back to that original rough.

This is the principle behind the GIA Diamond Origin Report.

GIA requires the rough diamond to be received in a documented, sealed and tamper-resistant parcel directly from the mining company. The rough is analysed and assigned an identification number. After cutting and polishing, the finished diamond can then be submitted and scientifically matched against the original rough.

The matching process can use a combination of physical measurements, spectroscopy, imaging and other characteristics recorded from the rough.

This is fundamentally different from taking an unknown polished diamond and attempting to guess its mine of origin.

What about the Kimberley Process?

The Kimberley Process is also an important part of the broader diamond supply chain.

It was established to prevent the international trade in conflict diamonds and provides a system of controls surrounding the international trade in rough diamonds.

DCLA’s own terms and conditions require diamonds listed through its website to have been imported under the Kimberley Process.

However, it is important to understand what this means.

A Kimberley Process certificate and supply-chain documentation can provide important evidence concerning the legal movement and declared origin of rough diamonds, but it is not the same as a gemmological laboratory looking at an unknown polished diamond and scientifically determining its mine.

What does a normal diamond certificate prove?

A diamond grading report is extremely useful, but consumers should understand what it does and does not establish.

A conventional grading report can document characteristics such as the diamond’s:

Carat weight
Colour
Clarity
Cut
Measurements
Proportions
Fluorescence and other laboratory observations

It may also identify whether a diamond is natural or laboratory-grown, depending on the laboratory and examination performed.

But a standard grading report does not automatically establish the mine where a natural diamond was extracted.

DCLA has also warned consumers about another important issue: a legitimate grading certificate can sometimes be presented with a different stone. The laboratory’s recent consumer alert highlights why matching the physical diamond to its report and verifying inscriptions and characteristics is so important.

You can read more about DCLA’s approach to diamond identification and certification through the DCLA Diamond Certification Laboratory.

What about coloured diamonds?

The situation becomes particularly interesting with natural coloured diamonds.

Certain geographic sources have become strongly associated with particular colours and colour ranges.

Australia’s Argyle mine, for example, became internationally famous for its pink diamonds. Other deposits have produced distinctive populations of yellow, blue, brown and other coloured diamonds.

Colour, hue and saturation can therefore sometimes provide useful clues about a possible source.

But again, a clue is not proof.

A particular colour may be much more frequently encountered from one locality than another, while similar colours can occur elsewhere.

The same principle applies to other characteristics such as inclusions, growth features and trace chemistry.

A laboratory may be able to say that a stone displays characteristics that are consistent with diamonds seen from a particular source. That does not necessarily mean the laboratory can prove that the individual diamond came from that mine.

The difference between identification and provenance

This is perhaps the most important distinction for consumers.

Identification asks:

What is this diamond?

Provenance asks:

Where did this particular diamond come from and can its journey be documented?

A laboratory can provide powerful scientific evidence about the first question.

The second question requires something more: a chain of evidence connecting the individual diamond to its source.

That evidence can include:

  • Mine documentation
  • Rough diamond identification
  • Sealed parcels
  • Export documentation
  • Kimberley Process documentation where applicable
  • Manufacturer records
  • Rough-to-polished matching
  • Laser inscriptions
  • Grading reports
  • Purchase invoices
  • Supplier records
  • Chain-of-custody documentation
  • Verified digital traceability systems

Documentation is the key to provenance

The simplest way to think about diamond provenance is this:

You cannot reliably create provenance after the diamond has lost its documented history.

If a diamond is mined, mixed with thousands of other diamonds, sold through several companies, cut and polished, and eventually appears years later without its original documentation, scientific examination may be unable to reconstruct its exact mine of origin.

By contrast, if the diamond’s identity is established at the mine and maintained throughout the manufacturing process, its journey can potentially be verified.

This is why modern diamond traceability systems are becoming increasingly important.

GIA itself has stated that there is currently no scientific method capable of determining country of origin simply by examining a random natural diamond. Its origin services instead rely on verified origin information and scientific matching between the rough and polished diamond.

The DCLA view

At DCLA, we believe consumers should be given a clear distinction between what can be scientifically established and what may simply be an educated opinion.

Diamonds from certain mines can share characteristics. Certain colours, qualities, inclusions and growth features may occur more frequently in particular deposits.

But the majority of gem-quality white diamonds, once polished, do not carry a unique scientific fingerprint that allows their mine of origin to be established with certainty.

And while some coloured diamonds may display characteristics strongly associated with particular sources, those characteristics are not automatically proof of origin.

The bottom line is simple:

If you want to know where your diamond came from, look at the chain of evidence not just the appearance of the stone.

A diamond grading report can tell you what the diamond is.

Scientific examination can identify many of its characteristics.

But provenance comes from being able to connect that individual diamond to its documented source.

For a diamond whose geographic origin is important to the buyer, the strongest evidence is documentation and traceability maintained from the rough diamond through cutting, polishing and sale.

In the world of diamond provenance, a good story is not the same as proof.

The most valuable provenance is the provenance that can be documented, verified and traced back to the source.

For further information on diamond identification, certification and laboratory-grown diamond detection, visit DCLA – Diamond Certification Laboratory of Australia and explore DCLA’s educational resources, including DCLA’s article on diamond mine origin and DCLA’s information on natural and laboratory-grown diamonds.

Independent research

For further scientific reading, GIA’s research on the geographic origin of diamonds explains the limitations of current analytical methods and why documented origin information remains essential. GIA: Methods and Challenges of Establishing the Geographic Origin of Diamonds

GIA also explains its rough-to-polished scientific matching process through its Diamond Origin Report service.

Wednesday, 24 June 2026

Natural Diamonds Show Resilience Through Transparency, Producer Growth and Global Market Evolution

 DRC Artisanal Diamonds Achieve Strong Results in Antwerp Auction

DRC Artisanal Diamonds Achieve Strong Results in Antwerp Auction

Artisanal diamonds from the Democratic Republic of Congo (DRC) have achieved a positive result in Antwerp, selling above expectations in a landmark auction designed to improve market access for small scale diamond producers.

The sale, organised by the Antwerp World Diamond Centre through its OrigemA programme, featured 103.77 carats of fully traceable rough diamonds sourced from artisanal mining cooperatives in the DRC.

The diamonds achieved an average price of $66 per carat, exceeding the estimated market value of $58 per carat. The total sale value reached approximately $6,000, demonstrating the potential for responsibly sourced artisanal diamonds to compete successfully in the international marketplace.

OrigemA was created through collaboration between Belgium and the DRC to connect artisanal miners with global diamond markets. The programme aims to ensure that more value from diamond production remains within local communities, supporting areas such as mining development, agriculture, healthcare and education.

Karen Rentmeesters highlighted that the auction demonstrated Antwerp’s continued role as a leading rough diamond trading centre, where international competition helps achieve fair market pricing.

The result also reflects a wider industry movement toward greater transparency, traceability and responsible sourcing as consumers increasingly seek confidence in the origins of natural diamonds.

Diamond Industry Adapts as Producer Countries Take a Greater Role

The natural diamond industry continues to adjust to changing consumer behaviour, economic uncertainty and evolving market conditions. However, industry leaders believe important foundations are being created for future growth.

World Federation of Diamond Bourses president Yoram Dvash noted that one of the most encouraging developments is the increasing participation of African producer nations across the diamond value chain.

Countries including Botswana and Angola have strengthened their involvement through their affiliation with the WFDB, while other producing nations such as Rwanda are also seeking a larger role in shaping the future of the diamond sector.

This reflects a broader shift where producer countries are looking beyond mining and becoming more involved in trading, manufacturing, marketing and value creation.

The potential future ownership changes surrounding De Beers, currently controlled by Anglo American, further highlight the changing structure of the global diamond industry.

Greater participation from producing countries could create stronger alignment between miners, manufacturers, traders and retailers, helping build a more balanced and sustainable diamond ecosystem.

Traceability and Consumer Confidence Become Industry Priorities

Transparency remains a major focus for the diamond sector as companies work to strengthen consumer trust.

The acquisition by Gemological Institute of America of a stake in De Beers’ Tracr platform represents continued movement toward verified diamond provenance and digital traceability.

As laboratory grown diamonds become more prominent in the market, the natural diamond industry is placing increasing emphasis on communicating the rarity, geological history and emotional value of natural diamonds.

Industry leaders continue to stress the importance of investment in marketing and education to help consumers understand the differences between natural and synthetic diamonds.

Russia Holds the Largest Share of Global Diamond Reserves

Global diamond supply remains concentrated among a small number of countries, with Russia holding the largest known reserves.

Russia accounts for almost half of the world’s diamond reserves, significantly ahead of Botswana, which holds approximately 250 million carats, representing around 14.7% of global reserves.

Other major reserve holders include Angola and the Democratic Republic of Congo, each with approximately 150 million carats, while South Africa holds around 87 million carats and Zimbabwe approximately 56 million carats.

Together, Russia and Botswana account for close to 60% of global diamond reserves, highlighting the concentration of future supply potential.

Africa continues to play a central role in the natural diamond industry, with Botswana, Angola, the DRC, South Africa and Zimbabwe collectively representing a significant share of known reserves.

The Future of Natural Diamonds

The diamond industry is entering a period of transformation. Greater producer involvement, improved traceability, responsible sourcing and renewed consumer education are reshaping the market.

While challenges remain, the continued focus on transparency and cooperation across the diamond pipeline provides a pathway toward a stronger future for natural diamonds.

The industry’s ability to adapt while preserving the rarity and uniqueness of natural diamonds will remain central to maintaining consumer confidence and long term value.

Source: DCLA

Friday, 5 June 2026

Unseen Imperial Russian Jewels for Sale

 Rare Imperial Russian jewels, including Catherine the Great's diamonds

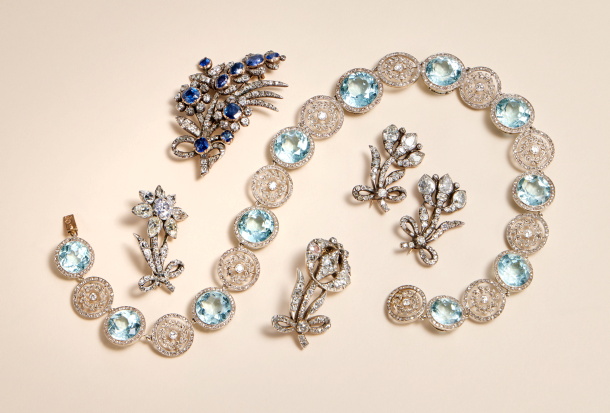
Rare Imperial Russian jewels, including Catherine the Great’s diamonds, and a Faberge necklace from the reign of Nicholas II, are to be offered for sale by Sotheby’s New York.

“It is difficult to overstate their rarity and historical importance,” said the auction house as it announced its Artistic Luxury: Faberge, Gold Boxes, Silver & Ceramics Art sale, on 17 June.

 “These jewels carry with them a fascinating window into the luxury and opulence of the Russian Imperial court.”

They were confiscated as part of the Russian State Jewels by the Soviet government after the 1917 revolution and have not been seen for over a century.

Three lots – all silver and diamond-set flower dress trimming by Louis David Duval of Geneva – belonged to Catherine the Great (1729 – 1796), with estimates between $30,000 and $80,000.

They were sold by Christie’s on behalf of the Soviet People’s Commissariat of Finance in 1927 to a noted dealer and are currently in a private European collection. 

Also being offered for sale is a larger trimming, of diamonds and Ceylon sapphire, that belonged Catherine’s predecessor, Empress Elizabeth Petrovna (1741-1762). Estimate $40,000 – $60,000.

Highlight of the sale is an Imperial Faberge diamond and aquamarine necklace from the reign of Emperor Nicholas II (1868 – 1918) with an estimate of $400,000 – $600,000.

Source: DCLA

Tuesday, 16 December 2025

Alrosa Upbeat, Despite Tariffs and Lab Growns

Alrosa diamond mining

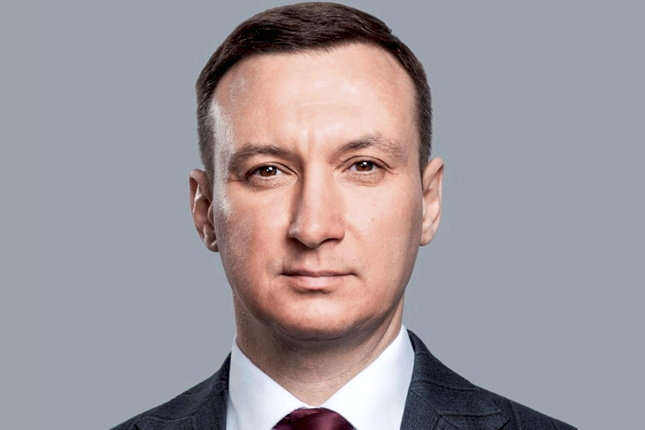
Alrosa CEO Pavel Maryinchev gave a remarkably upbeat assessment of the natural diamond market, telling the Times of India (TOI) that the industry is adapting well to US tariffs and that the threat from synthetic diamonds is diminishing.

Maryinchev (pictured) highlighted two major factors behind his optimism: steady global demand for jewelry and a decline in diamond production. “Inventories throughout the diamond pipeline are gradually normalizing, creating favorable conditions for price recovery,” he said.

Alrosa CEO Pavel Maryinchev

Alrosa, Russia’s state-owned and sanctioned diamond miner, reported a 24 per cent drop in revenue in the first half of 2025 and has suspended production at several low-margin mines.

But Maryinchev remains confident. “Our expectations are that the high import tariffs will not have a long-lasting impact, and businesses will be able to adapt and minimize the effect,” he said.

He also pointed to a significant decline in wholesale prices for lab-grown diamonds, which fell nearly 40 per cent year-on-year in Q3 2025, reducing the competitive pressure on natural stones.

“Fears that synthetic substitutes might replace natural diamonds are becoming less likely to come true every year,” he told TOI.

He noted that, with no major new deposits discovered and existing mines producing less, supply constraints are increasingly stabilizing the market.

Global rough diamond production is expected to fall to 100 million carats in 2025, a 30-50% decline compared to six to eight years ago.

Maryinchev said the effect of US tariffs on demand was muted because luxury jewelry buyers tend to be less price-sensitive, and retailers can temporarily adjust markups.

“Diamond jewelry manufacturers may need time to adapt, but we expect India’s demand to recover once the first positive sales figures post-tariffs are achieved,” he said.

Source: DCLA

Thursday, 7 August 2025

Double Whammy: Trump Hikes India Tariff to 50%

Trump Hikes India Tariff to 50%

US President Donald Trump today (6 August) doubled the tariff on all imports from India to 50 per cent, as a punishment for its oil purchases from Russia.

India’s diamond industry, already reeling from confirmation last week of a 25 per cent reciprocal tariff, is in shock that their goods will be subject to a second 25 per cent surcharge.

“I find that the Government of India is currently directly or indirectly importing Russian Federation oil,” Trump said in an executive order.

“Accordingly, and as consistent with applicable law, articles of India imported into the customs territory of the United States shall be subject to an additional ad valorem rate of duty of 25 per cent.”

The first 25 per cent tariff comes into force tomorrow (Thursday 7 August) and the new, punitive tariff is applicable three weeks from now, on 27 August.

The US is the single largest destination for Indian diamonds and gems, accounting for nearly $10bn or about 30 per cent of India’s annual gems and jewelry exports.

Industry leaders were already warning of the dire consequences of a 25 per cent tariff. Now they are facing an unprecedented body blow with the introduction of a 50 per cent double-tariff.

India’s Ministry of External Affairs said in a statement today that the tariffs were “unfair, unjustified and unreasonable”.

It defended its Russian oil purchases, saying they were “based on market factors and done with the overall objective of ensuring the energy security of 1.4 billion people of India”.

The US imposition of an extra tariff was, it said, “extremely unfortunate”.

Source: DCLA

Wednesday, 25 June 2025

Russia Still World’s Biggest Diamond Producer

Russia Alrosa Diamonds

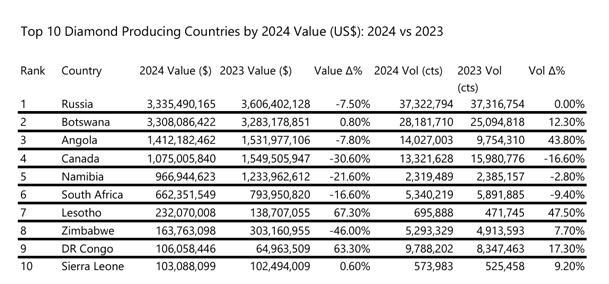
Russia remained the biggest rough diamond-producing country in the world in 2024, by both volume and value, despite the impact of G7 sanctions.

By volume it accounted for 32 per cent of global production in 2024 – or 37.3m carats – according to newly-released figures by the Kimberley Process Certification Scheme.

And by value it accounted for 29 per cent – or $3.335bn.

Botswana came second by volume – 24 per cent, 28.2m carats – and a very close second by value – 28.8 per cent, $3.308bn.

Overall global rough output fell 10 per cent to $11.48bn.

India was the biggest importer (40 per cent by carats, 39 per cent by dollars) followed by UAE (29 per cent by carats, 24 per cent by dollars).

Source: DCLA

Monday, 7 April 2025

Mining Company Alrosa Unveils Russia’s Largest-Ever Diamond

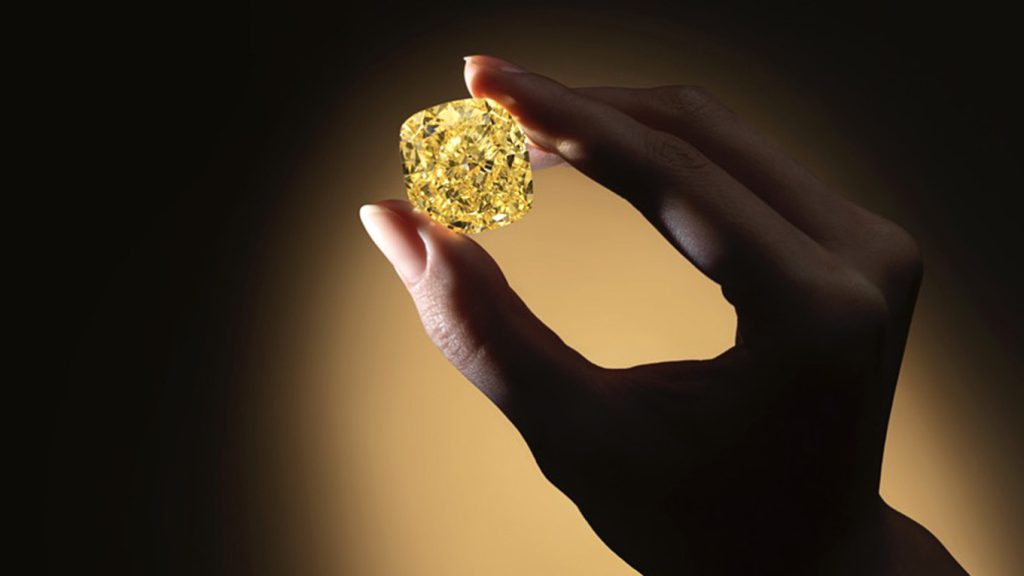
The 100-carat vivid yellow stone named New Sun

Russian diamond producer Alrosa announced Friday that it finished the two year cutting process of the country’s largest ever diamond a 100 carat vivid yellow stone named New Sun.

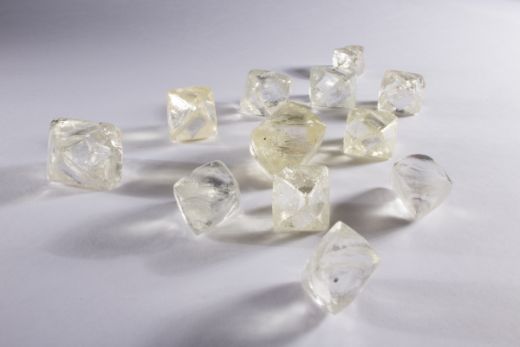
New Sun was cut from a billion year old 200 carat rough diamond, which was unearthed from an ancient riverbed at the Ebelyakh mine in the Far East republic of Sakha (Yakutia).

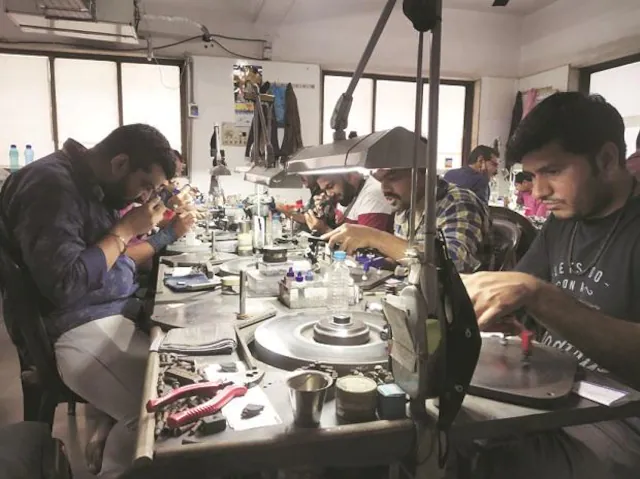
Alrosa said 15 of Russia’s top jewelers worked meticulously to “achieve the perfect balance between light, color and the play of shades.”

“Thanks to the highest skill of Russian experts, the diamond has acquired impeccable proportions that accentuate its depth and brightness of its sunny hue,” the company said.

The cutting process marks a “new stage” in the development of the Russian Cut, a gem cutting technique known for its precision and brilliance, Alrosa said.

“New Sun is one of the most significant events in the gemstone industry in recent years, highlighting Russia’s high status in the global diamond industry,” the company said.

Last month, Alrosa announced the temporary suspension of operations at several less profitable sites, reducing annual production by less than 1 million carats. The company still plans to produce 29 million carats of diamonds in 2025.

Alrosa, which is under an EU and G7 import ban, is the world’s largest diamond mining company by volume. It cut production by 2.8% to 34.6 million carats in 2023 and by 4.6% to 33 million carats in 2024.

Source: DCLA

Monday, 10 March 2025

Alrosa set to Sell More Rough to Government

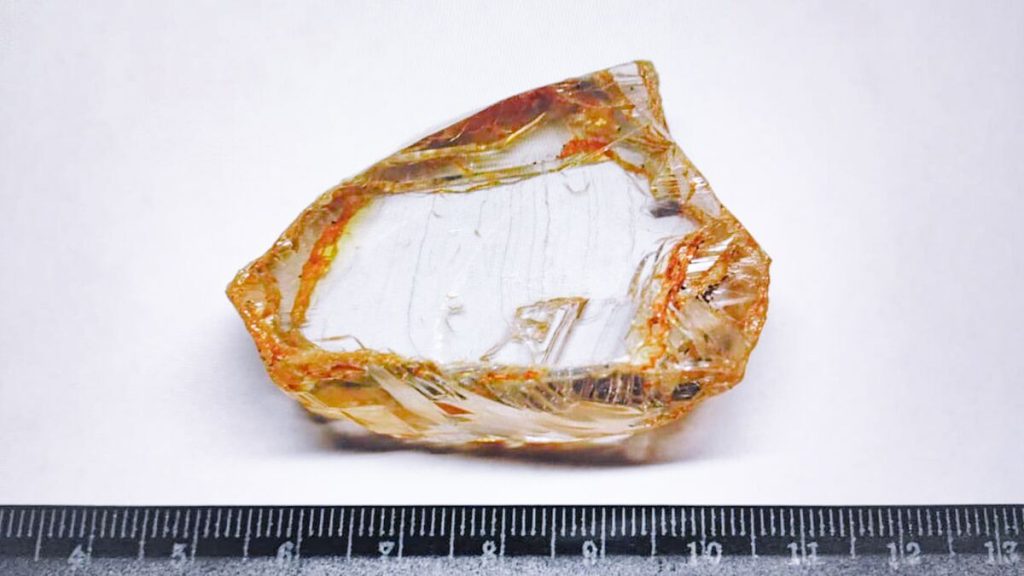
Alrosa Rough diamond weighing 390.7 carats

                                       Rough diamond weighing 390.7 carats

The Russian government could buy more rough diamonds from the state-run miner Alrosa, as it faces ongoing G7 sanctions and weak global demand.

The Finance Ministry says it will assess the situation after seeing second quarter results.

Alrosa last week reported a 77 per cent slump in profits for 2024 (down to $223m) and has said it could suspend some less profitable activities and lay off some of its 35,000 workers.

“As we have already said, it is possible that Gokhran will buy some of the stones, said Deputy Finance Minister Alexey Moiseyev, according to a report by the privately-run Interfax news agency.

“At this stage, we are still observing the market dynamics, indeed, it is quite weak, but not much time has passed. In principle, the first quarter is rarely good.”

Alrosa has previously offloaded excess inventory to Gokhran, the Russian State Precious Metals and Gemstones Repository in times of weak demand.

During the financial crisis of 2009 Gokhran bought up $1bn of Alrosa’s diamonds. And it sold back millions of carats in 2022, when a surge in post-lockdown demand outstripped the miner’s production capacities.

Last November it said it would be selling a batch of rough diamonds, including its largest recovery in a decade – an irregular-shaped diamond weighing 390.7 carats

Source: DCLA

Monday, 10 February 2025

US Diamond Importers Must Declare Country of Origin

New rules announced by US Customs and Border Protection (CBP) will require all diamond importers to declare the country of origin of all goods.

New rules announced by US Customs and Border Protection (CBP) will require all diamond importers to declare the country of origin of all goods.

The move, to be implemented in April, is aimed at enforcing sanctions on Russian diamonds.

Importers have been required, since last March, to certify that their goods are not Russian, but not to disclose where they are from.

The G7 nations – including the US and EU – imposed a ban on Russian diamonds of 1 carat or more from March 2024 and on goods of 0.5 carats or above from September 2024.

Despite the sanctions, Russia is still thought to be exporting 40 per cent of its diamonds output because they are below the size threshold or industrial quality.

The US Customs and Border Protection (CBP) said in a statement that it plans to start collecting additional data in April on jewelry imports (and seafood) requiring filers to provide the country of mining.

They’ll be required to upload a PDF document on official company letterhead to CBP’s automated commercial environment (ACE) document image system.

The requirement applies to both loose diamonds and jewelry containing diamonds. Jewelry imports without diamonds are exempt.

The carat size threshold is not mentioned in the CBP announcement.

Source: IDEX

Friday, 22 November 2024

Russia to continue buying diamonds through state fund in 2025

Russia to continue buying diamonds through state fund in 2025

Russia will continue to buy diamonds through a state fund in 2025 in order to support the diamond industry and market, Deputy Finance Minister Alexei Moiseev said on Thursday.

The Russian budget for 2025-2027 has set aside $1.55 billion for the purchase of precious metals and gems, Moiseev said in a statement.

Sign Up for the Precious Metals Digest

Russia will continue to ensure “stable global rough diamond prices in the wake of oversupply in the current market,” the same statement said.

State-owned precious metals and gems repository Gokhran resumed buying diamonds from Alrosa in March 2024. Alrosa, under US and EU sanctions, is the world’s largest producer of rough diamonds by volume with 30% of the market.

Source: DCLA

Wednesday, 28 August 2024

US Sanctions Russian Diamond Cutter and Retail Jeweler

jewelry brand Miuz and the diamond cutter Kristall

The US has added the prominent jewelry brand Miuz and the diamond cutter Kristall to its list of sanctioned companies in Russia.

Kristall, Russia’s largest diamond cutter, is now on the Specially Designated Nationals (SDN) List administered by the US Treasury Department.

Alrosa, its parent company has been on the list since April 2022, shortly after Russia invaded Ukraine. Kristall, based in Smolensk, has been part of the Alrosa group since 2019.

Miuz Diamonds, which has production facilities in Moscow and Perm and a chain of 300 retail outlets, has also been added to the list.

Miuz is part of the Ruiz Group of diamond and jewelry enterprises, linked to Israeli billionaire Lev Leviev.

It is not clear why the companies were not sanctioned sooner.

Kristall and Miuz are among almost 400 individuals and entities in Russia and beyond its borders that were added to the SDN list last Friday (23 August).

“Russia has turned its economy into a tool in service of the Kremlin’s military industrial complex,” said Deputy Secretary of the Treasury Wally Adeyemo, announcing the additions.

“Treasury’s actions today continue to implement the commitments made by President Biden and his G7 counterparts to disrupt Russia’s military-industrial base supply chains and payment channels.”

Source: DCLA

De Beers London launches Vibrations

  De Beers London presents Vibrations: a High Jewellery universe inspired by the quiet yet enduring power of inland water. The collection ce...